

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Pharmaceutical Dyes Market to Grow at a 5.52% CAGR, According to 2025 Insights

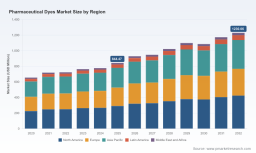
Worldwide Pharmaceutical Dyes Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s newest market intelligence brief, Worldwide Pharmaceutical Dyes Market: Strategic Outlook (base year 2025; historical analysis 2020–2025; forecast period 2026–2032), distills the actionable insights life‑science leaders need to shape decisions in 2026. The report documents a resilient industry that expanded through the first half of the decade and, under a set of near‑term scenarios, is projected to continue growing at a compound annual growth rate of 5.52% across the forecast window. In short: the industry is neither a backwater nor a breakout — it is a mature specialty market where operational execution, regulatory agility, and strategic positioning will determine winners.
Worldwide Pharmaceutical Dyes Market
Why 2026 Is a Strategic Inflection Point
Two parallel dynamics elevate the importance of decisions taken in 2026. First, cost and raw‑material volatility have tightened margins for manufacturers and suppliers alike. Notably, aniline — a primary feedstock for many azo dye chemistries — rose roughly 12% in Q4 2024 to near USD 1,850/MT, translating quickly into higher intermediate costs for synthetic colorants and pressuring procurement strategies.
Worldwide Pharmaceutical Dyes Market
Second, regulatory tightening and heightened import scrutiny are reshaping product compliance thresholds. Recent regional and pharmacopeial changes — for example, lowered permissible lead levels in iron oxide pigments and stricter light‑stability requirements for aluminum lakes — are forcing formulators and colorant suppliers to invest in reformulation, enhanced testing protocols, and traceable supply chains. Further, import alerts have materially increased rejection rates in certain trade lanes, and firms that fail to embed compliance into procurement and production risk market access disruptions.
Worldwide Pharmaceutical Dyes Market
Market Structure — Concentration and Competitive Dynamics
Our market structure analysis finds moderate concentration: the three largest players account for a meaningful but not overwhelming share of industry revenue, while the top five increase that share further. This leaves space for both established producers and specialized challengers to pursue growth through technical differentiation, niche positioning (e.g., natural, clean‑label colorants), and targeted M&A.
- Consolidation pressure: The industry’s CR3 and CR5 metrics indicate room for bolt‑on acquisitions to accelerate scale, broaden regulated product portfolios, and enhance geographic coverage.
- Specialist opportunity: Natural and clean‑label solutions have rising traction among formulators targeting end‑market differentiation, regulatory favorability, and marketing advantages in self‑care and consumer health segments.
- Vertical integration risk/benefit: Buyers with in‑house pigment blending or coating capability can capture margin and speed, but must weigh capital exposure against outsourced, compliance‑certified suppliers.
Competitive Landscape — What the Leading Suppliers Signal
The market’s competitive ledger is defined by a mix of global chemical majors, specialty pigment firms, natural‑ingredient specialists, and regional producers. Key strategic moves from recent quarters point to differentiated routes to capture value:
- Sensient Technologies Corporation (Milwaukee, WI) has doubled down on process‑robust color dispersions for high‑shear coating operations. Its recent product launch emphasizes stability in challenging manufacturing environments — a clear signal that coating reliability is a procurement priority for large formulators.
- Clariant AG (Muttenz, Switzerland) continues to leverage excipient branding and certification strategies (including expanded Halal coverage). Certification and monograph‑alignment remain decisive buying criteria for global supply chains.
- BASF SE (Ludwigshafen, Germany) has invested in capacity expansion for pharmaceutical‑grade iron oxides, anticipating renewed demand — a tactical bet on scale efficiency and assurance of supply amid upstream constraints.
- GNT Group (Mierlo, Netherlands) is the exemplar for natural, fruit‑ and vegetable‑derived colorants aimed at clean‑label formulations — an important growth vector for OTC and consumer health manufacturers seeking to differentiate on label claims.
- Kolor Jet Chemical Pvt Ltd (Vapi, India) and Sun Chemical Corporation (Parsippany, NJ) illustrate the sustained role of regional producers and pigment specialists that combine regulatory compliance (e.g., FD&C/D&C, Halal, Kosher) with competitive export models.
Taken together, these moves indicate an industry balancing product innovation (stability, natural alternatives) with certification and scale. For buyers, the emerging playbook is to treat colorants not as commodity inputs but as regulated, differentiating components of formulation strategy.
Regulatory and Supply Risk Dynamics
Regulatory changes in 2023–2024 are not academic; they are operationally material. Two examples illustrate the point:
- EU action lowering permitted lead in iron oxides tightened supplier specifications and testing regimes, requiring additional supplier validation and remediation timelines.
- USP’s updated monographs introduced more stringent photostability testing for aluminum lakes, which has immediate implications for product shelf‑life claims and packaging specifications.
Compounding these are trade‑lane enforcement actions: elevated FDA import scrutiny in certain source markets led to an observable spike in rejections during 2024, demonstrating that compliance gaps can abruptly remove supply options and force costly last‑minute sourcing shifts.
What PW Consulting’s Report Delivers — Practical, Executable Content
This report was designed to be operational from day one. Clients will find a structured suite of tools and analyses that move beyond descriptive narrative to enable decision execution in 2026:
- Market sizing and trend maps with scenario modelling (base, downside, upside) calibrated to raw‑material price scenarios and regulatory tightening timelines.
- Supplier scorecards that combine technical, regulatory, and commercial KPIs — designed for procurement RFPs and supplier rationalization exercises.
- Regulatory risk matrix with remediation playbooks mapped to product classes (e.g., aluminum lakes, iron oxides, azo derivatives) and to likely timeframes for compliance investment recovery.
- Go‑to‑market playbooks for both incumbent suppliers and new entrants: positioning, channel strategy, formulation partnerships, and pilot‑scale commercialization checklists.
- Procurement and hedging frameworks tailored to raw‑material volatility (including sensitivity analyses tied to aniline price paths and supplier concentration scenarios).
- M&A target shortlists and valuation heuristics for roll‑up strategies focused on technical depth, certified product portfolios, and regional logistics advantage.
We intentionally designed our deliverables to be usable by cross‑functional teams: R&D, regulatory affairs, procurement, and corporate development. The report couples quantitative scenarios with step‑by‑step implementation guidance.
2026 Priorities — Tactical Recommendations for Decision‑Makers
Based on our synthesis of market dynamics, the following priorities should guide executive agendas for 2026:
- Embed regulatory conformity at the start of sourcing: Restrict RFQs to suppliers with validated testing regimes for recent pharmacopeial updates and documented traceability to avoid import disruptions and costly reformulations.
- Hedge raw‑material exposure selectively: Use a mix of multi‑sourced contracts, short‑cycle inventory, and selective forward purchases for feedstocks like aniline to balance cost and availability without creating capital drag.
- Pursue clean‑label adjacencies when they align with brand strategy: For consumer health and self‑care portfolios, prioritize pilot programs with natural colorant specialists and conduct early stability trials to quantify tradeoffs.
- Prioritize suppliers with production scale and certified capacity expansion plans: Capacity commitments — and the ability to demonstrate compliant batch release — are a strategic insurance policy against supply shocks.
- Consider bolt‑on M&A to fill technical gaps: Targets with validated pharmacopeial alignment or proprietary natural‑extraction capabilities can accelerate market access and reduce time‑to‑market for reformulated SKUs.
Investor Lens — Where Value Will Be Created
Investors should watch three vectors where value is most likely to be created between 2026 and 2032:
- Regulatory arbitrage: Suppliers that invest early in upgraded testing and certification will be able to command quality premiums and defend margins.
- Technical differentiation: Proprietary dispersions, light‑stability formulations, and natural pigment extraction processes are defensible features that reduce price elasticity.
- Supply resiliency: Firms that can demonstrably manage feedstock volatility — through integrated sourcing, geographic diversification, or contracted capacity — will garner a valuation premium.
What We Are Not Releasing Here — And Why
Consistent with our “trailer” approach, this release highlights high‑value takeaways while intentionally preserving the granular segmentation tables, regional and application revenue splits, and individual supplier scoring data that form the most commercially sensitive elements of the report. Those appendices contain the precise data points needed to underwrite specific procurement, pricing, and acquisition decisions — and are available in the full report package.
Next Steps and How to Access the Full Intelligence
For teams preparing 2026 budgets, sourcing roadmaps, product roadmaps, or M&A pipelines, PW Consulting’s full report provides the detailed datasets, supplier scorecards, and executable playbooks needed to move from strategy to execution. The full deliverable includes the proprietary financial model (with scenario toggles), validated primary interview transcripts, and regulatory compliance checklists that are absent from this preview.
Contact PW Consulting to schedule a briefing with our senior analysts and to obtain the full Worldwide Pharmaceutical Dyes Market report, including the data appendices and implementation templates that will materially shorten decision cycles and reduce execution risk in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com