

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts Worldwide High‑Performance IMU Market to Reach USD 5,532.1 Million by 2032, Growing at a 5.72% CAGR

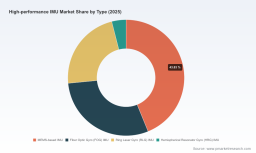
Worldwide High-performance IMU Market — Strategic Insight for 2026 Decision-Makers
PW Consulting’s new market brief on the Worldwide High-performance Inertial Measurement Unit (IMU) market provides an executive-grade synthesis designed to inform executive decisions in 2026. Using 2025 as the report’s base year and a forecast window of 2026–2032, our analysis projects the market to expand from an estimated USD 3,750.0 Million in 2025 to approximately USD 5,532.1 Million by 2032, representing a compound annual growth rate (CAGR) of 5.72%. This release functions as a strategic “trailer”: it presents rigorous, decision-ready insight while preserving the granular breakdowns and proprietary segment detail that clients access through the full report.
Worldwide High-performance IMU Market
What the report delivers — practical, transaction-ready intelligence
-
Proven forecasting methodology: transparent assumptions, sensitivity analyses, and scenario outputs for near-term (2026) and medium-term (through 2032) capital planning.
Worldwide High-performance IMU Market -
Market sizing and topline growth drivers: demand drivers across defense, navigation, marine, industrial and space segments, and the macro forces shaping adoption curves.
Worldwide High-performance IMU Market -
Technology landscape and roadmap: comparative assessment of MEMS, FOG, RLG, HRG and hybrid approaches; maturity curves and innovation inflection points.
-
Vendor benchmarking and capability matrices: strategic positioning, product differentiators, scale advantages, and go-to-market models for the leading suppliers.
-
Regulatory and compliance playbook: export-control implications (ITAR, EAR, USML), certification pathways (MIL-STD et al.), and commercial/defense segmentation strategies.
-
Procurement & integration toolkit: technical checklists, RFx templates, TCO models, environmental/qualification criteria, and supplier-risk scoring.
-
M&A and partnership screening: acquisition target shortlist, valuation multipliers, integration risk factors, and playbooks for cross-border consolidation given export controls.
-
Stress-tested scenarios: alternative demand trajectories (accelerated autonomy adoption, defense modernization waves, GNSS-denied contingencies) and recommended tactical responses for each.
Why this matters for 2026 decisions
-
Capital allocation clarity: With an objectively modeled growth trajectory to 2032 and multiple sensitivity runs, boards and investment committees can prioritize R&D and production scale investments against quantifiable upside and downside cases for 2026–2028.
-
Procurement timing: Our short-term overlays identify windows when component lead-times, certification cycles, and production ramp constraints converge — enabling procurement teams to lock in suppliers or hedge via secondary sources.
-
Technology prioritization: MEMS-based innovation is compressing the performance differential to higher-cost architectures. The report outlines where incremental sensor performance justifies premium pricing versus where cost optimization should be the priority.
-
Regulatory-informed market access: Compliance constraints materially affect go-to-market choices. The brief highlights control regimes and provides a compliance decision-tree for choosing between ITAR-governed and ITAR-free product strategies.
Competitive landscape — what incumbents and challengers are doing
The market remains moderately concentrated, with the three largest firms capturing a meaningful leadership position (CR3 ≈ 42.5%) and the top five approaching majority share (CR5 ≈ 58.8%). That structure creates a dual-track competitive environment: scale players defend mission-critical, high-margin aerospace and defense contracts, while agile specialists and MEMS innovators drive disruption at the tactical and commercial edges.
-
Honeywell International Inc. (USA): executing a product-led strategy to migrate MEMS devices into near-navigation-grade territory. Recent product introductions emphasize reduced SWaP and endurance in GNSS-denied environments — a clear signal that legacy vendors are prioritizing MEMS performance improvements to protect adjacent market share.
-
Northrop Grumman Corporation (USA): maintains a differentiated focus on space- and defense-grade FOG and HRG architectures, leveraging long-term stability and qualification pedigree. The company’s portfolio is positioned to serve missions where endurance and drift characteristics are non-negotiable.
-
Safran Electronics & Defense (France, incl. Sensonor): combining MEMS and quartz-based solutions to address tactical defense and industrial automation, with an emphasis on MIL-grade qualification and environmental robustness.
-
Thales Group (France): continuing investment in resilient navigation systems for contested and denied environments, signaling strategic emphasis on integrated solutions rather than component-only sales.
-
Analog Devices Inc. (USA), VectorNav (USA), SBG Systems (France), KVH (USA), Silicon Sensing (UK), Collins Aerospace (RTX, USA), TDK Tronics (France), Advanced Navigation (Australia), and others: together they form an ecosystem of specialization — from precision MEMS to FOG, supply-scale manufacturers, and ITAR-free challengers.
Recent industry developments underscore these dynamics: Honeywell’s HG3900 launch (June 2025) signals tactical-grade MEMS encroachment; Thales and SBG launched resilient and compass-capable MEMS products in 2025, broadening non-GNSS-reliant capabilities; Silicon Sensing reported a major production milestone (October 2025), underscoring scale; and consolidation activity, including VIAVI’s acquisition of Inertial Labs (December 2024), demonstrates active strategic buy-side interest.
Technology trends and the primary hardware bottlenecks
-
Performance convergence: MEMS innovations are closing gaps in bias instability and noise floors, enabling lower-cost tactical solutions to perform closer to mid-tier systems. However, high-stability FOG/RLG/HRG architectures retain advantages in long-duration, high-drift-sensitivity applications.
-
Persistent bottlenecks: the industry’s principal hardware challenges remain achieving low bias instability and scale-factor stability in compact packages subject to vibration and wide temperature ranges. Overcoming these limits drives premium pricing for validated solutions.
-
System-level differentiation: sensor fusion, on-board processing, and algorithmic compensation are becoming as important as raw sensor performance. Firms that combine sensor hardware with validated fusion software create higher switching costs for customers.
Regulatory, standards and supply-chain implications
Export controls and standards materially shape strategy. High-performance IMUs with military-specific modifications are frequently captured by ITAR and may be subject to USML controls; the U.S. Bureau of Industry and Security also applies EAR controls to certain dual-use inertial technologies. Concurrently, MIL-STD and environmental qualifications remain mandatory in many defense procurements. These realities mean that market access, partnership models, and M&A must be evaluated through a compliance-first lens.
-
Strategic sourcing: dual-sourcing and ITAR-free product lines can mitigate geopolitical and licensing risk and enable broader commercial expansion.
-
Localization: for firms seeking to serve defense buyers in constrained jurisdictions, localized production and qualification pathways reduce friction but require early capital planning.
-
Standards investment: certification timelines (vibration, temperature, shock) can add months to product introduction — factor these into 2026 program schedules.
Practical recommendations for executives in 2026
-
Prioritize modularity: invest in sensor-agnostic integration layers and on-board fusion to extend product longevity as sensor generations evolve.
-
Balance portfolio exposure: maintain a mix of ITAR-governed capabilities for strategic defense contracts and ITAR-free lines for commercial/global growth.
-
Lock in supply where qualification is the barrier: secure long-lead components and partner with high-volume producers to avoid ramp delays.
-
Use M&A selectively: with market concentration meaningful among top players, bolt-on acquisitions can rapidly add capability, but must be screened for regulatory complexity.
-
Embed compliance early: integrate export-control impact assessments into product design and go-to-market planning to avoid costly retrofits.
How to use PW Consulting’s full report
The brief you are reading encapsulates the strategic judgments and headline forecasts critical for 2026 decision-making. The full Worldwide High-performance IMU Market report expands on these themes with proprietary segmentation, granular region- and application-level models, supplier scorecards, supplier financial overlays, and downloadable templates for procurement and compliance. For teams evaluating capital deployment, supplier selection, or M&A in 2026, the full dataset and appendices provide the operational detail required to execute with confidence.
PW Consulting’s market intelligence combines validated quantitative modeling with practitioner-led insights to reduce execution risk. If you are preparing budgets, drafting technical RFPs, or screening acquisition targets for 2026, the report is structured to accelerate decisions while preserving the due diligence rigour your stakeholders expect.
Next steps
-
Visit our report page to access the full dataset, vendor scorecards, and downloadable procurement templates (full access required for segmentation-level data and appendices).
-
Engage PW Consulting for a tailored workshop: we map the market forecast to your product roadmaps, procurement calendars, and compliance posture to create a 100-day action plan.
In an industry where sensor performance, production scale, and regulatory posture intersect to determine winning strategies, the right intelligence can be the difference between a timely product launch and a multi-quarter delay. Our 2026-focused guidance equips boards, product leaders, and procurement teams with the context and tactical levers to act decisively — while the full report supplies the granular evidence base to execute.
For detailed analysis of this topic, please visit the official page: Worldwide High-performance IMU Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com