

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Tributyl Citrate Market Poised for Robust Growth at 5.12% CAGR, New Insight Report Finds

Worldwide Tributyl Citrate Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As global supply chains recalibrate and regulator-driven substitution accelerates, tributyl citrate (TBC) has emerged from niche status to a strategic raw material for manufacturers of flexible polymers, food-contact items, and medical-grade devices. PW Consulting’s latest market research — anchored on a 2025 base year and a historical review from 2020–2025 with forecasts through 2026–2032 — offers a forward-looking, actionable framework that senior executives and procurement leads must use to shape decisions in 2026.
Worldwide Tributyl Citrate Market
Market at a Glance: What the Numbers Tell Us
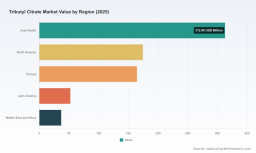
Our market sizing shows an evolving trajectory: after material volatility in the early 2020s, the global tributyl citrate market reached roughly USD 742 million in 2025. Under our base case modeling, the market is expected to expand at a compound annual growth rate (CAGR) of 5.12% over the 2026–2032 forecast window, approaching about USD 1.05 billion by 2032. That growth is neither linear nor uniform — it is shaped by regulatory shifts, raw material cycles, and structural demand changes across food, medical, and specialty polymer applications.
Worldwide Tributyl Citrate Market
Importantly, market structure analysis indicates a moderate level of concentration: a handful of global players hold disproportionate influence over technology, supply reliability, and regulatory compliance credentials. This creates both vulnerabilities and opportunities for market entrants, incumbent producers, and downstream buyers.
Worldwide Tributyl Citrate Market
Why This Report Matters for 2026 Decision-Making
- Timing: 2026 is the inflection year where regulatory substitution trends — particularly in response to phthalate restrictions — transition from early adoption to mainstream procurement requirements in several geographies. Companies that proactively align formulations and supply agreements in 2026 will capture premium access to food-contact and medical OEM programs.
- Risk Management: Our scenario-driven forecasts quantify exposure to raw material and logistics shocks, enabling procurement and operations teams to cost-effectively hedge supply and secure capacity commitments.
- M&A and CapEx Prioritization: With moderate market concentration and predictable mid-single-digit growth, targeted acquisitions and capacity expansions can deliver outsized returns if aligned to the right end-markets and regulatory certifications.
Key Strategic Dynamics Shaping 2026
- Regulatory Substitution: Policy measures restricting certain phthalates have materially increased interest in non-phthalate plasticizers. This regulatory momentum is particularly relevant for food-contact and medical applications, where certification and documentation are procurement gatekeepers.
- Raw Material Volatility: Citric acid — a primary upstream feedstock — experienced notable price spikes due to supply disruptions in late 2024. Our sensitivity modeling shows that feedstock cost pass-through and formulation optimization will be central to gross-margin preservation for producers in 2026.
- Trade & Tariff Pressures: Recent trade measures affecting imports from select origins have introduced short-term arbitrage and longer-term reshoring considerations for buyers, prompting re-evaluation of sourcing strategies and inventory buffers.
- Logistics Risk Premiums: Elevated chemical shipping rates and route disruptions have increased total landed costs. Multimodal routing and regional sourcing become economic imperatives for companies with thin margin tolerance.
- Sustainability & Bio-attribution: Demand for bio-based variants has moved beyond marketing rhetoric into procurement specifications. Firms able to document feedstock provenance and lifecycle benefits will enjoy differentiated access to certain OEMs and public tenders.
Competitive Landscape — Who Moves the Market
The competitive tableau combines multinational specialty chemical houses, regional industrial producers, and laboratory-grade suppliers. Leading firms bring differentiated capabilities:
- Large specialty producers have invested in scale and regulatory compliance to support global food-contact and medical applications. Capacity expansions and certification updates by these players have tightened premium-grade availability and raised the bar for new entrants.
- Regional manufacturers, particularly in high-volume growth corridors, offer competitive cost structures and export-ready volumes that influence spot-market dynamics and short-term pricing pressure.
- Laboratory and pharma-focused suppliers provide high-purity, USP/NF grades and play a vital role in R&D and niche medical applications where documentation and batch traceability matter most.
Recent corporate actions underscore these distinctions: notable capacity increases to meet non-phthalate demand, third-party certifications confirming food-contact compliance, and launches of bio-attributed grades that target sustainability-conscious buyers. Collectively, these moves suggest incumbents are shifting from volume playbooks to a blended strategy of compliance-led differentiation and targeted capacity investments.
Operational and Commercial Implications
- Procurement: Short-term spot exposure is rising. We recommend a mix of multi-year supply contracts for certified grades and tactical spot purchases for industrial applications to balance cost and availability.
- R&D and Product Strategy: Formulation roadmaps must prioritize substitution strategies where regulatory pressure is strongest, and embed bio-attribution where customer willingness to pay is validated.
- Supply Chain Resilience: Firms should stress-test portfolio profitability against a 10–20% citric-acid price shock and a 10–15% freight-rate increase. Scenario planning in 2026 will determine inventory policy and contingency routing investments for 2027–2028.
- Commercial Go-to-Market: Sales teams must pivot toward solution selling (regulatory dossiers, compliance documentation, supply continuity guarantees) rather than commodity-price negotiation when engaging food and medical OEMs.
What PW Consulting’s Report Delivers (Practical, Executable)
Our research package is engineered for direct use by strategy, procurement, and business development teams. Highlights include:
- Market-sizing and forecast model (2020–2032) with embedded scenario toggles to simulate regulatory, feedstock, and logistics shocks.
- Price-sensitivity and margin-impact dashboards that quantify how upstream cost changes translate to producer and buyer P&L — enabling rapid renegotiation playbooks.
- Competitive benchmarking and supplier scorecards covering technology, capacity, certifications, and geographic risk exposure — designed to support shortlists for sourcing and M&A diligence.
- Regulatory playbook and documentation templates tailored to food-contact and medical device procurement teams, including compliance checklists and audit-ready supplier qualification artifacts.
- M&A screening tool that identifies candidate targets by capability gaps, regulatory status, and scale economics — together with a transaction playbook and indicative valuation ranges for typical deal structures.
- Commercial strategies and segmented go-to-market approaches without revealing proprietary segmentation metrics in this preview — designed to swiftly convert technical compliance into revenue uplift.
Action Recommendations: 90-Day and 18-Month Horizon
- 90-Day: Run a cross-functional stress test on contracts for certified grades; prioritize supply agreements with suppliers that have proven certification trajectories and documented capacity expansion commitments. Lock in conditional contracts for high-priority OEM programs.
- 6–18 Months: Execute targeted supplier development (co-investment or offtake-linked financing) in regions that reduce tariff exposure and logistics complexity. Accelerate formulation approvals with top-tier customers by pre-submitting compliance dossiers and joint validation plans.
- M&A Window: Evaluate tuck-in opportunities in 2026 to secure regulatory-compliant capacity and shorten time-to-market for premium grades. Prioritize targets with validated documentation, traceable feedstock, and stable customer relationships.
Regulatory & Sustainability Watchlist
- Regulatory momentum away from certain plasticizers is creating durable demand for alternatives. Firms that secure early certifications and maintain audit-ready dossiers in 2026 capture disproportionate wallet share with conservative procurement teams.
- Bio-attributed product launches are shifting buyer expectations: sustainability claims must be verifiable and supported by lifecycle analysis to avoid commercial pushback.
- Trade measures and tariffs have altered the economics of global arbitrage; local production and regional supply chains are now strategic levers rather than cost centers alone.
How to Use This Preview — And Where to Go Next
This preview is intentionally strategic and integrative. It highlights the decisive variables that will govern success in the tributyl citrate value chain in 2026, but it does not disclose the granular segmentation and proprietary datasets that underpin our full-market intelligence. For procurement teams, R&D leads, and corporate strategists seeking the detailed models, supplier scorecards, and playbooks described above, the full PW Consulting report provides the calibrated inputs required to operationalize the strategies outlined here.
Accessing the complete report will provide: the full scenario model files, supplier-level benchmarking with certification timelines, a prioritized M&A target list (with supporting financials), and turnkey templates for supplier qualification and regulatory submission.
Final Thought
Tributyl citrate has evolved from an alternative plasticizer into a strategic commodity at the intersection of regulation, sustainability, and supply-chain resilience. The period beginning in 2026 will differentiate winners from laggards: organizations that integrate rigorous risk modeling, certify supply for regulated end-markets, and align commercial strategy to verified sustainability claims will capture the most value. PW Consulting’s Worldwide Tributyl Citrate Market report equips leaders with the insight and tools to make those decisions confidently — while the granular data necessary to execute those moves remains available in the full report.
To obtain the complete dataset, scenario models, and supplier playbooks, please visit our research portal (full access details and ordering information are available there).
For detailed analysis of this topic, please visit the official page: Worldwide Tributyl Citrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com