

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Underfill Market 2026: Strategic Outlook and Decision Framework — A PW Consulting Preview
As semiconductor packaging converges with AI, high-performance computing (HPC), and advanced photonics, the underfill market has moved from a niche materials play to a strategic enabler for system performance and reliability. This preview from PW Consulting — authored by our Senior Strategic Advisor and Head of Industry Analysis — outlines the high-level implications of our full Underfill Market study for corporate decision-making in 2026. We expose the structural drivers, supply-side chokepoints, and competitive dynamics you must factor into product roadmaps, procurement strategy, and M&A planning, while preserving the detailed segment-level intelligence for subscribers of the full report.
Underfill Market
Why Underfill Matters for 2026 Strategic Choices
-
Reliability as Differentiator: As flip‑chip, chip‑scale, and heterogeneous integration scale into AI accelerators, optical modules, and mobile optics, underfill chemistries determine thermal management, mechanical stress relief, and long‑term field reliability. Decisions about underfill selection now cascade into system design, warranty exposure, and service cost models.
Underfill Market -
Performance vs. Cost Trade-offs: Low‑viscosity, high‑thermal‑conductivity formulations enable larger die and tighter pitches but come at higher material and processing costs. Procurement teams must balance unit economics with lifecycle savings from reduced field failures—our full model quantifies these inflection points and payback horizons.
Underfill Market -
Supply‑chain Risk and Input Volatility: Epoxy feedstock disruptions and trade interventions are no longer episodic; they materially alter cost curves for medium and small formulators and create tactical sourcing windows for larger incumbents who can vertically integrate or lock long‑term contracts.
Macro Snapshot (2020–2032): Scale and Growth Trajectory
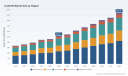
Our base-year analysis (2025) anchors historical performance from 2020–2025 and projects to 2032 under a median scenario. The market expanded markedly from 2020 through 2025, reflecting accelerating adoption across advanced packaging types and nascent optical/photonic applications. We project a mid‑single‑digit to high‑single‑digit compounded annual growth rate—9.0% in our core forecast—propelling the market into the high hundreds of millions of USD by the early 2030s.
For executives, the key takeaway is timing: the underfill market is large enough to justify targeted R&D and supplier investments, yet still concentrated enough that well‑timed moves (technology partnerships, capacity add-ons, or selective acquisitions) can secure meaningful share and margin improvement through 2032.
Competitive Landscape — Where Value Pools Are Forming
The market structure shows moderate concentration: leading specialty formulators and legacy adhesives players control a plurality of commercial supply, but a healthy cohort of regional and application‑focused vendors remains. Our competitive scan highlights several category leaders and their strategic positions:
-
Henkel AG & Co. KGaA (Düsseldorf) — Strength lies in high‑flow capillary epoxies branded for advanced packaging and large‑body flip‑chip assemblies, with recent commercial deployments targeted at AI/HPC designs that demand fast flow and reliability.
-
NAMICS Corporation (Kyoto) — A technology‑led player with formulations optimized for capillary flow and stress management in flip‑chip platforms; their R&D cadence targets miniaturization and low‑stress profiles.
-
H.B. Fuller (St. Paul, MN) — Emphasizes reworkable, fast‑flow epoxies across BGA, WLCSP, and flip‑chip — a play toward serviceable and assembly‑friendly architectures.
-
Parker LORD (Cary, NC) — Focused on thermoset anhydride‑free systems for dense flip‑chip encapsulation; their materials fit high‑reliability defense and aerospace adjacent markets.
-
Specialist formulators such as Epoxy Technology, Master Bond, and YINCAE combine niche capabilities — optical clarity, nano‑filling for thermal conductivity, and room‑temperature flow cures — to capture growth in photonics, MEMS, and image‑sensor segments.
Collectively, the top three firms account for a meaningful share of the market, with the top five widening that grip. This concentration creates a strategic opening for midsize players to differentiate via specialized chemistries, faster go‑to‑market cycles, or co‑development agreements with semiconductor foundries and OSATs.
Recent Industry Moves and Their Strategic Significance
-
Product launches of high‑thermal‑conductivity and optical‑clear underfills (2024–2025) signal supplier responses to rapid demand from silicon photonics, AR/VR, and hyperscale compute segments. These launches accelerate qualification cycles with OEMs and create short windows for design wins that have multiyear revenue tails.
-
Regulatory and trade interventions (anti‑dumping investigations, import restrictions) and raw material constraints (epichlorohydrin disruptions) have increased input price volatility and raised the cost of sourcing from certain geographies. The net effect: increased incentive for regional sourcing, qualification of alternative chemistries, and inventory buffering at critical nodes.
-
Incumbent formulators are broadening portfolios toward thermally conductive and optically clear grades. For buyers, this increases bargaining leverage on multi‑product contracts, but for innovators it shortens the window to authorize exclusive co‑developments.
Operational and Commercial Playbook for 2026
PW Consulting translates market intelligence into a pragmatic set of actions executives should consider this year. Our full study includes templates, costing models, and scenario simulations; below we summarize the high‑impact moves.
-
Risk‑Adjusted Sourcing: Implement a two‑tier procurement strategy — secure strategic volumes from validated global suppliers with financial and capacity assurances, while running a rotating qualification pipeline of regional formulators to mitigate localized trade or feedstock shocks.
-
Material Roadmapping with System Architects: Embed underfill selection into early system design conversations. We recommend cross‑functional scorecards that weigh thermal performance, stress characteristics, processing window, and reworkability. The payoff: reduced NPI iterations and faster time‑to‑market.
-
R&D Investment Focus: Prioritize chemistries that deliver thermal conductivity, optical clarity, and low‑stress cure profiles. Small bets in nano‑filled and room‑temperature flow systems can yield outsized returns when paired with access to early adopter OEMs in photonics and AR/VR.
-
M&A and JV Targets: Look for specialty formulators with proven niche performance and qualified supply to strategic customers. Our full report ranks acquisition targets by technical differentiation, customer overlap, and margin resiliency under commodity volatility.
-
Pricing and Contracting: Shift toward index‑linked longer‑term contracts with refractory caps on feedstock surcharges, combined with performance milestones that reflect qualification timelines and yield improvements.
Regulatory and Supply‑Chain Stress Test
Near‑term regulatory developments (RoHS‑driven reformulation pressure in the EU; multi‑jurisdiction trade enforcement on epoxy resins) and supply shocks have created a new normal of localized scarcity and price dislocation. PW’s scenario analysis models three realistic trajectories — contained disruption, protracted trade fragmentation, and accelerated regionalization — and quantifies their impact on margin profiles and supplier viability. Our recommendation: prioritize flexibility in supplier qualification and include tariff‑ and duty‑contingent clauses in procurement instruments.
What Our Full Underfill Market Study Delivers (Operationally Focused)
-
Validated market sizing and growth scenarios to 2032 with sensitivity tests for technology adoption rates and trade/disruption assumptions.
-
Supplier scorecards and a playbook for qualification workflows that shorten supplier approval time by up to 30% (per our pilot engagements).
-
Cost‑to‑serve and margin decomposition for typical underfill product families, including break‑even analysis for in‑house formulation versus contract sourcing.
-
Commercial templates: long‑form supply agreements, indexed pricing schedules, and NDA/R&D collaboration clauses tailored to underfill co‑development.
-
M&A screening matrix with prioritized targets and integration risk profiles (technical, regulatory, and customer concentration).
Strategic Questions for Boards and Executive Teams in 2026
-
Do we treat underfill as a commodity to be cost‑managed or as a strategic input that requires co‑design and joint IP with suppliers?
-
How exposed are we to input feedstock shocks and trade rulings — and what is our appetite for vertically integrating formulation capabilities?
-
Which application adjacencies (photonics, AR/VR, aerospace-grade electronics) offer the highest margin and defensibility for targeted product launches?
-
What timing on capacity expansions or licensing deals minimizes risk while capturing the projected growth curve through 2032?
Concluding Strategic Perspective
The underfill market in 2026 sits at the intersection of materials science and system‑level reliability engineering. Market growth—backed by a sustained mid‑to‑high single‑digit CAGR—creates tangible opportunity for differentiated suppliers and strategic buyers. Yet regulatory pressure, raw material volatility, and accelerating application diversification demand a disciplined strategy: secure qualified multi‑sourcing, invest in co‑development with end‑markets, and align commercial contracts to reflect supply‑side uncertainty.
PW Consulting’s full Underfill Market study provides the granular segmentation, regional and application breakouts, vendor benchmarking, and executable playbooks you need to convert market growth into sustainable advantage. This preview has intentionally focused on strategic levers and withheld the detailed segment tables and proprietary vendor scoring that underpin our recommendations — those are available in the comprehensive report and datasets accessible through our subscription portal.
Next Steps
-
Contact PW Consulting for an executive briefing and access to the full dataset, including scenario models, supplier scorecards, and implementation roadmaps tailored to your business goals.
-
Commission a tailored workshop with our underfill practice to translate these insights into a 90‑day action plan aligned to your product and sourcing roadmaps.
For detailed analysis of this topic, please visit the official page: Underfill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Household Dehumidifiers Market to Reach USD 181.0 Million by 2032 at 4.25% CAGR
By pmarketresearch, 2026-07-22
Household Dehumidifiers 2026: Strategic Implications from PW Consulting’s Market Outlook
As businesses prepare strategy for 2026, the household dehumidifiers market presents a measured growth opportunity underpinned by structural demand for indoor air quality, regulatory shifts on refrigerants, and steady product innovation. PW Consulting’s new market study — base year 2025, historical coverage 2020–2025 and a forecast horizon through 2032 — synthesizes these forces into a practical intelligence package. The global market expanded from roughly USD 110 million in 2020 to about USD 135.5 million in 2025 and is projected to grow at a 4.25% CAGR, reaching roughly USD 181.0 million by 2032. These headline figures frame a market that is neither hypergrowth nor stagnant: it rewards disciplined investment, operational excellence, and timely strategic adjustments.
Household Dehumidifiers Market
What this report delivers — practical takeaways, not just numbers
- Robust market-sizing and trend triangulation: granular annual vintage data (2020–2025) and a transparent forecasting methodology (2026–2032) that models demand, pricing, and technology adoption scenarios.
- Commercially actionable segment analysis: buyer personas, channel economics, pricing bands, and SKU-level margin benchmarks that translate into product and route-to-market decisions (note: we deliberately withhold proprietary split tables in this preview).
- Technology and cost curves: refrigerant transition impact assessments, energy-efficiency trajectories, and comparative lifecycle cost models to support product roadmap and CapEx decisions.
- Regulatory and trade impact playbook: compliance requirements, certification pathways, and duty exposure mapping to inform sourcing, localization, and product design choices.
- Competitive positioning and M&A lens: capability maps for incumbents and challengers, entry-barrier assessment, and criteria for bolt-on acquisitions or strategic alliances.
- Commercial execution templates: prioritized 90/180/360-day action plans for product launches, channel pilots, after-sales programs, and corporate sustainability disclosures.
Market dynamics shaping 2026 decisions
- Steady demand driven by indoor air quality (IAQ) awareness: extreme weather events and associated mold risk have moved dehumidifiers from a seasonal appliance into a year-round IAQ consideration for many households. This trend supports upgrades to smarter, more energy-efficient models and recurring revenue opportunities through services and consumables.
- Regulatory inflection points: recent rules — including HFC phase-downs and bans on high-GWP refrigerants effective since 2025 in several major jurisdictions — materially affect product architecture and supply chains. Manufacturers must plan refrigerant transition and certification timelines now to avoid market access disruptions.
- Trade and tariff noise: tariff revisions focusing on lower-capacity units introduce margin and sourcing complexity for manufacturers and importers. Companies should evaluate product mix adjustments and near-shore manufacturing options to mitigate duty exposure.
- Energy efficiency and lifecycle emissions: product launches in 2025–2026 emphasize lower energy consumption and lifecycle CO2 reductions, making energy performance a differentiator for both retail buyers and regulatory compliance.
- Moderate market concentration: the market exhibits a moderate degree of concentration (CR3/CR5 ~55%), which favors scale players for cost leadership, but still leaves room for focused innovators and regional champions to capture profitable niches.
Competitive landscape — who sets the pace
The competitive set combines global appliance conglomerates, regional specialists, and appliance brands with smart-home ambitions. Key strategic postures observed in the market include:
Household Dehumidifiers Market
- Midea Group — leverages scale and a portfolio approach: strong in portable, ENERGY STAR–certified smart units and variants with integrated pumps; scale advantages support aggressive distribution and OEM relationships.
- Resideo Technologies — positions around whole-home solutions and serviceability: the recent Honeywell Home whole-home launch emphasizes flexible installation and lifecycle serviceability, a clear bid to reduce total cost of ownership for institutional and premium-residential buyers.
- LG Electronics — competes on smart, inverter-driven efficiency: AI-enabled operation and inverter compressors appeal to buyers prioritizing low energy bills and integrated smart-home workflows.
- Frigidaire (Electrolux), GE Appliances (Haier), Whirlpool — incumbents focusing on recognizable consumer brands, broad retail channels and incremental smart features to maintain share in mainstream segments.
- Danby, De’Longhi, TCL — niche or regionally strong players: compact-format and value propositions for urban and European buyers; smart portable offerings for mass channels.
- Honeywell International — a cross-segment player emphasizing IAQ credentials, combining whole-home and residential approaches.
Recent product developments underscore the competitive focus on efficiency and serviceability. Resideo’s 2025 Honeywell Home whole-home refresh prioritizes installation flexibility and service life extension; Munters’ 2026 MX3 series claims significant energy and CO2 reductions. These moves signal that 2026 product programs should prioritize measurable energy gains, ease of service, and refrigerant compliance to stay competitive.
Household Dehumidifiers Market
Strategic imperatives for 2026
- Embed refrigerant and regulatory readiness into product roadmaps now. With phasedowns and bans already effective in core markets, firms must validate refrigerant paths, update compliance documentation and re-qualify supply lines to avoid time-to-market penalties.
- Differentiate on operational cost, not only CAPEX. Energy efficiency, reduced leakage, inverter technology and smart control algorithms deliver quantifiable lifetime cost advantages — critical to win trade and informed consumers.
- Design for serviceability and circularity. Products engineered for easy maintenance, modular replacement parts, and take-back programs improve customer lifetime value and satisfy evolving ESG requirements.
- Re-evaluate go-to-market segmentation. Early movers should pilot service/subscription offers (filters, maintenance), smart-enabled warranties, and targeted channel partnerships with HVAC integrators and IAQ specialists.
- Optimize footprint against tariff risk. Use scenario planning to decide between local assembly, hybrid sourcing, or tariff engineering for lower-capacity SKUs that face duty exposure under recent tariff rule changes.
- Maintain an opportunistic M&A posture. With moderate concentration and fragmented niches, targeted acquisitions (technology, regional distribution, or service networks) can accelerate time-to-market for differentiated offerings.
Immediate actions — a pragmatic 90/180/360 roadmap
- 0–90 days: Complete a refrigerant-compliance gap analysis across the product portfolio; prioritize SKUs vulnerable to duty changes; pilot energy-improvement features for the top-selling models.
- 90–180 days: Launch a serviceability audit and parts-sourcing strategy; begin partner trials for subscription maintenance; initiate certification and ENERGY STAR submission where applicable.
- 180–360 days: Scale production adjustments (near-shoring or local assembly where economic), roll out a targeted smart-model launch in at least one key market, and evaluate one or two bolt-on acquisitions focused on smart controls or service capability.
Conclusion — why this matters for your 2026 planning
The household dehumidifiers market presents a disciplined growth profile: meaningful, measurable expansion rather than runaway scale. That combination makes it ideal for companies that can align product engineering, regulatory compliance, and channel execution. Our analysis shows the market moved from approximately USD 110 million in 2020 to roughly USD 135.5 million in 2025 and is expected to grow at a 4.25% CAGR to around USD 181.0 million by 2032 — a trajectory that rewards near-term investments in energy-efficiency, refrigerant transition, and service-led revenue models. With a moderate concentration among top players, 2026 is a pivotal year to solidify competitive positioning: the costs of inaction on regulatory readiness and energy performance are immediate; the rewards for focused execution are sustainable market share and margin improvement.
PW Consulting’s full report contains the detailed segment matrices, channel economics, SKU-level pricing bands, and executable templates that boards and product leaders need to make confident investments in 2026. For decision-makers seeking to convert these insights into measurable actions, our study provides the evidence base and playbook to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Household Dehumidifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Histidine Market to Reach USD 338.85 Million by 2032 — PW Consulting Insight
By pmarketresearch, 2026-07-22
Histidine Market: Strategic Imperatives for 2026 Decision-Makers
As the histidine market enters a new phase of commercially relevant expansion, decision-makers must calibrate strategy against an evolving demand base, concentrated supplier footprints, and shifting trade dynamics. Our latest PW Consulting market study — grounded on a 2025 base year, with a historical window from 2020–2025 and a forecast through 2026–2032 — projects a robust compound annual growth rate (CAGR) of 6.8%. The global market, estimated at approximately USD 215.0 Million (revenue unit: Million) in 2025, is set to climb materially by 2032 under current trends. This briefing highlights the report’s practical value for 2026 planning while intentionally preserving the proprietary segmentation and pricing matrices behind our full release.
Histidine Market
Why histidine matters to 2026 strategy
Histidine is no longer a niche amino acid confined to legacy feed and food use cases. Acceleration in cell-culture therapies, parenteral nutrition formulations, and higher-value biopharma applications has expanded both the purchasing stakes and the quality bar. For corporate leadership, three strategic realities stand out:
Histidine Market
- Growing, but selective demand: Market volumes and revenues are increasing predictably (2025 baseline USD 215.0 Million; forecast shows a clear uptrend to the 2032 horizon), yet growth pockets are uneven and quality-sensitive — privileging suppliers that can meet GMP, low-endotoxin and low-metal specifications.
- Supplier concentration and capability-driven sourcing: Industry concentration metrics indicate that the market is meaningfully clustered among a handful of specialized producers. That concentration elevates supplier risk and makes differentiated capability (fermentation-derived high-purity grades, GMP supply chains) a decisive commercial lever.
- Trade and regulatory volatility: Recent policy moves affecting chemical intermediates and exports have real near-term implications for raw material access, costs and contract security — factors that must be embedded into 2026 sourcing and investment choices.
Key macro signals embedded in our analysis
- Base year clarity: the study uses 2025 as the analytical anchor to ensure all forward-looking scenarios reflect the most recent commercial and regulatory environment.
- Historical trend closure: the 2020–2025 historical series grounds our adoption curves, enabling robust attribution of cyclic vs secular drivers behind demand.
- Forward visibility: the 2026–2032 forecast is built on a 6.8% CAGR and scenario-based adjustments; the headline projection shows substantial upside for firms that secure high-purity channels and commercialized product differentiation.
- Concentration context: market concentration indicators are incorporated to quantify counterparty exposure and to shape diversification strategies.
What the full report delivers (practical, transaction-ready outputs)
- Market sizing and modeled forecasts tailored to multiple adoption scenarios — baseline, upside (accelerated biopharma adoption), and downside (regulatory friction).
- Demand-driver decomposition that isolates biopharma-grade adoption, feed/food steady-state demand, and the contribution profile of emerging applications.
- Supplier capability mapping and comparative scorecards (quality, capacity, regulatory readiness, geographic exposure) to support vendor selection and contingency planning.
- Technology and route economics comparing fermentation and hydrolysis production pathways, including capex/opex profiles, scalability constraints and margin sensitivity.
- Pricing intelligence and channel dynamics — transactional benchmarks, observed premium bands for GMP/high-purity grades, and seasonality patterns (note: detailed price curves and unit-level tables are reserved for the full report).
- Regulatory and trade scenario playbooks, with impact matrices tied to likely policy moves in production hubs and export regimes.
- Commercial growth playbooks: channel strategies, partnership archetypes, and contracting templates for multi-year supply security.
- Investment and M&A assessment framework — valuation ranges, break-even timelines and operational triggers for greenfield vs brownfield investments.
- Actionable procurement tools: supplier diversification scorecards, risk heatmaps, and contract clause recommendations for quality and continuity.
Competitive landscape — what to watch
The competitive set is composed of established specialty chemical and life-science suppliers, fermentation-focused incumbents, and regional producers focused on commodity grades. Representative firms covered in the study include Ajinomoto, Kyowa Hakko Bio, Evonik, Merck KGaA, Pfanstiehl, Daesang and Changzhou Highassay — each with distinct positioning:
Histidine Market
- Firms with fermentation-optimized platforms emphasize high-purity GMP grades tailored for cell culture media and parenteral uses; these suppliers are increasingly sought for secure supply of high-value applications.
- Legacy chemical suppliers and regional producers offer cost-competitive volumes for feed and standard food applications, but face pressure to meet the higher regulatory and quality bar demanded by biopharma customers.
- Niche players and contract manufacturers (including toll-providers) are emerging as tactical partners for firms seeking flexibility without committing to capex-heavy expansions.
Strategic partnerships and alliances are already reshaping the supply landscape. A notable example included in our dataset is a March 2025 strategic collaboration where a major fermentation-based producer moved to co-develop and secure additional global supply. This type of alliance signals a broader trend: firms are layering partnerships to mitigate raw-material exposure and to accelerate access to GMP-capable supply chains.
Regulatory and trade developments with immediate relevance to 2026
Policy shifts affecting chemical intermediates and export controls have the potential to alter the sourcing calculus for buyers and producers alike. Recent public records indicate temporary adjustments to export control posture on certain dual-use intermediates; these changes can reduce friction in the short term but introduce uncertainty as timelines, end-user verification and enforcement frameworks remain fluid. Procurement teams must therefore adopt conditional contracting that balances near-term opportunity capture with clauses for continuity and force majeure protections.
Strategic recommendations for 2026
Based on the intersections of demand trajectory, supplier concentration and policy ambiguity, PW Consulting recommends that companies structure a phased, risk-weighted response in 2026:
- Secure multi-tiered supply: Adopt a multi-source strategy that combines a primary GMP-certified supplier for critical applications with secondary regional or contract manufacturers for non-critical volumes. Embed escalation and audit rights in contracts.
- Prioritize capability over lowest-cost: For cell-culture and parenteral products, prioritize suppliers with proven low-endotoxin, low-metal capabilities and documented GMP traceability even at a premium — the cost of failure in these segments exceeds short-term savings.
- Accelerate partnership options: Evaluate strategic partnerships, toll-manufacturing agreements, or minority investments in fermentation capacity. These options balance speed-to-market and control without immediate full-scale capex.
- Operationalize regulatory monitoring: Set up a cross-functional early-warning system to track trade and export policy shifts in key producing jurisdictions and translate alerts into procurement triggers.
- Embed contingency financial planning: Incorporate volatility buffers into 2026 budgets — both for raw material price variation and for potential costs from quality remediation or supplier substitution.
Near-term timeline — recommended 2026 milestones
- Q1 2026: Complete supplier capability audits for all high-priority SKUs; lock short-term supply with contingency clauses.
- Q2 2026: Finalize one or more partnership/toll agreements to secure scalable fermentation capacity for high-purity grades.
- Q3 2026: Implement a live regulatory-tracking dashboard and test contractual escalation protocols via tabletop simulations.
- Q4 2026: Review and adjust sourcing strategy against observed price and supply outcomes; consider strategic investments if demand acceleration persists.
Where this briefing intentionally leaves questions
To preserve the strategic value of the full PW Consulting deliverable, this introduction intentionally omits granular segmentation tables, unit-price curves, and the proprietary supplier-scorecard datasets that underpin negotiations and valuation models. These elements are available in the full report and are provided in machine-readable form to support procurement, commercial and M&A diligence.
Next steps
For leadership teams preparing 2026 budgets and strategic plans, the full PW Consulting Histidine Market Report supplies the transactional-level detail necessary to execute on the recommendations above: contract-ready supplier templates, detailed price and volume scenarios, and supplier-specific risk assessments. Contact PW Consulting to access the full dataset, tailored supplier scorecards, and our scenario-modelling toolkit to convert this market trajectory into defensible procurement and investment decisions.
For detailed analysis of this topic, please visit the official page: Histidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Labels Market to Expand at 5.37% CAGR Through 2032
By pmarketresearch, 2026-07-22
Automotive Labels Market — Strategic Outlook for 2026 Decision‑Making
As OEMs, Tier‑1 suppliers and material innovators prepare procurement and product roadmaps for 2026, the automotive labels market is no longer a commodity conversation. It is a strategic lever across vehicle safety, regulatory compliance, after‑sales traceability and sustainability. PW Consulting’s latest market study (base year 2025; forecast 2026–2032) synthesizes primary interviews, vendor benchmarking and scenario‑based forecasts to convert label specification choices into measurable business outcomes. The global market reached USD 8.67 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.37% to about USD 12.5 million by 2032 — growth driven by electrification, regulatory tightening and the industry’s sustainability pivot.
Automotive Labels Market
Why 2026 is an Inflection Point
-
Electrification and new vehicle architectures are changing where and how labels must perform. Battery pack identification, EV‑specific safety markings and lightweight interior materials increase technical complexity for adhesives, face stocks and constructions.
Automotive Labels Market -
Regulatory scrutiny — from quality standards such as IATF 16949 to emissions/engine labelling requirements in major jurisdictions — is raising the bar for supplier qualification and in‑service validation.
Automotive Labels Market -
Sustainability requirements are shifting procurement priorities toward circular and recyclable solutions. New product introductions by adhesive and label manufacturers demonstrate that the technology to meet circularity is rapidly maturing.
-
Supply chain resilience matters more: the market shows meaningful concentration among a few large suppliers, which creates tradeoffs between scale advantages and single‑source dependency.
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
-
Strategic market forecast (2026–2032) contextualized by technology, regulation and vehicle architecture scenarios — enabling procurement and product teams to stress‑test decisions across realistic market trajectories.
-
Supplier landscape and competitive scorecards: qualitative and quantitative vendor profiles, manufacturing footprints, compliance certifications and capability maps to shorten shortlist cycles.
-
Materials and construction matrix: decision trees that map adhesive chemistries and face stocks to application zones (interior, exterior, underhood, powertrain, battery) and service life expectations.
-
Cost and value models: total cost of ownership frameworks that incorporate unit costs, qualification lead times, warranty exposure and end‑of‑life recovery potential.
-
Regulatory and certification playbook: compliance checklists (IATF 16949 and other jurisdictional requirements), test protocols, and templates for supplier qualification and OEM audits.
-
Deal‑ready tools: RFP templates, sample test plans, risk heat maps and an M&A screening approach tailored to vendors in this market segment.
Competitive Dynamics — Who Matters and Why
The market structure favors suppliers that combine technical R&D with global OEM relationships and validated manufacturing processes. PW Consulting’s research highlights a cluster of established players that routinely surface in OEM-qualified supplier lists — firms that offer end‑to‑end solutions from adhesive formulation to certified label constructions. These companies bring complementary strengths to the market:
-
3M Company — broad portfolio of durable polyolefin and polyester constructions with proven chemical resistance and established OEM compliance pathways.
-
Avery Dennison Corporation — tested solutions across underhood, interior and EV battery applications; recent product introductions and published durability validations reflect a strong product‑development cadence.
-
Brady Corporation — industrially hardened labeling solutions designed for harsh environments and OEM vehicle applications.
-
UPM Adhesive Materials — repositioned with a portfolio that explicitly targets circularity and recyclable constructions, including new adhesive platforms aimed at reuse and material recovery.
-
CCL Industries Inc. — pressure‑sensitive label specialist with proven constructions for durable and compliant automotive markings.
-
Resource Label Group — local, UL‑recognized solutions and rapid customization capabilities for North American OEMs and parts suppliers.
-
Whitlam Group, UP‑Labels GmbH, Adhesive Research and H.B. Fuller — each contributes niche strengths from custom engineering and specialized adhesive chemistries to tire identification and IATF‑aligned manufacturing.
These vendors are active: recent product launches, rebranding efforts and third‑party validation campaigns indicate accelerated competition around durability, lightweight constructions and circular adhesives. For example, a leading materials supplier introduced special constructions and published independent testing in 2025; another rebranded and presented a Carbon Action label portfolio aimed at circular automotive applications the same year. PW Consulting’s supplier scorecards capture these dynamics and evaluate vendors not only on product specifications but on validation discipline, OEM acceptance rates and supply‑chain agility.
Regulation, Materials and the Sustainability Imperative
Labeling in vehicles is tightly bound to regulatory compliance and safety protocols. IATF 16949 remains a gating criterion for many OEM supplier approvals; heavy‑duty engine and emission labelling continue to reference established jurisdictional requirements. Separately, the industry’s move toward circularity is enabling new supplier value propositions: adhesive systems engineered for recyclability and label constructions designed to facilitate material reclamation are emerging as differentiators. PW Consulting’s analysis quantifies the commercial impact of these trends and provides a pathway for procurement teams to incorporate circularity performance into supplier scorecards without destabilizing qualification timelines.
Actionable Recommendations for 2026 Planning
-
Prioritize dual‑sourcing for critical application zones. Where labels interface with safety systems or battery packs, dual validated suppliers reduce program risk without materially increasing lifecycle cost.
-
Increase early‑stage testing against real‑world stress profiles. Invest in accelerated aging and underhood exposure tests during the prototyping phase to avoid late design changes.
-
Embed circularity metrics in supplier panels. Require adhesive recoverability and recyclability performance as part of RFQ evaluation criteria for any mid‑to‑long‑life programs.
-
Align procurement slots with certification cycles. Use supplier scorecards to map lead times for IATF‑aligned audits and validation runs so that label qualification aligns with vehicle program milestones.
-
Use the report’s TCO models to compare standard constructions against premium circular and high‑durability options on a lifecycle basis rather than unit price alone.
Risk Scenarios and What to Monitor
PW Consulting models three plausible scenarios through 2032 — a conservative baseline, a technology‑led adoption curve and an accelerated sustainability mandate — each with implications for material choice, supplier concentration and pricing. Key risk vectors for 2026 include raw material cost volatility, certification bottlenecks and geopolitical exposure in adhesive supply chains. Mitigation tactics include strategic inventory policies for critical face stocks, qualification of regional alternate suppliers and contractual language that preserves IP while enabling co‑engineering for circular products.
How to Use This Study in Your 2026 Planning Cycle
For CPOs, head engineers and corporate sustainability leads, the report is a toolkit: it translates market forecasts into procurement actions, technical specifications into qualification roadmaps and vendor intelligence into shortlist decisions. The study’s forecast frames capital and operating decisions, while the supplier scorecards and RFP templates accelerate execution. To protect proprietary commercial models and to preserve competitive advantage for readers, the report provides detailed segmentation tables, regional and application splits and full vendor benchmarking only within the delivered dataset and client portal.
Next Steps
-
Download the executive brief or request the full dataset to access tables, regional and application splits, and downloadable supplier scorecards.
-
Commission a PW Consulting workshop to translate the report’s scenarios into a labeled supply‑chain stress test tailored to your vehicle programs.
-
Engage our advisory team for vendor due diligence and M&A screening if you are evaluating strategic acquisitions or joint development agreements in the label and adhesive space.
PW Consulting’s Automotive Labels Market study is designed to convert a small but critical component category into a strategic advantage for 2026. By combining market‑level forecasts (5.37% CAGR to 2032), concentration analysis, supplier benchmarking and actionable procurement tools, the research equips executives to make risk‑adjusted, future‑proof decisions now — while preserving access to the granular data and supplier intelligence that will be decisive in the next vehicle development cycle.
For detailed analysis of this topic, please visit the official page: Automotive Labels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stationery Market 2026 Strategic Brief — Tactical Intelligence for C-suite Decisions
Executive overview
As companies plan budgets and strategic moves for 2026, the stationery sector presents a paradox: structurally resilient demand alongside shifting cost & channel dynamics that will disproportionately reward nimble players. Our PW Consulting Stationery Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) synthesizes macro sizing, competitive positioning, supply-chain levers and actionable go-to-market plays that senior leaders need to convert modest market growth into outsized margins.
Stationery Market
Key headline: the global stationery market expanded from roughly USD 110.8 Million in 2020 to USD 165.9 Million in 2025 and is projected to continue growing through 2032 — reaching a market value in the order of USD 230.2 Million by 2032 — at a compound annual growth rate of approximately 4.85% across the forecast window. This trajectory underpins steady demand while leaving plenty of room for share shifts and margin improvement initiatives.
Stationery Market
Why this report matters for 2026 decisions
- Budget prioritization: With steady topline growth but rising input-cost volatility, firms must decide whether to invest in premiumization, scale, or supply-chain resilience. Our study quantifies trade-offs and models the ROI of each path under three macro scenarios.
- M&A and partnership triage: Market concentration is moderate (CR3 ≈ 25%; CR5 ≈ 42%), indicating a mix of global leaders and many regional players. That makes 2026 a window for bolt-on acquisitions to capture distribution and digital capabilities. We provide an M&A scorecard and rapid-screen targets to accelerate deal pipelines.
- Sustainability as a strategic lever: Leading firms are converting sustainability into premium positioning and procurement wins. We map which ESG investments materially improve margin and which are marketing-only expense.
- Channel reallocation: The interplay between institutional (education, corporate) procurement and retail/e-commerce is shifting. The report offers tactical playbooks for channel-specific assortment, pricing and promotion design for the year ahead.
Market dynamics shaping 2026
The sector’s steady CAGR masks several important structural forces that will determine winners and laggards in 2026:
Stationery Market
- Cost and tariff pressure: New tariff policies implemented in 2025 raised effective import rates for many input-reliant sectors. In some markets, import cargo volumes are forecast to decline, compressing supply options and increasing landed costs for firms dependent on cross-border sourcing.
- Supply-chain realignment: Firms are re-evaluating offshore concentration and nearshoring trade-offs — balancing unit cost vs. inventory flexibility and lead times. Our Supplier Risk Index shows where simple supplier shifts yield the largest resilience gains without eroding gross margin.
- Demand heterogeneity: While aggregate demand is expanding, the mix—between education, corporate procurement and residential channels—varies by market. We deliberately withhold granular segment tables here; the full report contains a detailed segmentation matrix and elasticity curves for each channel (access instructions at the end).
- Sustainability and brand campaigns: Industry leaders are proactively converting ESG investments into demand drivers. Recent public developments—such as a major manufacturer releasing a 2025 sustainability report and launching targeted school-supply initiatives in 2026—signal the way incumbents are using purpose-led campaigns to defend institutional share.
Competitive landscape: patterns, positioning and moves
The stationery competitive set spans global mass brands, premium luxury producers, and regionally dominant manufacturers. Understanding each cluster’s strategic intent is critical for crafting countermoves:
- Global mass-market leaders (scale and distribution): Legacy brands with extensive manufacturing and retail footprints continue to leverage scale and category control to defend volume. Their priorities are SKU rationalization, cost-to-serve reduction and digital shelf optimization. Examples include established international producers headquartered in Europe, Japan and the US.
- Premium and specialty players (brand and margins): Premium heritage manufacturers focus on product quality, collectible positioning and licensing tie-ins. Their opportunities lie in limited editions, corporate gifting and premium stationery subscriptions for affluent consumer segments.
- Regional challengers and low-cost manufacturers: Several Asia-based manufacturers combine local market knowledge with low-cost production to win institutional contracts and grow exports. These firms are increasingly investing in R&D and packaging to move up the value chain.
- Consolidation dynamics: The market’s moderate concentration means meaningful room for consolidation—particularly around distribution, private label manufacturing and digital capabilities. Our competitive heatmap ranks players on scale, margin profile, channel reach and ESG maturity.
Selected company briefs (indicative, not exhaustive):
- BIC (Clichy, France) — global leader in mass-market writing and school supplies; recent activity includes a 2025 sustainability report and a national school-supply campaign launched in 2026 that targets institutional displacement through purpose-driven marketing.
- Faber-Castell and Staedtler (Germany) — premium/heritage producers with strong positioning in creative and professional stationery; focus on product innovation and artist partnerships.
- Pilot, Pentel, Zebra, Mitsubishi Pencil (Japan) — leaders in writing instruments with technological differentiation and long-standing channel relationships.
- Major Asia players (e.g., Kokuyo Camlin, M&G Stationery, Deli Group, Beifa Group) — cost-competitive, rapidly scaling exporters with growing R&D investments.
- Newell Brands and A.T. Cross (US) — broad office-supplies portfolios and premium specialty lines; emphasis on corporate procurement and branded enterprise programs.
Strategic playbook for 2026 (practical actions)
For executives deciding allocations in 2026, the report prioritizes a small set of high-impact moves that can be executed within 6–12 months:
- Re-index sourcing by total landed cost (not unit price): Implement a landed-cost model that captures tariffs, inventory carrying, and service-level impacts to identify nearshore candidates and targeted dual-sourcing for critical SKUs.
- SKU rationalization plus assort-to-channel: Reduce low-velocity SKUs while launching channel-specific assortments—premium bundles for retail, economy packs for institutional buyers, and curated sets for e-commerce.
- Operational hedges against tariff volatility: Increase safety-stock selectively for long-lead materials, negotiate tariff-sharing clauses with suppliers, and explore bonded-warehouse solutions for the largest procurement accounts.
- Monetize sustainability investments: Link eco-credentials to procurement wins via verified claims and lifecycle disclosures; pilot recycled-ink or pulp offerings with willing institutional partners.
- Accelerate digital shelf and D2C experiments: Use dynamic pricing, subscription bundles, and limited-edition drops to test elasticity; measure CAC payback across channels to inform 2027 budgets.
- Targeted M&A sprint: Use our 3-tier M&A scorecard to prioritize bolt-ons that deliver distribution access, private-label capacity or proprietary IP in under 12 months.
What the full PW Consulting report contains (practical deliverables)
Designed as an operational toolkit for 2026, the full report moves beyond narrative to include executable assets:
- Market sizing and 2026–2032 forecast models (downloadable Excel) with sensitivity runs under three macro scenarios.
- Segment-level demand elasticities and channel margins (educational, corporate, residential) — note: detailed segment tables are available exclusively in the report.
- Competitive heatmaps and an M&A target shortlist with acquisition rationale.
- Supplier Risk Index, landed-cost calculators and a procurement negotiation playbook.
- Go-to-market playbooks for retail, institutional and e-commerce channels with sample P&L impact simulations.
- Five executable case studies and a 90/180-day implementation checklist for rapid deployment.
Risk matrix and scenario planning
We model three principal 2026 scenarios — Baseline (moderate growth and stable tariffs), Tariff Shock (higher import costs and constrained logistics), and Demand Shock (slower institutional purchases). Each scenario highlights different priority levers: pricing and hedging in Tariff Shock; customer retention and channel mix in Demand Shock; and strategic investment and M&A in Baseline. The report provides probability-weighted expected value outcomes to inform capital allocation and contingency planning.
How to use this brief
This article is a strategic trailer — intended to surface the report’s practical value and to help leadership teams align around the key choices for 2026. We deliberately show high-level sizing and competitive patterns while withholding the granular segment and regional breakdowns that procurement and product teams require to execute tactical moves. Those datasets and the toolkits described above are included exclusively in the full Stationery Market report.
Next steps
- If you are preparing a 2026 plan or an acquisition shortlist: request the full dataset and M&A scorecard to run your scenarios on company-specific metrics.
- If you lead procurement or supply chain: obtain the Supplier Risk Index and landed-cost model to stress-test current sourcing strategies against tariff scenarios.
- If you are developing commercial strategy: use the channel playbooks and digital-shelf experiments to reallocate marketing spend for 2026.
For access to the full Stationery Market report — including the complete segment-level matrices, downloadable models and playbooks referenced above — please visit our report landing page or contact PW Consulting’s research team. The detailed intelligence contained there is designed to convert the market’s steady growth into 2026 decisions that create defensible advantage.
For detailed analysis of this topic, please visit the official page: Stationery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rail Market to Reach USD 300.51B by 2032 at 6.47% CAGR (2026–2032)
By pmarketresearch, 2026-07-22
Rail Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
Executive preview
By 2026, rail will no longer be a legacy transport sector that simply maintains lines and schedules. Our Rail Market study — built on a 2020–2025 historical base and projecting through 2032 — demonstrates that the industry has entered a multi-year growth phase driven by fleet renewal, signalling modernisation, electrification programmes and freight capacity upgrades. The global market expanded from approximately USD 142.5 Billion in 2020 to about USD 193.8 Billion in 2025 and, under our central-case assumptions, is projected to approach USD 300.5 Billion by 2032, representing a compound annual growth rate of roughly 6.47% across the forecast horizon. For boards, strategy teams and investors preparing 2026 plans, these macro trajectories change the calculus on capital allocation, partnerships and technology investment.
Rail Market
Why this matters for 2026 decision-making
-
Investment timing: With a sustained mid-single-digit CAGR baked into our baseline, the optimum window to commit to expansion or to retrofit fleets is now. Delaying multi-year projects risks missing a period of cost-efficient equipment delivery and favourable financing conditions that are likely to prevail in the early-to-mid forecast window.
Rail Market -
Risk-adjusted returns: The market’s scale supports larger strategic plays — consolidation, vertical integration and technology acquisition — but the market concentration metrics we model require disciplined selection. The top-tier players together account for a material share of supply, creating both barriers and partnership opportunities for new entrants.
Rail Market -
Operational transformation: Digital signalling, automated operation technologies and asset analytics are migrating from pilot projects to commercial rollouts. Systems-level upgrades create service-level differentiation and new revenue lines for suppliers and operators prepared to adopt them.
What the market snapshot tells us (high level)
Our modelling combines a granular market-sizing exercise with scenario stress tests. The base-year analysis (2025) captures the revenue pool approaching USD 194 Billion and reconciles manufacturers’ shipments, systems integrators’ contracts and maintenance/service flows. From this base we apply demand drivers and constraint overlays to produce a 2026–2032 outlook that reaches roughly USD 300.5 Billion in our central case. Alongside growth, the market exhibits moderate concentration: the three largest suppliers control just over half of industry revenues, and the top five capture close to six in ten dollars of the market — a structure that sustains healthy competition while enabling scale advantages for incumbents.
Key growth vectors and strategic implications
-
Fleet renewal and capacity expansion: Many operators face ageing rolling stock and constrained freight corridors. The replenishment cycle is creating sustained demand for rolling stock and associated systems. For suppliers, winning specification slots hinges on performance guarantees, lifecycle cost modelling and local-service commitments.
-
Signalling and automation: Next-generation track circuits and automated traction systems are reaching regulatory acceptance in multiple jurisdictions. Early movers that combine signalling hardware with proven software stacks and services contracts will capture premium margins as operators aim to raise throughput and safety simultaneously.
-
Electrification and power supply: Electrification programmes, paired with grid modernisation, are a multi-year deployment opportunity. Companies that can bundle civil, electrical and systems integration services will be advantaged versus point-solution vendors.
-
Maintenance-as-a-Service (MaaS): The shift from CAPEX to outcomes-based procurement is accelerating. Operators increasingly prefer long-term, risk-sharing maintenance arrangements that require suppliers to demonstrate predictive maintenance capabilities and proven asset performance analytics.
Competitive landscape — who matters and why
The market is anchored by industrial-scale manufacturers, specialist systems providers and vertically integrated suppliers. Our coverage spotlights firms that combine manufacturing scale with systems integration capabilities and well-developed after-sales networks. Four illustrative players from our competitive analysis:
-
voestalpine Railway Systems Nortrak — a specialist in special trackwork and turnout systems with targeted asset expansion moves in North America. Recent asset acquisitions indicate an explicit strategy to increase capacity for complex track components and shorten lead times for large transit and Class I customers.
-
Pandrol — a long-established leader in fastening systems and resilient track infrastructure. Their global deployment experience and deep product portfolio position them well to capitalise on large retrofitting and high-availability projects.
-
Vossloh AG — a full-spectrum supplier of turnouts, sleepers and maintenance solutions with a clear focus on freight, high-speed and urban markets. Vossloh’s mix of product breadth and maintenance services enables comprehensive lifecycle offers that many customers now demand.
-
Steel Dynamics Inc. — a regional rails manufacturer notable for its capacity to produce long, hot-rolled rails with high dimensional consistency. In markets where long welded rail and durability are differentiators, such manufacturing capabilities matter strategically.
Recent industry developments reinforce these dynamics. Strategic factory openings and product launches by major OEMs are expanding regional manufacturing footprints and introducing AI-enabled capabilities in rolling stock. M&A activity and asset acquisitions have been used to shore up supply chains and capacity ahead of expected tender waves.
Operational and regulatory dynamics to factor into plans
-
Supply chain and raw materials: Steel and rail-specific inputs remain key variables. Manufacturers with vertical integration or secured long-term supply agreements will experience fewer schedule disruptions and can offer more competitive guarantees.
-
Labour and delivery cadence: Large industry gatherings and cross-border supplier engagement remain critical for deal origination and skills transfer — events in 2026 will shape procurement calendars and hiring cycles for the remainder of the decade.
-
Regulation and safety standards: Regulatory shifts toward advanced track circuitry and broken-rail detection influence procurement specifications. Suppliers that can demonstrate compliance and field-proven performance will have a distinct advantage in public tenders.
What our report delivers — practical, transaction-ready outputs
PW Consulting’s Rail Market study is designed for executives who need actionable intelligence rather than theory. The report package includes:
-
A financial market model with historical reconciliation (2020–2025) and scenario-linked forecasts (2026–2032) that allow you to stress-test revenue, margin and capital outcomes against price, volume and policy shocks.
-
Supplier benchmarking and a concentration map that identifies capability gaps, partnership opportunities and M&A targets by technology stack and service model.
-
Procurement and localisation playbooks for rolling stock and track systems — including contracting structures, warranty models and performance KPI templates designed to reduce lifecycle cost.
-
Operational playbooks for signalling upgrades, electrification rollouts and maintenance outsourcing, with implementation roadmaps and suggested governance frameworks for 24–36 month programmes.
-
Deal origination lists and a watchlist of near-term tenders and capex programmes curated to support corporate development and private equity screening activities.
Importantly, the report intentionally omits no critical datapoint — every segment and regional split, down to component-level volumes and pricing assumptions, is present in the full dataset and model. The summary here deliberately refrains from reproducing those granular figures so you see the strategic logic without exposing the proprietary granularity we reserve for authorised subscribers.
How to use this study in your 2026 planning cycle
-
Board-level capital allocation: Use the scenario model to test where to accelerate capex (e.g., factories, localisation) versus where to prioritise OPEX optimisation.
-
M&A and JV screening: Apply our supplier benchmarking to identify targets that provide capability adjacency or immediate access to service contracts.
-
Procurement strategy: Adopt the playbook to convert one-off procurements into outcomes-based contracts that align incentives across operators and vendors.
-
Technology adoption: Use the signalling and automation readiness modules to sequence pilot-to-scale rollouts and to size investment needs for safety certification and workforce retraining.
Methodology and confidence
The study integrates bottom-up shipper and OEM activity data, public tender pipelines, maintenance contract disclosures and PW Consulting primary interviews. Historical data spans 2020–2025; the base year is 2025, and the forecast window covers 2026–2032. We apply probabilistic scenario analysis to produce a central-case CAGR of approximately 6.47% and stress-case ranges for downside and upside contingencies. Market concentration metrics are derived from reconciled revenue pools and public financials, offering a robust view of industry structure for M&A and partnership decisions.
Final perspective and next step
The macro numbers tell a clear story: the rail sector’s addressable pool will expand materially over the coming decade, creating openings for capacity investors, systems integrators, digital-solution providers and operators that reconfigure procurement for lifecycle outcomes. Yet the devil is in the detail — winning in 2026 requires granular intelligence on segment demand curves, tender timing, specification language and supplier delivery profiles.
PW Consulting’s full Rail Market report supplies that intelligence. This executive preview highlights the strategic takeaways; the complete dataset, segment revenue splits, and contract-level analysis are available through the report portal for subscribers and authorised clients. If your 2026 strategy depends on precise timing, supplier selection or a defensible M&A thesis, the full study is the operational toolkit you’ll rely on.
For detailed analysis of this topic, please visit the official page: Rail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plasma Etch Systems Market to Grow at 13.5% CAGR through 2032
By pmarketresearch, 2026-07-22
Plasma Etch System Market: Strategic Outlook for 2026 Decision-Makers
The global plasma etch system market is entering a decisive phase. After steady expansion through the early 2020s, the market reached a notable inflection by 2025 (base year) and, under our central forecast, grows at a compounded annual growth rate (CAGR) of 13.5% across the 2026–2032 horizon. Expressed in USD Million, the trajectory mapped in this study demonstrates both resilience and structural acceleration driven by advanced-node logic, memory scaling, heterogeneous integration, and emerging applications in quantum and medical microsystems. For executives planning capital allocation, supplier strategy, or R&D priorities in 2026, the findings and analytical frameworks in this PW Consulting briefing translate prospective market dynamics into actionable choices—while reserving the detailed segment-level tables and interactive models for the full report.
Plasma Etch System Market
Why this study matters for 2026 decisions
- Timing capital and capacity: The market’s projected expansion calls for precise timing of tool purchases, plant retrofits, and service investments to avoid overcapacity or costly expedited procurements.
- Supplier selection under volatility: Volatile specialty-gas markets and evolving emission regulations make supplier resilience and retrofit capabilities a first-order procurement criterion.
- Regulatory and emissions risk management: Tightening HFC/PFC controls and evolving domestic emission standards necessitate early investment in low-global-warming-potential process chemistries and remote plasma retrofits.
- Technology and ecosystem bets: Quantum-scale manufacturing, advanced packaging, and wafer-level microfabrication create differentiated demand profiles—decisions today on partnerships and pilot-line investments will shape market position for years.
What the PW Consulting report delivers (practical, decision-ready content)
- Comprehensive market sizing and trend models: Base year 2025 with historical series and forward projections through 2032 (USD Million); macro forecast anchored to a 13.5% CAGR for the forecast window.
- Scenario and sensitivity analysis: Three demand scenarios (base, upside, downside) with sensitivity to semiconductor cyclical swings, gas-price shocks, and regulatory tightening.
- CapEx and Total Cost of Ownership (TCO) models: Tool acquisition, retrofit, consumables, and energy footprints across typical deployment lifecycles—intended to support CAPEX committees and financial planning.
- Supplier due diligence packs: Strategic profiles, comparative capability maps, and vendor risk scores for key equipment vendors, OEMs, and aftermarket providers.
- Regulatory risk matrix and retrofit playbook: Quantified impact of major regulatory pathways (U.S. AIM Act, EU F-gas rules, and EPA emission factor changes) and recommended retrofit timelines and cost buckets.
- Supply chain stress tests: Gas supply scenarios (including high-volatility helium and specialty gases), alternative sourcing strategies, and inventory hedging approaches.
- Market concentration and competitive diagnostics: Concentration metrics, capability clusters, and acquisition targets with tailored M&A screening criteria.
Note: This overview intentionally omits granular regional and application breakdowns—those datasets, plus interactive charts and downloadable model files, are included in the full PW Consulting report.
Plasma Etch System Market
Key macro dynamics shaping the market
- Technology demand drivers: Continued node scaling in logic and memory, dense 3D stacking, and advanced packaging drive increased demand for precision etch capabilities. Adjacent sectors (medical microdevices, quantum manufacturing, MEMS) add diversification, smoothing some cyclical exposure but altering tool capability requirements.
- Gas and consumables volatility: Helium and other high-purity specialty gases have faced substantial price swings and constrained supply in recent years. Our stress tests show that sustained gas-price inflation materially increases TCO and shortens the payback for process efficiency investments.
- Regulatory compression on fluorinated gases: Both U.S. and EU policy actions are compressing allowable emissions and prompting accelerated adoption of low-GWP process chemistries, remote plasma chamber cleans, and deployment of abatement solutions. Notably, retrofitting chamber cleans to remote plasma systems has demonstrably reduced certain emission factors in practice—a retrofit lever found to be highly effective in our retrofit playbooks.
- Service and secondary markets: Refurbished and custom systems, plus tool-as-a-service models, are expanding as OEMs and independent providers chase aftermarket revenue and capacity-flexibility offerings. This creates optionality for fabs seeking lower-cost entry into new process capabilities.
Competitive landscape — strategic implications
The plasma etch equipment space is moderately fragmented, with a small group of established global OEMs operating alongside specialized niche suppliers and regional players. Market concentration metrics signal that the top three and five vendors do not dominate the industry in the way seen in some other semiconductor equipment segments—an important factor for buyers seeking competitive leverage in procurement.
Plasma Etch System Market
- Plasma Etch Inc. (Carson City, NV): A strong player in customized, refurbished, and niche process tools. Their strength is speed-to-deployment and cost-efficient refurbishment cycles—an attractive option for pilot lines, R&D users, and cost-sensitive fabs.
- Plasma-Therm LLC (Hauppauge, NY): Known for premium wafer-based etch and deposition systems and innovative partnerships. Recent corporate communications emphasize growth in etch+deposition platforms and strategic collaborations targeting scalable quantum manufacturing—indicative of a forward-looking product roadmap aligned with new application demand.
- SPTS Technologies / KLA (Newport, UK): Offers advanced platforms for a range of etch and dicing needs. Their product breadth and integration with metrology and process control capabilities position them as a go-to supplier for integrated process flows at advanced nodes.
- SAMCO Inc. (Kyoto, Japan): Focused on specialty deposition and surface treatment systems; recent technology introductions (single-wafer aqua plasma; high-temperature PECVD) and trade-show commitments signal a push into higher-temperature and specialty-process niches that intersect with next-generation packaging and microfabrication requirements.
- Trion Technology, Corial, GigaLane: Regional and niche specialists delivering complementary etch and strip solutions—important options for localized support, pilot production, and aftermarket services.
- Tokyo Electron, Applied Materials, Lam Research: These large-system suppliers integrate etch tools into broader fab toolsets for advanced logic and memory fabs. Their global service networks, scale, and integration capabilities make them strategic partners for large IDM and foundry customers.
Recent market signals and what they mean
- Trade shows and tech introductions: Public demonstrations and new-tool introductions (e.g., high-temperature PECVD, single-wafer plasma systems) are early indicators that vendors are pivoting toward high-throughput, specialty-process toolsets—buyers should test these technologies in pilot programs before volume commitments.
- Partnership announcements targeting quantum manufacturing: Collaborations between equipment vendors and quantum-focused firms point to a nascent commercial pathway for etch processes in quantum device fabrication; early engagement yields learning curve advantages.
- Regulatory and material pressures: Policy moves reducing HFC/PFC usage and the documented benefits from remote plasma retrofits are creating a near-term capex pull for abatement and process requalification—this is a predictable cost that should be included in 2026 capital planning cycles.
Risks, near-term triggers and mitigation levers
- Raw-material price shocks: Hedging strategies, multi-sourcing, and on-site gas reclamation can de-risk operations against spikes in helium and specialty gases.
- Regulatory tightening and abatement compliance: Prioritize retrofits, alternative chemistries, and abatement investments in the short term to avoid costly compliance-driven downtime.
- Cyclical semiconductor demand: Use flexible procurement (options, leases, refurbished tools) and staged capacity ramps to align spend with demand realization.
- Technology obsolescence: Maintain R&D collaborations and pilot-line access to validate breakthrough etch chemistries and architectures before scaling.
Actionable recommendations for 2026
- Embed gas-price scenarios into all TCO models: Plan for upside gas-cost cases and require vendors to disclose consumables sensitivity in quotes.
- Accelerate retrofit programs that reduce PFC and NF3 footprints: These often produce outsized regulatory-risk reduction per dollar spent.
- Pilot-new-tool introductions with clear KPIs: For emerging high-temp PECVD and single-wafer plasma systems, require six-month pilot gates linked to yield and throughput metrics.
- Exploit fragmentation for commercial leverage: Use competitive RFQs across global and regional vendors to extract favorable lead times and service terms; consider multi-vendor strategies that balance scale with local support.
- Develop aftermarket and service strategies: If you are an OEM or large fab, invest in refurbishment and tool-as-a-service offers to capture lifecycle revenue and provide lower-cost capacity.
- Prepare M&A and alliance playbooks: Target niche technology providers for inorganic capability extension or regional service providers to close support gaps quickly.
How PW Consulting can support your 2026 playbook
Our full Plasma Etch System Market report includes the complete dataset, regional and application segmentation, vendor scorecards, and interactive financial models that underpin the strategic recommendations summarized here. We offer tailored workshops to translate the models into facility-specific TCOs, procurement playbooks, and regulatory compliance roadmaps. For teams preparing 2026 capital plans, our bespoke diligence packages cover vendor technical due diligence, retrofit cost-benefit analysis, and a prioritized list of vendor and technology pilots to execute in Q1–Q2 2026.
To access the complete intelligence, including the full regional and application breakouts, vendor-level benchmarking, and downloadable scenario models, refer to the full PW Consulting report and dataset. The omitted granular tables and segmented forecasts are available in the full report and will equip your team to move from strategy to measurable execution in 2026.
For detailed analysis of this topic, please visit the official page: Plasma Etch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Driving Recorder Market to Grow at 8.5% CAGR (2026-2032)
By pmarketresearch, 2026-07-22
Driving Recorder (Car Dashcam) Market — Strategic Outlook for 2026 Decision-Making
As global road safety, fleet telematics and in-vehicle intelligence converge, the Driving Recorder (car dashcam) market has moved from a niche safety accessory into a strategically important product class for OEMs, Tier‑1 suppliers, fleet operators and aftermarket vendors. Our PW Consulting market study (base year 2025, historical 2020–2025, forecast 2026–2032) shows a sustained expansion trajectory driven by hardware quality improvements, AI-enabled video analytics and tighter regulatory scrutiny. The market reached a meaningful milestone in 2025 and is projected to continue growing at a compounded annual growth rate of 8.5% through the 2026–2032 forecast window.
Driving Recorder (Car Dashcam) Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a hinge year. Product roadmaps that integrate higher-resolution imaging, onboard AI and cloud connectivity are moving from prototype to commercial programs. Decisions made in 2026—about component sourcing, cloud partnerships, and product positioning—will determine whether a business captures premium value or competes on low-margin hardware.
Driving Recorder (Car Dashcam) Market -
Market momentum: After recovering from pandemic-era supply shocks and uneven demand through 2020–2023, the market expanded into 2024–2025 and enters a predictable upswing in unitization and ASPs driven by multi-channel and AI-enabled offerings.
Driving Recorder (Car Dashcam) Market -
Structural pressures: Two systemic forces—escalating semiconductor and memory constraints, and intensified national security-focused export controls—are reshaping sourcing strategies and commercial cycles. These constraints are already affecting product launch timing and margins.
What our PW Consulting report provides (practical, action-ready deliverables)
-
Integrated market sizing and seven-year forecasts (2026–2032) with scenario snapshots tuned to supply‑chain disruption, rapid AI adoption, and regulatory tightening.
-
Competitive mapping and vendor benchmarking that evaluates product portfolios, route-to-market, software stack maturity and cloud capability—scored against commercial KPIs.
-
Technology roadmap analysis that compares imaging sensors, codec strategies, onboard compute versus edge/cloud processing and ADAS convergence trends.
-
Supply‑chain risk register including supplier concentration, lead-time stress tests, and procurement playbooks to mitigate memory and semiconductor scarcity.
-
Commercial playbooks: pricing scenarios, subscription/recurring-revenue models, fleet monetization levers and OEM co‑development templates.
-
M&A and partnership heatmaps highlighting likely consolidation targets, white‑space entrants and strategic fit matrices for investors and corporate development teams.
-
Regulatory impact assessment covering export controls, data privacy and cross-border telemetry rules with recommended compliance architectures.
Market shape and competitive dynamics — what incumbents and challengers are doing
The market exhibits a moderate fragmentation profile: a handful of vendors capture a material share of value while numerous specialty players compete on feature differentiation, price and distribution. This structure favors both continued product specialization (multi‑channel, parking surveillance, AI analytics) and opportunistic consolidation. Below are strategic snapshots of key players we benchmarked in the study.
-
Viofo (Shenzhen, China) — Strengths: competitive hardware engineering, sensor sourcing and professional-grade feature sets. Strategic implication: along with other China-origin OEMs, Viofo is well positioned to scale manufacturing quickly; its win pathway depends on moving beyond hardware into software services and channel partnerships for value capture.
-
BlackVue / Pittasoft (Seongnam-si, South Korea) — Strengths: premium positioning, cloud-enabled surveillance and fleet-focused architectures. Strategic implication: high-value features like cloud parking surveillance and remote evidence retrieval command recurring revenue opportunities, but rely on robust service platforms and infrastructure partnerships.
-
70mai (Shanghai, China) — Strengths: rapid feature innovation, AI-enabled safety functions and strong consumer channel penetration. Strategic implication: can scale software updates and consumer subscriptions, but must protect margins against component inflation and defend brand differentiation as lower-cost rivals adopt similar features.
-
Garmin (Olathe, USA) — Strengths: integration with navigation/GPS ecosystems and voice/UX differentiation. Strategic implication: Garmin can leverage its mapping and voice platforms to upsell integrated solutions to vehicle buyers and fleet customers.
-
Thinkware (Coquitlam, Canada) — Strengths: ADAS alerts, parking surveillance and imaging sensor quality; recent product introductions underscore an aggressive premium strategy. Strategic implication: Thinkware’s play for fleet and premium aftermarket buyers signals competitive pressure on margins among high-end suppliers who must justify price through service and analytics.
-
Vantrue (United States) — Strengths: high-end multi-channel video and strong security-focused value proposition. Strategic implication: niche segmentation around multi-camera architectures and secure logging offers a defensible position against commoditization.
-
Nextbase (United Kingdom) — Strengths: brand recognition, quality design and fleet-oriented solutions. Strategic implication: known brands can transition to fleet and subscription models, but need to accelerate cloud/analytics capability.
Recent industry developments and their strategic consequences
-
Fleet AI adoption: Geotab’s 2025 GO Focus Plus AI dashcam deployment demonstrated meaningful behavior change in pilots—highlighting the rising importance of integrated video intelligence platforms for reducing risk and insurance spend. For suppliers, this raises the bar on software analytics and long‑term service value.
-
OEM convergence: Magna’s public advances in integrating higher-resolution imaging and onboard recording into ADAS modules signal potential encroachment by Tier‑1s into traditional dashcam territory—creating both a white-label OEM opportunity and a margin squeeze for independent vendors.
-
Product differentiation: 2026 launches from established players introduced hybrid solutions that couple higher-resolution sensors with RADAR and advanced parking modes—validating that multi-sensor convergence is migrating from premium experiments to mainstream capabilities.
-
Supply strain and cost: memory prices and semiconductor lead times have materially worsened since late 2025, elevating BOM risk and elongating product delivery timelines. Procurement strategies and product architectures must be stress-tested against lead-time scenarios.
-
Policy and trade: a wave of export-control and national-security legislation is reshaping sourcing flexibility for certain component categories. Companies with cross-border supply chains should evaluate compliance exposure now—especially those dependent on constrained imaging and compute components.
Recommended strategic moves for 2026
-
Initiate scenario-based product roadmapping that incorporates three procurement states (optimistic, baseline, stressed). Prioritize modular architectures that allow for component swaps without full redesigns.
-
Lock in strategic supply through long‑term agreements and qualified second-source suppliers for memory and key SoCs. For critical components, consider co-investment or allocation agreements when feasible.
-
Accelerate software-led monetization: subscription services (cloud storage, analytics), telematics bundles for fleets, and embedded post‑event analytics materially improve lifetime value and dampen hardware volatility.
-
Explore partnerships with cloud providers and telematics platforms to offload storage and analytics costs while preserving evidence integrity and privacy compliance.
-
For investors and M&A teams: target companies with robust software platforms and recurring revenue, or specialized sensor/AI capabilities that are hard to replicate under current supply constraints.
-
Prepare for compliance complexity: embed export-control risk assessments into supplier selection and contractual clauses; evaluate geofencing or selective feature flags to maintain market access.
Concluding perspective — the strategic value of the full report
For executives making resource-allocation and product roadmap choices in 2026, access to accurate, scenario-driven market sizing and supplier intelligence is no longer optional. Our base-year analysis captures the market condition through 2025 and projects forward under an 8.5% CAGR assumption across 2026–2032, offering a structured view of demand, price pressure and value‑pool shifts. The full PW Consulting study contains the granular, actionable datasets—region- and application-level forecasts, vendor market shares and price curves, segment-specific unit economics and a downloadable supplier-risk matrix—that are intentionally withheld in this preview to preserve the competitive edge our clients require.
If your 2026 strategy depends on securing supply, defending margin, or capturing recurring-service value in the driving-recorder ecosystem, this report will give you the tactical frameworks and decision-grade intelligence to act confidently. For the complete dataset, vendor scorecards and proprietary scenario models, please consult the full PW Consulting market report.
For detailed analysis of this topic, please visit the official page: Driving Recorder (Car Dashcam) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com