

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rail Market to Reach USD 300.51B by 2032 at 6.47% CAGR (2026–2032)

Rail Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
Executive preview
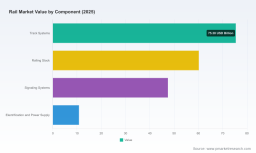
By 2026, rail will no longer be a legacy transport sector that simply maintains lines and schedules. Our Rail Market study — built on a 2020–2025 historical base and projecting through 2032 — demonstrates that the industry has entered a multi-year growth phase driven by fleet renewal, signalling modernisation, electrification programmes and freight capacity upgrades. The global market expanded from approximately USD 142.5 Billion in 2020 to about USD 193.8 Billion in 2025 and, under our central-case assumptions, is projected to approach USD 300.5 Billion by 2032, representing a compound annual growth rate of roughly 6.47% across the forecast horizon. For boards, strategy teams and investors preparing 2026 plans, these macro trajectories change the calculus on capital allocation, partnerships and technology investment.
Rail Market
Why this matters for 2026 decision-making
-
Investment timing: With a sustained mid-single-digit CAGR baked into our baseline, the optimum window to commit to expansion or to retrofit fleets is now. Delaying multi-year projects risks missing a period of cost-efficient equipment delivery and favourable financing conditions that are likely to prevail in the early-to-mid forecast window.
Rail Market -
Risk-adjusted returns: The market’s scale supports larger strategic plays — consolidation, vertical integration and technology acquisition — but the market concentration metrics we model require disciplined selection. The top-tier players together account for a material share of supply, creating both barriers and partnership opportunities for new entrants.
Rail Market -
Operational transformation: Digital signalling, automated operation technologies and asset analytics are migrating from pilot projects to commercial rollouts. Systems-level upgrades create service-level differentiation and new revenue lines for suppliers and operators prepared to adopt them.
What the market snapshot tells us (high level)
Our modelling combines a granular market-sizing exercise with scenario stress tests. The base-year analysis (2025) captures the revenue pool approaching USD 194 Billion and reconciles manufacturers’ shipments, systems integrators’ contracts and maintenance/service flows. From this base we apply demand drivers and constraint overlays to produce a 2026–2032 outlook that reaches roughly USD 300.5 Billion in our central case. Alongside growth, the market exhibits moderate concentration: the three largest suppliers control just over half of industry revenues, and the top five capture close to six in ten dollars of the market — a structure that sustains healthy competition while enabling scale advantages for incumbents.
Key growth vectors and strategic implications
-
Fleet renewal and capacity expansion: Many operators face ageing rolling stock and constrained freight corridors. The replenishment cycle is creating sustained demand for rolling stock and associated systems. For suppliers, winning specification slots hinges on performance guarantees, lifecycle cost modelling and local-service commitments.
-
Signalling and automation: Next-generation track circuits and automated traction systems are reaching regulatory acceptance in multiple jurisdictions. Early movers that combine signalling hardware with proven software stacks and services contracts will capture premium margins as operators aim to raise throughput and safety simultaneously.
-
Electrification and power supply: Electrification programmes, paired with grid modernisation, are a multi-year deployment opportunity. Companies that can bundle civil, electrical and systems integration services will be advantaged versus point-solution vendors.
-
Maintenance-as-a-Service (MaaS): The shift from CAPEX to outcomes-based procurement is accelerating. Operators increasingly prefer long-term, risk-sharing maintenance arrangements that require suppliers to demonstrate predictive maintenance capabilities and proven asset performance analytics.
Competitive landscape — who matters and why
The market is anchored by industrial-scale manufacturers, specialist systems providers and vertically integrated suppliers. Our coverage spotlights firms that combine manufacturing scale with systems integration capabilities and well-developed after-sales networks. Four illustrative players from our competitive analysis:
-
voestalpine Railway Systems Nortrak — a specialist in special trackwork and turnout systems with targeted asset expansion moves in North America. Recent asset acquisitions indicate an explicit strategy to increase capacity for complex track components and shorten lead times for large transit and Class I customers.
-
Pandrol — a long-established leader in fastening systems and resilient track infrastructure. Their global deployment experience and deep product portfolio position them well to capitalise on large retrofitting and high-availability projects.
-
Vossloh AG — a full-spectrum supplier of turnouts, sleepers and maintenance solutions with a clear focus on freight, high-speed and urban markets. Vossloh’s mix of product breadth and maintenance services enables comprehensive lifecycle offers that many customers now demand.
-
Steel Dynamics Inc. — a regional rails manufacturer notable for its capacity to produce long, hot-rolled rails with high dimensional consistency. In markets where long welded rail and durability are differentiators, such manufacturing capabilities matter strategically.
Recent industry developments reinforce these dynamics. Strategic factory openings and product launches by major OEMs are expanding regional manufacturing footprints and introducing AI-enabled capabilities in rolling stock. M&A activity and asset acquisitions have been used to shore up supply chains and capacity ahead of expected tender waves.
Operational and regulatory dynamics to factor into plans
-
Supply chain and raw materials: Steel and rail-specific inputs remain key variables. Manufacturers with vertical integration or secured long-term supply agreements will experience fewer schedule disruptions and can offer more competitive guarantees.
-
Labour and delivery cadence: Large industry gatherings and cross-border supplier engagement remain critical for deal origination and skills transfer — events in 2026 will shape procurement calendars and hiring cycles for the remainder of the decade.
-
Regulation and safety standards: Regulatory shifts toward advanced track circuitry and broken-rail detection influence procurement specifications. Suppliers that can demonstrate compliance and field-proven performance will have a distinct advantage in public tenders.
What our report delivers — practical, transaction-ready outputs
PW Consulting’s Rail Market study is designed for executives who need actionable intelligence rather than theory. The report package includes:
-
A financial market model with historical reconciliation (2020–2025) and scenario-linked forecasts (2026–2032) that allow you to stress-test revenue, margin and capital outcomes against price, volume and policy shocks.
-
Supplier benchmarking and a concentration map that identifies capability gaps, partnership opportunities and M&A targets by technology stack and service model.
-
Procurement and localisation playbooks for rolling stock and track systems — including contracting structures, warranty models and performance KPI templates designed to reduce lifecycle cost.
-
Operational playbooks for signalling upgrades, electrification rollouts and maintenance outsourcing, with implementation roadmaps and suggested governance frameworks for 24–36 month programmes.
-
Deal origination lists and a watchlist of near-term tenders and capex programmes curated to support corporate development and private equity screening activities.
Importantly, the report intentionally omits no critical datapoint — every segment and regional split, down to component-level volumes and pricing assumptions, is present in the full dataset and model. The summary here deliberately refrains from reproducing those granular figures so you see the strategic logic without exposing the proprietary granularity we reserve for authorised subscribers.
How to use this study in your 2026 planning cycle
-
Board-level capital allocation: Use the scenario model to test where to accelerate capex (e.g., factories, localisation) versus where to prioritise OPEX optimisation.
-
M&A and JV screening: Apply our supplier benchmarking to identify targets that provide capability adjacency or immediate access to service contracts.
-
Procurement strategy: Adopt the playbook to convert one-off procurements into outcomes-based contracts that align incentives across operators and vendors.
-
Technology adoption: Use the signalling and automation readiness modules to sequence pilot-to-scale rollouts and to size investment needs for safety certification and workforce retraining.
Methodology and confidence
The study integrates bottom-up shipper and OEM activity data, public tender pipelines, maintenance contract disclosures and PW Consulting primary interviews. Historical data spans 2020–2025; the base year is 2025, and the forecast window covers 2026–2032. We apply probabilistic scenario analysis to produce a central-case CAGR of approximately 6.47% and stress-case ranges for downside and upside contingencies. Market concentration metrics are derived from reconciled revenue pools and public financials, offering a robust view of industry structure for M&A and partnership decisions.
Final perspective and next step
The macro numbers tell a clear story: the rail sector’s addressable pool will expand materially over the coming decade, creating openings for capacity investors, systems integrators, digital-solution providers and operators that reconfigure procurement for lifecycle outcomes. Yet the devil is in the detail — winning in 2026 requires granular intelligence on segment demand curves, tender timing, specification language and supplier delivery profiles.
PW Consulting’s full Rail Market report supplies that intelligence. This executive preview highlights the strategic takeaways; the complete dataset, segment revenue splits, and contract-level analysis are available through the report portal for subscribers and authorised clients. If your 2026 strategy depends on precise timing, supplier selection or a defensible M&A thesis, the full study is the operational toolkit you’ll rely on.
For detailed analysis of this topic, please visit the official page: Rail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com