

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Shea Butter Market to hit USD 1,687 Million by 2032 at 8.2% CAGR
By pmarketresearch, 2026-07-22
Shea Butter Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
Between 2020 and 2025 the global shea butter market expanded materially, driven by rising demand across personal care, food and nutraceutical applications. Our base-year analysis (2025) shows the market reached just under USD 1.0 billion after a steady recovery from 2020. Looking forward, PW Consulting projects continuation of this expansion through the 2026–2032 forecast window at a compound annual growth rate of 8.2%, with the market entering new structural dynamics as policy, traceability and value‑addition shape trade flows and profitability.
Shea Butter Market
Why this report matters for 2026 strategic decisions
- Supply volatility has become a strategic variable. Policy shifts and minimum-price interventions in producing countries, together with temporary export controls, are changing the availability and short‑term economics of raw kernels and semi‑processed butter. Procurement teams can no longer assume historical supply elasticities; scenario-driven sourcing is now essential.
- Value‑addition is shifting the centre of gravity. Producing countries are taking active measures to capture more value domestically. Players that can align sourcing with local processing initiatives — or secure strategic tolling/partnering arrangements — will be advantaged.
- Regulatory and market-entry requirements are non‑negotiable for food and cosmetic routes-to-market. Major consumer markets are applying stricter labelling, hygiene and HACCP expectations; compliance readiness is a prerequisite for commercial access and premium positioning.
- Fragmentation creates both risk and opportunity. The market remains only moderately consolidated: a small number of processors and exporters account for a meaningful share of trade, but a long tail of local suppliers persists. This dynamic supports niche differentiation while exposing buyers to concentration risk at key nodes of the supply chain.
Recent developments that will influence 2026 strategies
- Producer‑country interventions in 2025–2026 altered price and trade incentives: minimum pricing in key producing zones and temporary export bans aimed at stimulating domestic processing have already produced measurable supply re‑routing and price volatility.
- Regulatory alignment in destination markets (notably the EU) requires rigorous labelling, hygiene systems and HACCP implementation for food applications — creating a higher bar for market access but also supporting premiumisation of compliant products.
- Commercial evolution among processors and fractionators is accelerating: leading refiners and specialty fat houses are investing in fractionation, derivative streams and certification to meet cosmetic and pharmaceutical grade requirements.
What PW Consulting’s full report delivers (practical, executable content)
Our Shea Butter Market study is built as a decision tool for C‑suite and corporate strategy teams planning for 2026. The report combines a robust quantitative backbone with operational playbooks and deal-level intelligence. Core deliverables include:
Shea Butter Market
- Historical market sizing (2020–2025), base‑year benchmark (2025) and forward revenue model through 2032 with sensitivity cases tied to key policy and yield scenarios.
- Supply‑chain mapping from kernel collection to refined fractions, highlighting logistics choke points, cost buildups, and quality risk factors at each node.
- Price and margin models for raw, refined and fractionated products under alternate trade‑policy and currency scenarios.
- Regulatory compliance checklist for major destination markets (including EU food and cosmetic entry requirements such as mandatory labelling, hygiene and HACCP frameworks).
- Go‑to‑market playbooks for manufacturers and brand owners covering product positioning, upstream partnerships, traceability systems and certification pathways (organic, fair‑trade, ISO standards).
- Investment and M&A screen: short-list of attractive targets by capability (processing, refining, fractionation, certification) with high‑level valuation bands and integration risks.
- Supplier scoring matrix and negotiation playbook that operational procurement teams can apply immediately to reduce exposure to single‑node disruption.
- Scenario toolkits for CFOs to stress‑test cashflow and working‑capital under price shocks and policy interventions.
Note: the full report contains granular segmentation (by region, product type and application), pricing ladders and the proprietary revenue tables used to generate our forecasts. Those detailed splits are reserved for the comprehensive release.
Shea Butter Market
Competitive landscape — who matters and why
The competitive picture is shaped by a mix of global processors, refiners, and origin‑based specialists. Top firms combine sourcing scale, processing flexibility and established offtake relationships with cosmetic and food customers. Key archetypes include:
- Large processors/exporters with integrated supply chains. Firms in this group focus on aggregating kernels and converting them into stable supply flows for global manufacturers. Their strength lies in logistics, long‑term supplier agreements and the ability to service large industrial buyers.
- Refiners and fractionators. Companies that add value through refining and fractionation are capturing margin uplifts by supplying cosmetic‑grade derivatives and tailored functional fats for food applications.
- Origin‑level specialists. Smaller organisations rooted in producing countries that emphasise organic, community‑based sourcing and social impact — attractive to brands pursuing traceability and sustainability narratives.
Representative companies profiled in our study include firms that act across these archetypes: large-scale processors focused on West African sourcing and exports; European refiners developing value‑added fractions; Ghanaian origin exporters working at village level to empower rural livelihoods; and South Asian wholesalers supplying bulk organic and unrefined butter to cosmetics markets. Together, they illustrate the strategic choices incumbents and new entrants will need to make in 2026: invest in scale, specialise in fractions, or own provenance and certification as a premium signal.
Market concentration is meaningful but not overwhelming: the top few players hold a substantial share of global processing capacity, while a broad base of smaller suppliers continues to serve niche, certified and local end‑markets.
Immediate strategic actions for 2026 (practical checklist)
- Run a 90‑day supply stress test. Identify single‑supplier exposures and simulate outcomes from export controls or regional price floors. Create contingency lists for immediate secondary sourcing and buffer stock triggers.
- Pursue selective upstream partnerships. Negotiate multi‑year offtake or tolling agreements with origin processors that include quality KPIs, capacity reservations and joint investments in drying, testing and packaging to reduce contamination premiums.
- Prioritise compliance readiness. For food and cosmetic routes, certify hygiene, traceability and HACCP systems now — failure to comply will delay market entry and reduce access to higher‑margin channels.
- Accelerate product differentiation. Invest in fractionation and formulation capabilities (or partner with specialty refiners) to move away from commodity butter sales toward higher‑value functional ingredients for cosmetics and pharma.
- Embed sustainability into commercial terms. Build sourcing programmes that combine measurable livelihood outcomes with third‑party verification; these programmes will protect brand equity and facilitate premium pricing.
- Use financial hedges selectively. Consider indexed pricing clauses, price‑band contracts and working‑capital facilities tied to inventory buffering to protect margin during policy shocks.
- Scan for M&A and alliance targets. Look for origin processors with stable supplier relationships, refiners with fractionation know‑how, and certification specialists that can be bolt‑on assets to accelerate market access.
Expected near‑term scenarios and implications
Our scenario analysis models three plausible 18‑month pathways for 2026: (1) policy normalization with gradual re‑opening of export channels and investment in local processing; (2) intermittent producer‑country protectionism with episodic price swings and trade diversion; and (3) accelerated premiumisation driven by regulatory tightening and consumer demand for certified supply chains. Each scenario implies different capital allocation, procurement, and product strategies — the full report provides the scenario matrices, probabilistic weightings and tactical responses tailored to buyers, processors and brand owners.
Next steps — how to use this research
PW Consulting’s Shea Butter Market study is designed to move teams from high‑level awareness to operational readiness. If you are planning procurement, launching a new personal‑care line in 2026, considering a processing investment, or evaluating acquisition prospects, our research provides the market architecture, the risk playbooks and the commercial levers you need.
For practitioners who require the detailed segmentation, granular revenue tables, supplier scoring sheets and executable M&A targets that underpin this executive overview, please refer to the full PW Consulting report. The comprehensive dataset and models are provided with templates you can deploy immediately in procurement tenders, investor diligence and product roadmaps.
For detailed analysis of this topic, please visit the official page: Shea Butter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Honing Machines Market to Reach USD 1,126M by 2032 at 5.5% CAGR
By pmarketresearch, 2026-07-22
Honing Machines Market 2026: Strategic Imperatives for Decision-Makers
As organisations plan capital investments and competitive plays for 2026, understanding the honing machines market’s trajectory and operational realities is essential. PW Consulting’s latest market brief—anchored on a 2025 base and a 2026–2032 forecast horizon—shows a market positioned for steady, mid-single-digit growth. The global market, measured in USD Million, rose through the historical window and reached an estimated USD 773.0 Million in 2025. Under our forecast scenarios the market advances to about USD 841.5 Million in 2026 and is projected to surpass USD 1.12 Billion by 2032, reflecting a compound annual growth rate (CAGR) of approximately 5.5% across the projection period.
Honing Machines Market
Why this study matters for 2026 decision cycles
- Timing capital: OEMs, Tier suppliers and specialised job shops face compressed windows to allocate CapEx for machining upgrades. Our synthesis links macro demand drivers to short-term spend cycles—helping CFOs and plant managers prioritise investments in 2026 that balance productivity gains and payback horizons.
- Supplier strategy: With the market exhibiting a moderate concentration (top-3 firms control a material share of supply and the top-5 an even higher portion), buyer leverage, lead times and aftermarket support differ markedly by supplier. Procurement teams need finely tuned supplier-selection criteria beyond list prices—our study provides that framework.
- Technology and operations alignment: The interplay of automation, tooling selection and operator skills determines realised throughput and part quality. For leaders planning shop-floor transformation in 2026, this report translates high-level technology claims into operational KPIs and TCO implications.
Executive snapshot — what the research reveals (without giving away the playbook)
- Market trajectory: A resilient recovery and steady expansion through 2032 driven by maintenance & aftermarket demand in mature industries and new build requirements where precision bores are critical.
- Competitive shape: A marketplace with several well-established global OEMs complemented by regional manufacturers and specialist tooling providers. Market concentration indicates meaningful advantages for larger names in service networks and R&D, while niche vendors compete on speed-to-application and cost flexibility.
- Margin levers: Service contracts, consumables (notably high-value abrasives), retrofit packages and automation integration are prominent margin drivers beyond the initial machine sale.
Report contents — actionable modules included
The research was developed to be operationally useful. Key deliverables embedded in the full study include:
Honing Machines Market
- Market sizing and validated forecasting models (historical 2020–2025; base year 2025; forecast 2026–2032) with scenario sensitivity to end-market shocks and commodity swings.
- Buyer decision matrices and procurement playbooks—objective frameworks that combine CapEx, uptime, consumable spend, service coverage and typical payback thresholds for different customer archetypes.
- Technology adoption roadmaps—practical guidance on when to adopt multi-axis CNC honing, twin-spindle systems, and retrofit automation to balance throughput and operator availability.
- Competitive benchmarking profiles and capability matrices for a curated set of global and regional vendors, with suggested engagement strategies for sourcing, co-development and service partnerships.
- Supply chain risk maps—including raw material bottlenecks, single-source tooling dependencies, and recommended mitigation (dual-sourcing, inventory strategies, long-term agreements).
- M&A and partnership playbooks—criteria to assess bolt-on targets, integration challenges and value-capture mechanisms for strategic buyers and financial sponsors.
- Regulatory and workforce compliance checklists, including operator competence regimes and suggested training curricula to reduce operational risk.
Competitive landscape — what practitioners must know
The market is served by a mix of legacy OEMs, highly specialised European precision engineers, established North American providers and an expanding set of medium-sized manufacturers across Asia. Several firms stand out because of their deep portfolios across horizontal and vertical architectures, tooling ecosystems, and strong aftermarket footprints. Examples include long-established precision tool and machine providers known for broad global service networks, German and Swiss engineering houses notable for CNC and multi-spindle innovations, and Asian manufacturers offering compelling value and local presence.
Honing Machines Market
Recent industry moves illustrate how vendors are positioning for 2026:
- Product introductions and line upgrades continue to focus on twin-spindle and universal multi-spindle designs, reflecting customers’ demand for higher throughput without increasing shop-floor footprint.
- Major trade-show engagements in early 2026 reinforced emphasis on hydraulic and high-precision bore finishing solutions for critical hydraulic, automotive and engineering components.
- Incremental product enhancements target improved maintainability, digital diagnostics and simplified operator interfaces—features that materially reduce the labour intensity of deployment.
Market dynamics and operational headwinds
Understanding the practical constraints that shape procurement and adoption is critical for 2026 planning:
- Workforce constraint: A persistent shortage of skilled operators remains one of the leading adoption barriers. Organisations that pair machine investments with structured training pathways and operator competency frameworks will realise higher effective throughput.
- Core raw materials: Diamond abrasives and carbide tooling are the primary consumable inputs. Supply tightness or price swings in these commodities have out-sized impacts on operating costs and unit economics—especially for high-volume honing applications.
- Regulatory and standards compliance: Operator competence and machine operation guidelines increasingly reference formal standards. Compliance-ready training and certification can be a differentiator in regulated supply chains.
- CapEx realities: Mid-range CNC honing machines commonly transact within a defined capital band. Buyers should assess not only sticker price but also lifecycle consumable spend, maintenance cadence and local service availability to evaluate true cost of ownership.
Strategic implications and recommended actions for 2026
- Prioritise investments that reduce labour sensitivity. Where possible, opt for machines and vendor packages that include automation-ready interfaces, advanced diagnostics and remote-support agreements. This reduces exposure to operator shortages and shortens ramp-up.
- Lock in consumables supply. Establish strategic relationships or long-term agreements with abrasives and tooling suppliers to stabilise unit economics. Consider small-scale vertical integration or exclusive distribution agreements in strategic jurisdictions.
- Make service networks a procurement criterion. The delta in effective uptime between vendors with dense local service footprints and those without will materially exceed purchase-price differentials in many operating contexts.
- Adopt a portfolio approach to CapEx. Blend targeted brownfield retrofits, where modern honing heads and controls can elevate legacy assets, with greenfield acquisitions of multi-spindle or CNC systems for new lines. This balances cashflow and productivity impact.
- Evaluate M&A or partnership pathways. For firms seeking rapid capability expansion, selectively acquiring regional specialists or contracting exclusive tooling partnerships can accelerate market access while managing integration risk.
How we translate findings into 2026-ready decisions
PW Consulting’s deliverables are structured to move executives from insight to action. The full study includes ready-to-use investment templates, procurement scorecards, and an executive dashboard that maps potential investment outcomes against key performance targets for 2026–2028. For teams preparing board-level CapEx requests, the combination of validated market sizing, technology TCO models and supplier engagement strategies enables tightly argued, risk-adjusted proposals.
Next steps — where to get the full intelligence
This introduction highlights strategic lines and operational contours you need to evaluate honing machine investments in 2026. The full PW Consulting report contains the detailed segmentation, supplier matrices, financial case models and granular regional and application forecasts that underpin the guidance summarized here. If your 2026 plan involves upgrading bore-finishing capabilities, expanding service footprints, or evaluating M&A in this sector, the full report provides the models and templates to accelerate decision-making and reduce execution risk.
Contact PW Consulting to receive the complete study and the toolkit designed to convert the market’s steady growth and consolidation dynamics into executable advantage.
For detailed analysis of this topic, please visit the official page: Honing Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Optical Films Market to Grow 7.1% CAGR to USD 399M by 2032
By pmarketresearch, 2026-07-22
Optical Films Market — Strategic Outlook for 2026 Decision Makers
Executive summary
By 2025 the global optical films market had scaled into a clearly commercial phase, reaching an estimated USD 249.15 Million (base year 2025). The market has expanded from roughly USD 177.15 Million in 2020 and, under current structural drivers, is projected to continue at a compound annual growth rate (CAGR) of 7.1% into the 2026–2032 forecast window — reaching an expected USD 399.0 Million by 2032. These headline numbers mask important inflection points that will determine winners and losers in 2026: component engineering (ultra-thin and flexible films), sustainability-driven product redesign, and a reshaping supply chain driven by tariffs, raw material volatility, and regionalization efforts.
Optical Films Market
Why this study matters for corporate strategy in 2026
- Capital allocation: validate or reprioritize investments in new film lines, coating capability, or localized manufacturing to protect margins and time-to-market.
- Supplier strategy: redesign sourcing to manage polymer and specialty-chemical exposure, and to mitigate tariff and export-restriction risk.
- Product roadmap alignment: map optical-film capabilities to end-market shifts — displays, automotive HUD/AR systems, and flexible electronics — to capture premium ASPs.
- M&A and partnership screening: quantify opportunities in consolidation and targeted partnerships that accelerate technology access or regional scale.
Market trajectory and what the aggregated numbers reveal
The reported growth path (2020 → 2025 → 2032) highlights a market moving from component commoditization toward engineered differentiation. Demand remains tied to display cycles, but the marginal growth is coming from higher-value features: thinner form factors for flexible OLEDs, brightness-enhancement stacks that reduce power draw, and films engineered for automotive HUDs and AR overlays. This evolution supports sustained mid-single-digit to high-single-digit CAGR rather than a rapid commoditization-driven price collapse.
Optical Films Market
Equally important is market structure: concentration is moderate. The three largest firms account for roughly one-third of sales, and the top five approach the mid-forties in aggregate share. That profile creates room for focused entrants and regional champions while preserving scale advantages for incumbents that control advanced polymers, coating lines, and intellectual property.
Optical Films Market
Supply-chain and cost dynamics — levers that determine 2026 outcomes
Several structural noise factors will shape decision risk and opportunity:
- Raw-material volatility: polymers such as PET and TAC, and specialty chemicals used in coatings and ITO processes, have shown price swings that materially affect gross margins. Sustainability mandates and recycling requirements add complexity — both compliance costs and an opportunity for premium positioning.
- Regulatory and tariff exposure: export restrictions and higher tariffs on specialty chemicals and certain optical components have already forced re-routing of supply and decision-makers to reassess supplier footprints. This dynamic will continue to push localization and inventory strategies.
- Labor and capacity risks: material shortages and extended lead times have driven investments in localized production and strategic stockpiling. Firms that manage lead-time variability through dual-sourcing or near-shore capacity stand to protect market share in 2026.
- Technology substitution: alternatives to traditional ITO and emerging nanostructured coatings are creating both product-risk and product-upside scenarios depending on a company’s R&D posture.
Competitive landscape — tactical implications for 2026
The competitive map comprises a mix of chemical majors, specialty-film producers, and vertically integrated electronics suppliers. Each archetype implies a different response from buyers and competitors:
- Large diversified players (scale and IP): Firms such as 3M and Eastman leverage broad chemistry expertise and global manufacturing, enabling fast product introductions and capacity expansion. Their moves (e.g., ultra-thin polarizers, new Asia Pacific capacity) set technology and cost baselines for the market.
- Regional champions and speciality suppliers: Companies like Zeon, Toray, Nitto, and Toyobo focus on transmittance, haze control and module-level integration. Their strengths are product customization and relationships with display OEMs.
- Battery and display conglomerates: Suppliers such as Samsung SDI bring integration advantages with OEM customers and can accelerate co-development for next-generation panels.
- Sustainable innovators: LG Chem’s recyclable optical film portfolio is an example of product innovation that addresses regulatory and OEM sustainability mandates, presenting a pricing and differentiation lever for first movers.
Recent corporate activity confirms these patterns: new ultra-thin polarizer launches, expanded manufacturing capacity in Asia, partnerships to develop HUD/AR-specific films, and recyclable product portfolios. These are not isolated events — they signal strategic positioning that will be decisive for contract negotiations and OEM roadmaps in 2026.
What the full PW Consulting report delivers — practical, executable modules
This study goes beyond market sizing to provide operating teams and GMs with tools to move from insight to action. Highlights include:
- Scenario-based demand forecasts: three strategic scenarios (base, tariff-stress, sustainability-accelerated) with implications for capacity, pricing, and working capital.
- Supplier scorecards and risk heat maps: standardized metrics to evaluate supply continuity, raw-material exposure, tariff vulnerability, and ESG compliance.
- Capex prioritization framework: NPV and payback templates tailored to different film technologies and regional investment cases.
- Pricing sensitivity and margin-protection model: a simple-to-deploy tool that quantifies the margin impact of polymer price swings, tariff shocks, and volume shifts.
- M&A and partner-screening playbook: target filters, valuation moats, and integration checklists focused on capability accretion (e.g., coating lines, low-haze polymer IP, recycling tech).
- Commercial playbooks: negotiation levers for OEM contracts, sample-term sheets for long-term agreements, and roadmap alignment templates for co-development with display OEMs and automotive integrators.
Recommended strategic plays for executives in 2026
Based on the market trajectory and competitive moves, PW Consulting recommends executives prioritize a portfolio of six pragmatic plays:
- Dual-track capacity strategy: combine a core long-term facility with flex capacity (contract manufacturing or modular lines) to manage demand spikes and tariff risk without overcommitting capital.
- Sustainability premium: invest selectively in recyclable or lower-carbon film lines to secure OEM sustainability mandates and capture premium pricing where composites are required.
- Raw-material hedging and vertical partners: negotiate multi-year supply agreements with polymer producers and assess minority investments in upstream specialty-chemical capacity.
- Targeted partnerships for automotive/AR: co-develop films tuned for HUD and AR to lock in design wins as automotive displays drive a layer of specialized demand.
- M&A for capability and regional scale: pursue tuck-ins that add low-haze/high-transmittance IP or regional manufacturing footprints in low-tariff jurisdictions.
- Operational digitization: deploy inline metrology and predictive quality controls to reduce scrap, tighten specifications for premium films, and accelerate time-to-sample for OEMs.
Governance, metrics and the 100-day play
Translate strategy into measurable outcomes. Key KPIs for 2026 should include:
- Gross margin by film family (engineered vs commodity)
- Capacity utilization and time-to-ramp for new lines
- Supplier concentration index and tariff exposure score
- Time-to-sample for OEM design cycles
- ESG compliance and recycled-content percentage for qualifying SKUs
A prioritized 100-day plan should establish a cross-functional war room: procurement to renegotiate polymer contracts, R&D to accelerate recyclable-film pilots, and commercial teams to secure design-win commitments with tier-1 OEMs.
Conclusion — where PW Consulting adds value
The optical films market’s headline growth (mid-to-high single digit CAGR) is straightforward; the strategic complexity is not. The interplay of technology shifts, sustainability mandates, tariff regimes, and supplier footprints creates a high-stakes environment for capital deployment and customer lock-in. PW Consulting’s report turns the underlying data into executable strategies: risk-mitigated investment cases, supplier playbooks, and commercial tools that let you win premium share without overexposing the P&L.
For corporate leaders preparing budgets, negotiating OEM contracts, or assessing M&A targets in 2026, the practical modules of this study — supplier scorecards, scenario demand curves, capex prioritization and a negotiation playbook — are the instruments that convert a favorable market trajectory into durable competitive advantage. To review the full analysis, proprietary segment detail, and the plug-and-play financial models that accompany this executive brief, please access the complete PW Consulting Optical Films Market report.
For detailed analysis of this topic, please visit the official page: Optical Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Natural Astaxanthin Market Poised for 9.1% CAGR, Hits USD 372M in 2025
By pmarketresearch, 2026-07-22
Natural Astaxanthin Market: Strategic Imperatives for 2026
Summary for decision-makers
As organizations shape their 2026 investment and commercial agendas, the natural astaxanthin market presents a distinct combination of steady expansion, concentrated supplier power, and evolving regulatory boundaries that together determine near-term opportunity windows and execution risks. PW Consulting’s latest market study—anchored on a 2025 base year and a multi-year forecast through 2032—maps the commercial terrain you need to prioritize: the total market grew from the low hundreds of millions in 2020 to approximately USD 372.0 Million in 2025 and is projected to exceed USD 686 Million by 2032 at a compound annual growth rate (CAGR) of roughly 9.1%. These headline dynamics frame both the scale of the prize and the urgency of tactical moves in 2026.
Natural Astaxanthin Market
Why this report matters in 2026
-
Clear growth trajectory. The sector is beyond exploratory growth: the historical trend through 2025 demonstrates durable demand drivers (human nutraceuticals, aquaculture feed enhancement, and cosmetics premiumization), while our 2026–2032 forecast quantifies expansion paths under multiple uptake scenarios. Executives who treat 2026 as a pivot year—where capacity planning, pricing strategy, and regulatory positioning must be decisively set—will materially influence their competitive positioning for the rest of the decade.
Natural Astaxanthin Market -
Supply-side constraints matter. Upstream production remains a potential choke point: commercial Haematococcus pluvialis–derived powder is the primary feedstock, and global commercial production volumes are limited relative to demand (industry estimates point to annual production on the order of several hundred to one thousand metric tons). That scarcity, combined with technical differences in cultivation (open ponds vs. closed photobioreactors), creates meaningful margin dispersion and time-to-market advantages for vertically integrated players.
Natural Astaxanthin Market -
Regulatory inflection points dictate commercial scope. Recent regulatory developments—most notably regional food-safety opinions and novel-food dossiers submitted by leading producers—are re-shaping permitted end-uses and product formats. For 2026 planning, companies must model scenarios where certain uses remain limited to dietary supplements or require additional authorisations, affecting addressable demand by application.
What the report delivers (practical, decision-ready content)
-
Executive dashboard: concise KPIs and sensitivity scenarios built around our base-case CAGR of ~9.1%, with upside and downside pathways tied to regulatory outcomes and raw-material availability.
-
Supply-chain heatmap: supplier tiers, technical risk profiles (contamination, production variability), and near-term capacity catalysts—presented as action items for procurement and finance teams to secure continuity and manage cost escalation.
-
Commercial playbooks: segmented go-to-market options for B2B and B2C channels, premiumization levers for nutraceutical and cosmetic claims, and pricing elasticity guides—designed for product, marketing, and sales leadership to turn market growth into captured revenue and margin.
-
Regulatory risk matrix: jurisdictional scenarios, timing assumptions for novel-food and feed-authorisation processes, and compliance checklists that counsel legal and R&D investments.
-
M&A and partnership pipeline: an evidence-based shortlist of bolt-on capabilities, tolling partners, and vertical integration targets—ranked by strategic fit, time-to-value, and regulatory exposure.
Competitive landscape — what incumbents’ moves mean for your strategy
The natural astaxanthin value chain is populated by a small number of specialized producers that differ on technology, scale, and go-to-market orientation. The companies we assess combine legacy capability with recent strategic moves that reveal their chosen levers for growth. Below are the strategic implications drawn from competitor profiles and recent developments—sufficiently detailed to inform positioning, while reserving proprietary segment-level metrics for the full report.
-
AstaReal Inc. (Sweden) — AstaReal’s long-term focus on Haematococcus pluvialis cultivation and their contributions to pharmacopeial standards provide them with high credibility in premium nutraceutical and clinical-grade formulations. Their participation in novel-food dossiers signals a strategy of expanding authorized applications; for competitors, this is a reminder that regulatory engagement can create durable commercial advantages.
-
Cyanotech Corporation (United States) — Cyanotech’s open-pond model and established brand for Hawaiian astaxanthin have produced recent margin improvements as scale and throughput rise. This underlines two actionable lessons: (1) operational optimization can rapidly translate into per-unit cost advantages; and (2) location and branding matter to downstream customers seeking provenance-based claims.
-
Algatechnologies Ltd. (Israel) — The introduction of diversified, all-natural extract concentrations tailored for softgel and specialty formats highlights product-line expansion as a route to capture adjacent segments. Product innovation into format-specific deliverables allows premium price capture without necessarily requiring new feedstock volumes.
-
Beijing Gingko Group (BGG) (China) — Recent capacity expansion and investment in R&D infrastructure demonstrate a scale-and-integrate play. For global buyers, larger-scale producers can offer reliable supply and competitive pricing but also raise concentration risks—creating negotiating pressure for buyers unless they diversify supply sources.
-
Algalif Iceland, Fuji Chemical, Divis Laboratories — Each brings a distinct capability: closed-system sustainability and premium positioning (Algalif), formulation and formulation-services expertise (Fuji), and large-scale API and ingredient manufacturing discipline (Divis). A robust competitive strategy will evaluate partnerships that combine formulation know-how, scale manufacturing, and geographic distribution.
Regulatory and market-access dynamics to model in 2026
-
EU constraints and implications: recent regional opinions have clarified permitted scopes for certain algal preparations used outside of food supplements. These determinations materially affect feed and food ingredient strategies and should be modeled as scenario levers when sizing addressable demand in 2026 planning cycles.
-
Novel food filings: leading firms have progressed submissions that, if approved, could expand permissible product forms and broaden shelf-space opportunities. Companies that actively manage regulatory dossiers (including investment in human safety data and manufacturing controls) can shorten commercial timelines for new formats.
-
Upstream quality and quantity risk: constrained upstream availability of Haematococcus-derived powder means that buyers face either price volatility or the need to secure capacity via long-term offtakes or joint ventures. Strategic purchasers should evaluate tolling arrangements and backward integration where margin and continuity dictate.
Five pragmatic strategic moves for 2026
-
Secure supply now, hedge later: prioritize contractual arrangements (multi-year offtake, tolling, or equity-linked partnerships) to lock in access. Where immediate capacity is unavailable, short-term tolling agreements or formulation outsourcing can sustain product launches without large CAPEX.
-
Differentiate through formulation and claims: invest in clinically supported positioning and format engineering (water-dispersible systems, oleoresin-based formulations) to avoid competing solely on raw-material price.
-
Engage regulators proactively: allocate resources to dossier preparation and post-market surveillance to accelerate approvals in priority markets; early engagement is a competitive moat for applications that remain constrained.
-
Optimize cost-to-serve: map the full cost stack from biomass cultivation to finished dosage formats, and target 3–5 high-impact levers (yield improvements, extraction efficiency, formulation consolidation, logistics rationalization).
-
Use M&A selectively: target capabilities that shorten time to market (formulation specialists, regional tollers), or add production flexibility (photobioreactor capacity), rather than pursuing only scale-driven purchases.
Next steps: how to use the full PW Consulting study
This article highlights the strategic contours you must account for in 2026 planning. The complete PW Consulting Natural Astaxanthin Market report contains the segment-level demand matrices, regional forecasts, price curve modelling, supplier scorecards, and an executable 90-day action plan that operational teams can deploy. We intentionally limit disclosure here to maintain the commercial utility of our proprietary segmentation and confidential benchmarking—access to the full dataset and decision tools will enable teams to convert the 2026 market momentum into defensible market share and margin capture.
Contact PW Consulting to obtain the full study and a tailored briefing that maps our findings to your portfolio and investment roadmap for 2026–2028.
For detailed analysis of this topic, please visit the official page: Natural Astaxanthin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
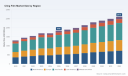
Cling Film Market — Strategic Outlook for 2026 Decision-Makers
As companies re-evaluate portfolios and supply chains in 2026, understanding the cling film market is no longer a niche operational concern — it is a strategic vector that touches procurement, sustainability roadmaps, product innovation, and commercial positioning. PW Consulting’s latest market study (base year 2025) synthesizes five years of historical performance (2020–2025) and presents a scenario-driven forecast for 2026–2032. The global market, estimated at USD 1,840 Million in 2025, has grown from roughly USD 1,300 Million in 2020 and is projected to reach about USD 2,610 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.2% over the forecast period. This preview highlights the study’s strategic value for corporate leadership while preserving the granular segmentation and line-item data that our clients rely on for transactions and tactical plans.
Cling Film Market
Why this report matters for 2026 strategic decisions
-
From procurement to P&L: Cling film is a commodity that hides complexity. Its cost base ties directly into hydrocarbon feedstock cycles, converter capacity, and regulatory shifts. In 2026, firms that align procurement strategies with a forward-looking demand model will secure margin stability and negotiation leverage with suppliers and converters.
Cling Film Market -
Product and channel differentiation: The market’s steady growth trajectory creates space for premiumization — higher-performance films, dispenser systems, and value-added cutterbox formats aimed at commercial foodservice, processors, and healthcare. Our analysis shows a clear premiumization runway, but execution requires data on channel elasticity and pricing thresholds (available in the full report).
Cling Film Market -
Sustainability is table stakes: Regulators and major retail buyers increasingly demand recyclable or recycled-content cling solutions. The study evaluates material substitution pathways, recyclability constraints, and lifecycle trade-offs that decision-makers must weigh when signing multi-year supply contracts or authorizing capital investments in recycling or sorghum-based alternatives.
-
Fragmented supplier landscape — opportunity for consolidation: Despite the presence of large multinationals, market concentration remains low (CR3 at ~20%; CR5 at ~25%), indicating fragmentation and local-market advantages for regional players. For acquisitive strategists, this fragmentation implies abundant mid-market targets and the potential to create scale advantages in distribution and converting.
-
Operational resilience: In a world of intermittent feedstock shocks, flexible manufacturing footprints matter. The forecast to 2032 highlights where capacity tightness may emerge and where lead-time risk will affect service-sensitive end users such as foodservice and healthcare distributors.
What PW Consulting’s report delivers — practical, transaction-ready outputs
-
Verified market sizing and trend decomposition. We reconcile top‑down macro drivers (raw material indices, foodservice demand, healthcare procurement trends) with bottom‑up manufacturer intelligence to produce a defensible market model for 2020–2032.
-
Scenario analysis and stress testing. Three demand and pricing scenarios are modeled, integrating feedstock price volatility, regulatory shifts (single-use plastics policies), and material innovation adoption curves. Each scenario includes implications for revenue, margin, and working capital.
-
Supply chain and cost-to-serve mapping. Detailed supplier maps, converter networks, and logistics choke-point analysis enable procurement teams to prioritize dual-sourcing, nearshoring, or inventory strategies by risk profile.
-
Buyer and channel playbooks. Actionable guidance for positioning products across retail, foodservice, industrial, and healthcare channels — including suggested SKU architectures, dispenser solution strategies, and pricing frameworks.
-
Regulatory and sustainability toolkits. Lifecycle assessment summaries, end‑of‑life pathways, and a comparative matrix of recycled-content options empower sustainability teams to craft credible claims and procurement specifications.
-
Deal flow support and valuation priors. For M&A teams, we provide target screening criteria, a shortlist of high-potential acquisition archetypes, and valuation priors calibrated to margin profiles and growth prospects in the cling film value chain.
Competitive landscape — strategic implications from incumbent profiles
The market is populated by well-known consumer brands and specialized converters; each player brings a distinct mix of distribution reach, product portfolio, and channel focus. Below are strategic readouts for the key companies profiled in our study. These are intended to guide decision-makers in negotiating partnerships, structuring deals, and anticipating competitive moves in 2026.
-
Berry Global Inc. (Evansville, Indiana) — Strengths: global production and distribution footprint, strong presence in foodservice and healthcare channels, and a portfolio that includes professional-grade cling solutions. Strategic implication: Berry is positioned to win large institutional contracts and to offer integrated packaging systems, making them a preferred partner for buyers seeking single-vendor simplification. For challengers, differentiation must focus on service agility or localized sustainability credentials.
-
Amcor plc (Zurich, Switzerland) — Strengths: recognized foodservice performance brands and scale in flexible packaging. Strategic implication: Amcor can leverage R&D and design capabilities to accelerate premium and recyclable offerings. Counterstrategies for incumbents include tightening converter partnerships in target geographies and fast-tracking eco‑design pilots that prove cost parity.
-
The Glad Products Company (Oakland, California) — Strengths: strong household brand recognition and retail penetration. Strategic implication: Glad’s consumer brand equity provides leverage for new product introductions and private-label initiatives. Competitors should anticipate promotional cycles and align trade terms accordingly.
-
Polyvinyl Films, Inc. (Sutton, Massachusetts) — Strengths: specialty polyvinyl-based films with premium mechanical properties. Strategic implication: Technical superiority in cling, stretch, and cold performance opens doors in food processing and institutional catering where performance justifies price premiums. Buyers in these segments prioritize performance over commodity pricing, creating margin insulation for suppliers.
-
Anchor Packaging Inc. (St. Louis, Missouri) — Strengths: cutterbox safety features and product variants for foodservice and processors. Strategic implication: Product ergonomics and safety are differentiators in professional kitchens; suppliers that bundle dispenser systems and service support can capture share even in mature channels.
-
Wrapex Limited (United Kingdom) — Strengths: eco-focused product lines and dispensing systems tailored to professional catering. Strategic implication: European regulatory pressure and foodservice sustainability commitments create a favorable environment for differentiated eco-products. Replication of these go-to-market models in other regions is an option for ambitious regional players.
Key strategic moves for 2026 — priorities by horizon
-
Immediate (0–12 months): lock in raw-material hedges for critical months, implement dual-sourcing for mission‑critical SKUs, and audit current supplier sustainability claims. Negotiate short-term supply agreements with contractual flexibility for recycled-content switches as validated alternatives become available.
-
Near term (12–36 months): pilot recyclable and recycled-content cling solutions in selected channels, invest in converter partnerships to co-develop dispenser systems, and rationalize SKU portfolios to improve production efficiency and reduce obsolescence.
-
Strategic (36+ months): consider targeted M&A to acquire converter capacity or proprietary film technologies, evaluate capex for localizing rollstock production to reduce logistics lead times, and build closed-loop propositions with retail or foodservice partners.
Decision levers and KPIs to monitor in 2026
-
Cost per linear meter and margin per SKU — to spot erosion early when feedstock volatility spikes.
-
Conversion yield and scrap rates at converters — critical for negotiating unit-based pricing and for evaluating capital investments in higher-efficiency lines.
-
Adoption rates for recyclable/recycled-content SKUs by channel partners and HS code impacts from evolving regulation.
-
Service-level metrics and lead time variability by region — important for foodservice and healthcare customers where stockouts are costly.
What we are intentionally withholding in this preview
To preserve the commercial integrity and tactical value of the study for subscribers, this introduction does not disclose the detailed regional, type, and application-level line-item breakouts that underpin the model. Readers seeking the granular splits — including the full regional demand matrix, application-level demand elasticities, and SKU-level pricing priors — should consult the full report. Those datasets are the basis for our SKU-level playbooks, acquisition screens, and pricing sensitivity analyses, and they are provided with interactive spreadsheets and scenario tools in the subscriber package.
How PW Consulting can help
For leadership teams preparing 2026 budgets, negotiating long-term supply contracts, or building sustainability-compliant product lines, PW Consulting offers tailored advisory services based on this study: bespoke supply risk assessments, M&A target screening, procurement tender support, and operational improvement programs for converters. Our work combines market-grade modeling with on-the-ground converter and brand interviews, delivering recommendations you can operationalize within quarter timelines.
To access the full dataset, strategic appendices, and scenario workbooks, visit PW Consulting’s Cling Film Market report page or contact our industry team for a briefing. The macro trajectory is clear — steady demand, pockets of premiumization, and sustainability-led disruption — but the competitive and geographies-by-application contours in 2026 will decide who captures the upside. Use this study to align your 2026 decisions with an evidence-based roadmap that balances growth, resilience, and regulatory readiness.
For detailed analysis of this topic, please visit the official page: Cling Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tea Tree Oil Market Poised for 10.6% CAGR Through 2032
By pmarketresearch, 2026-07-22
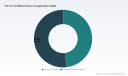
Tea Tree Oil Market — 2026 Strategic Outlook and Executive Primer
As PW Consulting’s lead industry analyst, I present a focused strategic primer that frames our full Tea Tree Oil Market study for executives making investment, sourcing, and product strategy decisions in 2026. Anchored on a 2025 base year and incorporating five years of historical trend analysis (2020–2025), our modelling shows the global market has entered a sustained growth phase, expanding at a compound annual growth rate of 10.6% into the 2026–2032 forecast window. By our base year the industry already approached the mid‑hundreds of millions of USD in annual revenues, and our scenario work projects this to roughly double by the end of the forecast horizon — a trajectory that materially changes the commercial calculus for manufacturers, branded consumer goods companies, and ingredient distributors alike.
Tea Tree Oil Market
Why this study matters for 2026 decision‑making
- Timing: 2026 is a pivotal year in which regulatory clarifications, upstream capacity additions and accelerating consumer preference for natural/clean‑label products converge — creating both windows of opportunity and asymmetric risks.
- Actionability: The full report translates market sizing into concrete commercial playbooks — procurement hedges, supplier qualification scorecards, and go‑to‑market roadmaps — so decisions made this year can capture market share and limit downside exposure.
- Signal vs. noise: Our analysis separates transient headlines from persistent structural change (e.g., certification premiums, grade migration toward pharmaceutical and high‑purity contexts), enabling capital allocation that is robust to alternative regulatory outcomes.
Market trajectory and strategic implications
Tea tree oil is transitioning from a niche botanical into a core functional ingredient across personal care, household hygiene and certain therapeutic adjacencies. Growth is underpinned by three structural forces: rising consumer demand for natural antimicrobials and botanical actives; upstream investments in plantation and distillation capacity that expand reliable supply of high‑purity grades; and premiumization, where certified organic, pharmaceutical‑grade and ethically produced streams capture value beyond commodity pricing.
Tea Tree Oil Market
Our central case incorporates an annualized growth rate of roughly 10.6% across the 2026–2032 horizon. The consequence for 2026: procurement teams should assume tighter competition for premium volumes, R&D leaders should accelerate formulation work that leverages tea tree oil’s efficacy attributes, and M&A teams should prioritize targets that offer vertical control (plantation + distillation + certification) or differentiated distribution reach.
Tea Tree Oil Market
Supply‑side developments to watch
- Major upstream investments: Several key producers have recently expanded plantations and distillation capacity. These projects improve yield and high‑purity extraction throughput but take time to fully de‑risk — creating near‑term supply‑quality arbitrage opportunities for buyers who can qualify multiple origins.
- Certification and differentiation: Organic, Fair Trade and regenerative certifications are becoming commercial differentiators. Suppliers that can pair certified sourcing with consistent analytical quality are commanding premium placement in formulations and retail assortments.
- Vertical strategies by large essential‑oil brands: Well‑capitalized aromatherapy and wellness companies are integrating extraction capabilities and launching product lines, intensifying competition in branded channels while also acting as preferred direct purchasers for certain suppliers.
Competitive landscape: observed dynamics
The market structure blends specialist grower‑distillers with global branded essential‑oil suppliers. From our qualitative benchmarking and recent-event tracking, we observe three archetypes:
- Integrated plantation‑to‑refinery growers building scale and certifications to supply pharmaceutical and premium personal care markets.
- Large essential‑oil brands extending upstream to secure preferred volumes for retail and direct channels.
- Community and sustainability‑led producers that differentiate via organic, fair trade and regenerative credentials and command access to premium natural product supply chains.
Recent company moves exemplify these archetypes and the practical consequences for buyers and investors. Examples include capacity expansions and upgraded distillation facilities by established growers, plantation investments by large extract specialists, supply‑chain export expansions, production optimization programs at community producers, and product launches and facility additions by major essential‑oil brands to secure upstream supply. These developments reduce some historical supply bottlenecks but also accelerate competition for certified and pharmaceutical‑grade tonnages.
Regulatory inflection points and risk calibration
Regulation is the single largest non‑market variable influencing strategic choices in 2026. Notably, scientific panel activity and trade policy discussions in 2025 have created a bifurcated risk landscape:
- Positive clarifications: A recent safety opinion has affirmed permitted uses of tea tree oil in certain cosmetic contexts subject to strict limits. That opinion supports formulators and retailers by reducing regulatory uncertainty for defined product categories.
- Ongoing classification debates: Simultaneously, trade notices and public consultations on hazard classification create potential for import controls and compliance cost increases in some jurisdictions. These matters remain unresolved and require active monitoring and contingency planning.
Strategically, corporates should adopt a two‑track compliance posture in 2026: optimize existing product portfolios to conform with the clarified safe‑use limits, while provisioning for tighter classification scenarios through diversified sourcing, substitution pathways and updated labelling/packaging workflows.
What the full PW Consulting report delivers (practical content)
Our published study is intentionally operational. It avoids vague forecasts and instead provides the tools and datasets that commercial teams use to act quickly and confidently:
- Market model with scenario layers: base, upside and constrained regulatory scenarios, each with demand drivers and sensitivity tables.
- Supply‑chain maps and origin risk scoring: farmer cooperative profiles, distillation capacities, certification pipelines and time‑to‑scale estimates.
- Regulatory matrix and compliance playbook: jurisdictional summaries, label/packaging checklists, and investment triggers tied to plausible policy outcomes.
- Competitive intelligence packets: strategic profiles of leading integrated growers, branded essential‑oil companies and community producers, plus recent capital expenditure and product launch timelines.
- Commercial toolkits: supplier selection scorecards, contract templates for volume guarantees, premium‑certification ROI calculators, and GTM playbooks for launching tea tree‑enabled products.
- M&A and sourcing filters: target screening criteria, valuation multiples benchmarked by supply‑chain position, and integration risk checklists.
To preserve commercial advantage for purchasers of the full study, we deliberately withhold the granular segment tables, per‑region revenue splits, application‑level unit economics and supplier‑level pricing curves from this executive primer; those live datasets are provided in the full report and accompanying spreadsheets.
Top strategic moves for executives in 2026
- Secure a two‑tier supply program: establish long‑term offtake agreements for premium, certified volumes while maintaining a diverse spot purchasing capability for commodity grades.
- Prioritize formulation work now: reformulate to the confirmed safety limits and develop premium SKUs that emphasize certified origin and efficacy claims.
- Invest in supplier partnerships: co‑fund traceability and agronomy improvements with select growers to reduce quality variability and create preferred access to scale‑up volumes.
- Build regulatory scenario triggers into capital allocation: set investment gates tied to clear regulatory outcomes and specify contingency budgets for compliance-driven labelling or reformulation costs.
- Monetize sustainability credentials: leverage organic, Fair Trade or regenerative claims in pricing strategies and retail positioning where certification premiums are accepted by end consumers.
- Use M&A tactically: pursue bolt‑on assets that either deepen vertical integration (plantation + distillation) or extend distribution into strategic channels (pharmaceutical or large personal‑care OEM relationships).
How PW Consulting supports execution
We work alongside clients from strategy through implementation. Typical engagements we recommend for 2026 include:
- Procurement optimization and supplier negotiations supported by our price forecasting and contract templates.
- Due diligence for acquisition targets, including technical verification of distillation assets and certification audits.
- Regulatory risk workshops and development of compliance playbooks aligned to specific product portfolios and markets.
- Commercial acceleration programs — from concept to launch — that integrate positioning, claims strategy, and retailer engagement plans.
For executives ready to act, the next step is simple: obtain the full report and the underlying datasets. The complete package contains the proprietary regional and application breakdowns, supplier scorecards, detailed pricing curves and the scenario‑level model that directly informs procurement volumes, CAPEX sizing and M&A valuation. These are the elements we intentionally withhold here to preserve the strategic value of the research.
Concluding perspective
Tea tree oil has evolved from an aromatic botanical into a strategically significant ingredient across multiple consumer and health markets. The 2026 moment is defined by rapidly improving supply infrastructure, meaningful regulatory clarifications and an expanding premium market that values certified, high‑purity streams. Companies that align sourcing, R&D and regulatory strategy in a coordinated manner will capture outsized returns; those that treat the market as a simple commodity risk being outflanked by vertically integrated suppliers and premium‑focused competitors.
PW Consulting’s full Tea Tree Oil Market study provides the granular intelligence and operational toolkits to translate these strategic imperatives into executable plans. For access to the full dataset, supplier scorecards and scenario models that underpin our recommendations, please visit the report landing page or contact our market team directly.
For detailed analysis of this topic, please visit the official page: Tea Tree Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
EPDM Market Poised at USD 5,000M in 2025; 5% CAGR Forecast (2026–2032) — PW Consulting
By pmarketresearch, 2026-07-22
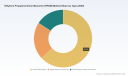
EPDM Market 2026: Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our full Ethylene Propylene Diene Monomer (EPDM) Market research. This briefing synthesizes seven-year historical context (2020–2025), a robust forecast window (2026–2032), and the practical intelligence executives need to act in 2026. We expose the high-level trajectories, competitive dynamics, regulatory inflection points, and the operational playbook contained in the full report — while intentionally withholding the granular segmentation tables to compel direct access to our source materials for transaction-level planning.
Ethylene Propylene Diene Monomer (EPDM) Market
Market Trajectory: Macro Facts You Must Act On
EPDM has moved from a cyclical commodity into a strategic industrial polymer underpinning automotive, construction, and electrical applications. Using 2025 as our base year, the global EPDM market stands at approximately USD 5,000 million. Our modeling — calibrated on primary supply-side interviews, plant-level capacity audits, and price/pass-through elasticity analysis — projects growth through 2032 at a compound annual growth rate (CAGR) of roughly 5.0% across the 2026–2032 forecast window, taking the market to just over USD 7 billion by the end of the period.
Ethylene Propylene Diene Monomer (EPDM) Market
That mid-single-digit CAGR masks important structural shifts: demand is becoming more concentrated around performance formulations (driven by electric-vehicle sealing, lightweighting, and higher thermal/corrosion resistance needs), while regulatory and circularity pressures are accelerating product re-engineering. On the supply side, a moderate level of concentration persists: the top three suppliers account for less than half of global capacity, and the top five near the mid‑50s percentile — a market structure that supports regional price differentiation and recurring opportunity for value capture through technology, scale, or customer intimacy.
Ethylene Propylene Diene Monomer (EPDM) Market
Why This Report Matters for 2026 Strategic Decisions
- Capex vs. Contracting Choices: Producers and converters must decide whether to expand integrated EPDM capacity, pursue tolling arrangements, or secure off-take through long-duration contracts. Our cash-flow scenarios and plant-level breakevens illuminate the trade-offs under multiple ethylene feedstock price trajectories.
- Product Portfolio Prioritization: Solid EPDM grades, tailor-made compound formulations, and engineered sheets/profiles serve distinct margin curves and go-to-market motions. The research provides a prioritized roadmap to reallocate R&D and commercial investments for the highest ROI.
- Supply Chain Resilience: With feedstock concentration and regulatory uncertainty, procurement teams need dynamic hedging strategies and dual-sourcing blueprints — all of which are actionable in the report’s procurement playbook.
- Commercial and M&A Playbooks: Given the market’s moderate concentration, there are repeatable M&A archetypes (capability buy, footprint buy, customer-accretion buy). We map valuation multipliers and integration risks across each archetype.
What the Full Report Contains — An Operational Toolkit
- Proprietary market-sizing model (2020–2032) with scenario toggles for feedstock shocks and accelerated electrification.
- Segment-level demand drivers by type (solid EPDM, compounds, sheets/profiles) and end-market use cases (automotive, building & construction, wires & cables), with forecasted volumes and sensitivity matrices. (Note: granular numeric splits are reserved for the full report.)
- Price and margin modelling including feedstock pass-through, contract vs spot dynamics, and short‑cycle arbitrage opportunity windows.
- Cost curve and breakeven analysis for greenfield, brownfield restart, and tolling models — at plant and regional levels.
- Competitive capability maps and vendor scorecards covering technology, geographic footprint, logistics, and commercial sophistication.
- Regulatory and ESG impact assessment (packaging directives, chemical taxation scenarios, end-of-life mandates) with policy-driven demand adjustments.
- M&A and partnership heatmap, including screening criteria to identify accretive targets and integration scorecards.
- Client-ready slides, negotiation checklists, and a one-day executive workshop module to convert insights into 90‑day action plans.
Competitive Landscape — Who Matters and Why
The EPDM competitive set blends global integrated majors, regional specialists, and national champions. Each player brings a distinct strategic posture:
- Integrated majors (examples include firms known for branded EPDM elastomers) leverage global feedstock integration, licensing networks, and well-established customer relationships in automotive and industrial sealing. Their strengths are scale, R&D depth, and multi-market distribution channels.
- Specialized elastomer manufacturers focus on formulation expertise and just-in-time supply for compounders and converters. Their advantage is product differentiation and faster customization cycles — critical when OEMs demand tailored performance or recycled content.
- Regional players and state-backed suppliers often compete on cost and proximity to local demand centers; they are influential in fast-growing regional segments where logistics and local standards drive procurement decisions.
Recent industry moves illustrate the tactical shape of competition. A leading integrated chemicals company announced in mid‑2025 a capacity restart in the United States, reflecting a broader industry pattern: measured volume additions targeted at tightening margins and securing parity in service for North American customers. Such moves are indicative of the playbook we observe — incremental capacity restarts and targeted brownfield investments to capture near-term demand growth while preserving flexibility for longer-term strategic pivots.
Regulatory and ESG Drivers — Non-Negotiable for 2026
Two regulatory developments deserve immediate board-level attention. First, a petition has been filed in the United States proposing that EPDM fall under a broader Superfund tax regime for certain chemical substances. If enacted, this could change cost structures for domestic producers and tilt sourcing calculus for multinational buyers. Second, the European Union’s updated packaging directive — mandating 30% recycled content in plastic packaging by 2030 — is already exerting influence beyond packaging. Automotive and industrial specifiers are extending recycled-content and circularity requirements into elastomer components, pressuring EPDM formulations and supply chains.
Our report quantifies the P&L impact across several policy adoption scenarios and provides tactical mitigation options: accelerated circular product development, supplier cooperation agreements for reclaimed rubber streams, and contract clauses to share regulatory cost shifts.
Practical Strategic Moves for 2026
- Lock strategic optionality on capacity: Prefer staged brownfield restarts and modular expansions over large greenfield commitments until recycled-content mandates and feedstock taxation risks crystallize.
- Prioritize high-value formulations: Invest in high-margin EPDM compounds tailored for EV sealing and thermal-management to offset volume-driven commoditization elsewhere.
- Formalize circular supply pilots: Partner with converters and OEMs to develop validated recycled-EPDM streams and secure first-mover commercial terms.
- Negotiate flexible offtake: Use hybrid contracts (minimum commitment + spot flex) to balance working capital and exposure to price spikes tied to ethylene feedstock moves.
- Prepare for tax and compliance shocks: Build scenario-based cashflow buffers and contractual pass-through mechanics to absorb or reallocate newly proposed Superfund-type taxes.
Reading the Competitive Signals — Where Winners Differentiate
Winners will be those who combine three capabilities: technological differentiation (specialty grades and recycled-content formulas), commercial agility (tiered contracts and near-customer inventory models), and regulatory foresight (proactive compliance pathways and circular partnerships). The market concentration metrics indicate that, while scale matters, niche specialization and customer intimacy remain decisive competitive levers. For corporates considering M&A, targets that offer either technology differentiation or regional access to high-growth end markets should be prioritized.
How to Use This Preview
This document is a directional briefing designed to inform Board deliberations and 2026 planning cycles. The full PW Consulting EPDM Market report contains the complete data tables, granular regional and application splits, supplier scorecards, and downloadable model files that underpin the scenarios summarized here. We intentionally omit those line-item segment figures in this preview to preserve commercial exclusivity and to encourage direct engagement with our analysts for bespoke modeling and transaction support.
For companies seeking to convert insight into action, we offer three immediate engagements: a tailored 48‑hour market scan to stress-test a specific investment thesis, a two‑week commercial diligence package for M&A targets, and a one-day executive workshop to build a 90‑day roadmap. Contact PW Consulting to arrange access to the full report and to commission any bespoke analysis needed to operationalize these findings in 2026.
For detailed analysis of this topic, please visit the official page: Ethylene Propylene Diene Monomer (EPDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Air Beds Market to hit USD 575.51M by 2032 with 7.9% CAGR
By pmarketresearch, 2026-07-22
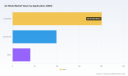
Air Beds Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present this executive introduction to our latest Air Beds Market study — a practitioner-focused intelligence product designed specifically to influence and de-risk executive choices in 2026. The sector is at an inflection point: steady demand fundamentals meet shifting end‑user expectations, modular manufacturing advances, and a more concentrated competitive set. This briefing highlights the study’s strategic value, synthesizes the macro trajectory, and previews the practical deliverables that will support commercial, product and M&A decisions next year. Per our “trailer” principle, we demonstrate analytical depth while withholding detailed segment-level numbers to drive interested readers to the full report.
Air Beds Market
Why this research matters for 2026 planning
- Timing: 2026 is the first forecast year in our model and will be the operational planning horizon for most companies completing 2025 reviews and setting 2026 budgets. Tactical choices made now—capex for pump integration, channel investments, SKU rationalization—will determine who captures the next wave of growth.
- Market momentum: The total air beds market expanded consistently through the 2020–2025 historical window and enters the forecast period with positive momentum. Our base-year market sizing (2025) provides the common reference for scenario work and target setting across commercial functions.
- Competitive levers are shifting: Product differentiation has moved from simple materials and inflation convenience to integrated systems (pumps, smart controls), experiences (glamping-ready durability), and channel-adapted SKUs (vehicle- and truck-bed solutions). These are precisely the levers analyzed in the full report to inform where to invest for 2026.
Market snapshot: scale, pace and concentration
Our comprehensive market model establishes an agreed industry baseline: the market grew from the lower hundreds of millions in 2020 to a 2025 base of USD 340.0 Million (base year = 2025). Under our central-case assumptions—reflecting demand recovery, premiumization and incremental penetration in adjacent applications—the market is projected to expand to USD 575.51 Million by 2032, representing a compound annual growth rate (CAGR) of 7.9% across the 2026–2032 forecast window.
Air Beds Market
Two additional structural metrics drive competitive strategy. First, market concentration is material: the three largest providers control a meaningful majority share, and the top five approach three‑quarters of the market. Second, growth is not evenly distributed—value accretes to product features and channel footprints that unlock higher ASPs or recurring purchase streams. The combined implication for suppliers and investors in 2026 is clear: scale confers pricing elasticity and distribution advantages, but targeted product or channel bets can deliver outsized returns for agile players.
Air Beds Market
Competitive landscape: capabilities that matter
Our competitive review emphasizes capabilities and business models rather than headline market shares (those finer splits are retained in the full report). The current field can be usefully profiled by capability vectors:
- Integrated consumer systems: Brands that combine advanced internal pumps, easy-set controls and fiber or coil support systems are capturing guest‑use and home comfort segments. They benefit from simple value propositions (faster setup, stable pressure, better sleep) that justify premium pricing.
- Outdoor and experiential specialists: Suppliers focusing on durability, base construction and outdoor fabrics target glamping and camping channels. Their growth is tied to outdoor leisure trends and OEM partnerships with camping-gear distributors.
- Vehicle- and truck-specific solutions: A narrow but strategic niche where product fit and OEM relationships matter—these providers extract higher margins through bespoke designs and aftermarket channels.
Representative firms in our competitive analysis illustrate these dynamics:
- Intex Recreation Corp. — consumer-oriented with an emphasis on fiber-tech construction and pump integration, enabling broad retail distribution and strong brand recognition in portable mattresses.
- Coleman — leveraging outdoor and camping heritage to offer raised air mattresses and airbed cots that prioritize structural support and leak resistance for field use.
- Zempire — a specialist tailing the premium glamping trend through durable bases and stretch fabrics, positioning for channel partnerships in upscale outdoor hospitality and enthusiast retail.
- Sound Asleep Products — differentiating through internal ComfortCoil technology and eco‑conscious materials, appealing to health- and environment‑focused consumers.
- King Koil Airbeds — targeting the luxury raised-bed guest and home market with enhanced coil systems and integrated pumps to capture premium dollar‑per‑unit segments.
- Pittman Outdoors — occupying the vehicle/utility niche with truck-bed‑specific inflatable solutions and aftermarket distribution strength.
Our scorecards evaluate these players across product breadth, channel reach, proprietary technology, and supply-chain resilience. The full report contains competitive heat maps and supplier strategies; this summary highlights that winning in 2026 will require either scale to support mass channels or narrow specialization with strong channel partnerships.
Key growth drivers and headwinds
- Premiumization of transient sleeping solutions: Consumers and businesses are willing to pay for improved comfort and convenience features—integrated pumps, multi-zone support and improved materials—driving ASP growth.
- Outdoor leisure and experiential consumption: Glamping and outdoor hospitality are creating higher-margin use cases for ruggedized, design-forward air beds.
- Channel evolution and direct commerce: E‑commerce allows niche players to reach segmented audiences profitably, while large retailers continue to demand SKU rationalization and predictable logistics.
- Manufacturing and material cost pressure: Input-cost volatility and the need for sustainable materials present both a margin headwind and an innovation opportunity.
- Regulatory and environmental expectations: Growing attention to PVC alternatives and recyclability affects sourcing and product claims—firms that credibly transition early can capture premium positioning.
Strategic plays for 2026 — practical recommendations
Based on the model and competitive mapping, the following strategic playbook is prioritized for executives building 2026 plans:
- Prioritize modular product platforms: Invest in pump and control modules that can be shared across SKUs to accelerate new feature rollouts and reduce per‑SKU R&D costs.
- Channel-led SKU rationalization: Align assortment to channel economics—streamline SKUs for mass retail while offering modular add-ons and premium bundles in direct channels.
- Partnerships over greenfield manufacturing: Where capital constraints exist, pursue co‑manufacturing or licensing for specialized outdoor or vehicle applications to access expertise and reduce time to market.
- Capture recurring revenue: Explore subscription or replacement parts/service plans (pumps, covers) that leverage installed base and extend customer lifetime value.
- Use M&A selectively: Target bolt-on acquisitions that fill capability gaps—smart pump electronics, specialty fabrics, or distribution footprints—rather than broad horizontal consolidation, unless scale is in doubt.
What the full PW Consulting report delivers
The complete study is designed as an operational tool for commercial and corporate strategy teams. Key deliverables include:
- Market sizing and a transparent methodology reconciled to public and proprietary datasets (historical 2020–2025 and forecast 2026–2032).
- Demand-driver models with scenario analysis (base, upside, downside) tied to macroeconomic assumptions and channel shifts.
- Price‑and‑volume forecasts and ASP trajectories by product family (presented in the full report; we withhold granular splits here to preserve subscriber value).
- Competitor scorecards, capability maps and go‑to‑market playbooks for both scale players and specialists.
- Supply‑chain heat maps, cost‑sensitivity analyses and sourcing risk assessments for critical inputs and manufacturing footprints.
- Acquisition target shortlists and integration checklists calibrated to corporate capabilities and financial thresholds.
- Actionable 90‑, 180‑ and 360‑day implementation plans tailored for marketing, product development and channel teams.
We deliberately do not reproduce detailed regional, type or application splits in this executive preview. Those granular segmentations—derived from our reconciled data and essential for precise revenue planning and territory-level investments—are available in the full report and interactive models.
How to apply this intelligence in your 2026 playbook
- CEOs and corporate strategists: Use the report’s scenario outputs to set top‑line targets, capital allocation limits, and M&A screening criteria for 2026 initiatives.
- Product leaders: Apply the modular platform guidance and feature‑value maps to prioritize R&D and SKU rationalization in Q1 2026.
- Commercial heads: Align channel investments to the report’s go‑to‑market playbooks—accelerate direct channels for premium propositions and streamline mass-retail assortments.
- Investors and PE teams: Leverage our valuation overlays and acquisition shortlists to identify deals that offer immediate operational improvements or strategic scale.
Next steps
If your 2026 planning cycle requires a defensible market base, executable go‑to‑market steps, and a shortlist of capability-focused acquisitions, PW Consulting’s full Air Beds Market report and interactive model provide those deliverables with traceable assumptions and master data. The executive preview above outlines the high‑level implications and the analytic frames we use; the full report contains the actionable segment-level forecasts, competitor matrices, and financial templates required to translate strategy into results.
To access the complete report, interactive dataset and bespoke advisory options for scenario workshops and M&A diligence, please visit our report page or contact PW Consulting directly. Our team stands ready to align the analysis to your 2026 operating rhythm and to convert market insight into market advantage.
For detailed analysis of this topic, please visit the official page: Air Beds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com