

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Natural Astaxanthin Market Poised for 9.1% CAGR, Hits USD 372M in 2025

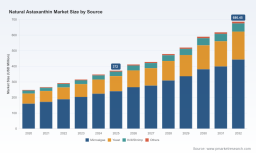
Natural Astaxanthin Market: Strategic Imperatives for 2026
Summary for decision-makers
As organizations shape their 2026 investment and commercial agendas, the natural astaxanthin market presents a distinct combination of steady expansion, concentrated supplier power, and evolving regulatory boundaries that together determine near-term opportunity windows and execution risks. PW Consulting’s latest market study—anchored on a 2025 base year and a multi-year forecast through 2032—maps the commercial terrain you need to prioritize: the total market grew from the low hundreds of millions in 2020 to approximately USD 372.0 Million in 2025 and is projected to exceed USD 686 Million by 2032 at a compound annual growth rate (CAGR) of roughly 9.1%. These headline dynamics frame both the scale of the prize and the urgency of tactical moves in 2026.
Natural Astaxanthin Market
Why this report matters in 2026
-
Clear growth trajectory. The sector is beyond exploratory growth: the historical trend through 2025 demonstrates durable demand drivers (human nutraceuticals, aquaculture feed enhancement, and cosmetics premiumization), while our 2026–2032 forecast quantifies expansion paths under multiple uptake scenarios. Executives who treat 2026 as a pivot year—where capacity planning, pricing strategy, and regulatory positioning must be decisively set—will materially influence their competitive positioning for the rest of the decade.
Natural Astaxanthin Market -
Supply-side constraints matter. Upstream production remains a potential choke point: commercial Haematococcus pluvialis–derived powder is the primary feedstock, and global commercial production volumes are limited relative to demand (industry estimates point to annual production on the order of several hundred to one thousand metric tons). That scarcity, combined with technical differences in cultivation (open ponds vs. closed photobioreactors), creates meaningful margin dispersion and time-to-market advantages for vertically integrated players.
Natural Astaxanthin Market -
Regulatory inflection points dictate commercial scope. Recent regulatory developments—most notably regional food-safety opinions and novel-food dossiers submitted by leading producers—are re-shaping permitted end-uses and product formats. For 2026 planning, companies must model scenarios where certain uses remain limited to dietary supplements or require additional authorisations, affecting addressable demand by application.
What the report delivers (practical, decision-ready content)
-
Executive dashboard: concise KPIs and sensitivity scenarios built around our base-case CAGR of ~9.1%, with upside and downside pathways tied to regulatory outcomes and raw-material availability.
-
Supply-chain heatmap: supplier tiers, technical risk profiles (contamination, production variability), and near-term capacity catalysts—presented as action items for procurement and finance teams to secure continuity and manage cost escalation.
-
Commercial playbooks: segmented go-to-market options for B2B and B2C channels, premiumization levers for nutraceutical and cosmetic claims, and pricing elasticity guides—designed for product, marketing, and sales leadership to turn market growth into captured revenue and margin.
-
Regulatory risk matrix: jurisdictional scenarios, timing assumptions for novel-food and feed-authorisation processes, and compliance checklists that counsel legal and R&D investments.
-
M&A and partnership pipeline: an evidence-based shortlist of bolt-on capabilities, tolling partners, and vertical integration targets—ranked by strategic fit, time-to-value, and regulatory exposure.
Competitive landscape — what incumbents’ moves mean for your strategy
The natural astaxanthin value chain is populated by a small number of specialized producers that differ on technology, scale, and go-to-market orientation. The companies we assess combine legacy capability with recent strategic moves that reveal their chosen levers for growth. Below are the strategic implications drawn from competitor profiles and recent developments—sufficiently detailed to inform positioning, while reserving proprietary segment-level metrics for the full report.
-
AstaReal Inc. (Sweden) — AstaReal’s long-term focus on Haematococcus pluvialis cultivation and their contributions to pharmacopeial standards provide them with high credibility in premium nutraceutical and clinical-grade formulations. Their participation in novel-food dossiers signals a strategy of expanding authorized applications; for competitors, this is a reminder that regulatory engagement can create durable commercial advantages.
-
Cyanotech Corporation (United States) — Cyanotech’s open-pond model and established brand for Hawaiian astaxanthin have produced recent margin improvements as scale and throughput rise. This underlines two actionable lessons: (1) operational optimization can rapidly translate into per-unit cost advantages; and (2) location and branding matter to downstream customers seeking provenance-based claims.
-
Algatechnologies Ltd. (Israel) — The introduction of diversified, all-natural extract concentrations tailored for softgel and specialty formats highlights product-line expansion as a route to capture adjacent segments. Product innovation into format-specific deliverables allows premium price capture without necessarily requiring new feedstock volumes.
-
Beijing Gingko Group (BGG) (China) — Recent capacity expansion and investment in R&D infrastructure demonstrate a scale-and-integrate play. For global buyers, larger-scale producers can offer reliable supply and competitive pricing but also raise concentration risks—creating negotiating pressure for buyers unless they diversify supply sources.
-
Algalif Iceland, Fuji Chemical, Divis Laboratories — Each brings a distinct capability: closed-system sustainability and premium positioning (Algalif), formulation and formulation-services expertise (Fuji), and large-scale API and ingredient manufacturing discipline (Divis). A robust competitive strategy will evaluate partnerships that combine formulation know-how, scale manufacturing, and geographic distribution.
Regulatory and market-access dynamics to model in 2026
-
EU constraints and implications: recent regional opinions have clarified permitted scopes for certain algal preparations used outside of food supplements. These determinations materially affect feed and food ingredient strategies and should be modeled as scenario levers when sizing addressable demand in 2026 planning cycles.
-
Novel food filings: leading firms have progressed submissions that, if approved, could expand permissible product forms and broaden shelf-space opportunities. Companies that actively manage regulatory dossiers (including investment in human safety data and manufacturing controls) can shorten commercial timelines for new formats.
-
Upstream quality and quantity risk: constrained upstream availability of Haematococcus-derived powder means that buyers face either price volatility or the need to secure capacity via long-term offtakes or joint ventures. Strategic purchasers should evaluate tolling arrangements and backward integration where margin and continuity dictate.
Five pragmatic strategic moves for 2026
-
Secure supply now, hedge later: prioritize contractual arrangements (multi-year offtake, tolling, or equity-linked partnerships) to lock in access. Where immediate capacity is unavailable, short-term tolling agreements or formulation outsourcing can sustain product launches without large CAPEX.
-
Differentiate through formulation and claims: invest in clinically supported positioning and format engineering (water-dispersible systems, oleoresin-based formulations) to avoid competing solely on raw-material price.
-
Engage regulators proactively: allocate resources to dossier preparation and post-market surveillance to accelerate approvals in priority markets; early engagement is a competitive moat for applications that remain constrained.
-
Optimize cost-to-serve: map the full cost stack from biomass cultivation to finished dosage formats, and target 3–5 high-impact levers (yield improvements, extraction efficiency, formulation consolidation, logistics rationalization).
-
Use M&A selectively: target capabilities that shorten time to market (formulation specialists, regional tollers), or add production flexibility (photobioreactor capacity), rather than pursuing only scale-driven purchases.
Next steps: how to use the full PW Consulting study
This article highlights the strategic contours you must account for in 2026 planning. The complete PW Consulting Natural Astaxanthin Market report contains the segment-level demand matrices, regional forecasts, price curve modelling, supplier scorecards, and an executable 90-day action plan that operational teams can deploy. We intentionally limit disclosure here to maintain the commercial utility of our proprietary segmentation and confidential benchmarking—access to the full dataset and decision tools will enable teams to convert the 2026 market momentum into defensible market share and margin capture.
Contact PW Consulting to obtain the full study and a tailored briefing that maps our findings to your portfolio and investment roadmap for 2026–2028.
For detailed analysis of this topic, please visit the official page: Natural Astaxanthin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com