

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cling Film Market Set to Grow at 5.2% CAGR

Cling Film Market — Strategic Outlook for 2026 Decision-Makers
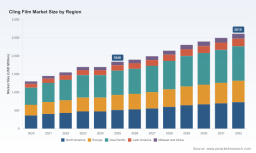
As companies re-evaluate portfolios and supply chains in 2026, understanding the cling film market is no longer a niche operational concern — it is a strategic vector that touches procurement, sustainability roadmaps, product innovation, and commercial positioning. PW Consulting’s latest market study (base year 2025) synthesizes five years of historical performance (2020–2025) and presents a scenario-driven forecast for 2026–2032. The global market, estimated at USD 1,840 Million in 2025, has grown from roughly USD 1,300 Million in 2020 and is projected to reach about USD 2,610 Million by 2032, reflecting a compound annual growth rate (CAGR) of 5.2% over the forecast period. This preview highlights the study’s strategic value for corporate leadership while preserving the granular segmentation and line-item data that our clients rely on for transactions and tactical plans.
Cling Film Market
Why this report matters for 2026 strategic decisions
-
From procurement to P&L: Cling film is a commodity that hides complexity. Its cost base ties directly into hydrocarbon feedstock cycles, converter capacity, and regulatory shifts. In 2026, firms that align procurement strategies with a forward-looking demand model will secure margin stability and negotiation leverage with suppliers and converters.
Cling Film Market -
Product and channel differentiation: The market’s steady growth trajectory creates space for premiumization — higher-performance films, dispenser systems, and value-added cutterbox formats aimed at commercial foodservice, processors, and healthcare. Our analysis shows a clear premiumization runway, but execution requires data on channel elasticity and pricing thresholds (available in the full report).
Cling Film Market -
Sustainability is table stakes: Regulators and major retail buyers increasingly demand recyclable or recycled-content cling solutions. The study evaluates material substitution pathways, recyclability constraints, and lifecycle trade-offs that decision-makers must weigh when signing multi-year supply contracts or authorizing capital investments in recycling or sorghum-based alternatives.
-
Fragmented supplier landscape — opportunity for consolidation: Despite the presence of large multinationals, market concentration remains low (CR3 at ~20%; CR5 at ~25%), indicating fragmentation and local-market advantages for regional players. For acquisitive strategists, this fragmentation implies abundant mid-market targets and the potential to create scale advantages in distribution and converting.
-
Operational resilience: In a world of intermittent feedstock shocks, flexible manufacturing footprints matter. The forecast to 2032 highlights where capacity tightness may emerge and where lead-time risk will affect service-sensitive end users such as foodservice and healthcare distributors.
What PW Consulting’s report delivers — practical, transaction-ready outputs
-
Verified market sizing and trend decomposition. We reconcile top‑down macro drivers (raw material indices, foodservice demand, healthcare procurement trends) with bottom‑up manufacturer intelligence to produce a defensible market model for 2020–2032.
-
Scenario analysis and stress testing. Three demand and pricing scenarios are modeled, integrating feedstock price volatility, regulatory shifts (single-use plastics policies), and material innovation adoption curves. Each scenario includes implications for revenue, margin, and working capital.
-
Supply chain and cost-to-serve mapping. Detailed supplier maps, converter networks, and logistics choke-point analysis enable procurement teams to prioritize dual-sourcing, nearshoring, or inventory strategies by risk profile.
-
Buyer and channel playbooks. Actionable guidance for positioning products across retail, foodservice, industrial, and healthcare channels — including suggested SKU architectures, dispenser solution strategies, and pricing frameworks.
-
Regulatory and sustainability toolkits. Lifecycle assessment summaries, end‑of‑life pathways, and a comparative matrix of recycled-content options empower sustainability teams to craft credible claims and procurement specifications.
-
Deal flow support and valuation priors. For M&A teams, we provide target screening criteria, a shortlist of high-potential acquisition archetypes, and valuation priors calibrated to margin profiles and growth prospects in the cling film value chain.
Competitive landscape — strategic implications from incumbent profiles
The market is populated by well-known consumer brands and specialized converters; each player brings a distinct mix of distribution reach, product portfolio, and channel focus. Below are strategic readouts for the key companies profiled in our study. These are intended to guide decision-makers in negotiating partnerships, structuring deals, and anticipating competitive moves in 2026.
-
Berry Global Inc. (Evansville, Indiana) — Strengths: global production and distribution footprint, strong presence in foodservice and healthcare channels, and a portfolio that includes professional-grade cling solutions. Strategic implication: Berry is positioned to win large institutional contracts and to offer integrated packaging systems, making them a preferred partner for buyers seeking single-vendor simplification. For challengers, differentiation must focus on service agility or localized sustainability credentials.
-
Amcor plc (Zurich, Switzerland) — Strengths: recognized foodservice performance brands and scale in flexible packaging. Strategic implication: Amcor can leverage R&D and design capabilities to accelerate premium and recyclable offerings. Counterstrategies for incumbents include tightening converter partnerships in target geographies and fast-tracking eco‑design pilots that prove cost parity.
-
The Glad Products Company (Oakland, California) — Strengths: strong household brand recognition and retail penetration. Strategic implication: Glad’s consumer brand equity provides leverage for new product introductions and private-label initiatives. Competitors should anticipate promotional cycles and align trade terms accordingly.
-
Polyvinyl Films, Inc. (Sutton, Massachusetts) — Strengths: specialty polyvinyl-based films with premium mechanical properties. Strategic implication: Technical superiority in cling, stretch, and cold performance opens doors in food processing and institutional catering where performance justifies price premiums. Buyers in these segments prioritize performance over commodity pricing, creating margin insulation for suppliers.
-
Anchor Packaging Inc. (St. Louis, Missouri) — Strengths: cutterbox safety features and product variants for foodservice and processors. Strategic implication: Product ergonomics and safety are differentiators in professional kitchens; suppliers that bundle dispenser systems and service support can capture share even in mature channels.
-
Wrapex Limited (United Kingdom) — Strengths: eco-focused product lines and dispensing systems tailored to professional catering. Strategic implication: European regulatory pressure and foodservice sustainability commitments create a favorable environment for differentiated eco-products. Replication of these go-to-market models in other regions is an option for ambitious regional players.
Key strategic moves for 2026 — priorities by horizon
-
Immediate (0–12 months): lock in raw-material hedges for critical months, implement dual-sourcing for mission‑critical SKUs, and audit current supplier sustainability claims. Negotiate short-term supply agreements with contractual flexibility for recycled-content switches as validated alternatives become available.
-
Near term (12–36 months): pilot recyclable and recycled-content cling solutions in selected channels, invest in converter partnerships to co-develop dispenser systems, and rationalize SKU portfolios to improve production efficiency and reduce obsolescence.
-
Strategic (36+ months): consider targeted M&A to acquire converter capacity or proprietary film technologies, evaluate capex for localizing rollstock production to reduce logistics lead times, and build closed-loop propositions with retail or foodservice partners.
Decision levers and KPIs to monitor in 2026
-
Cost per linear meter and margin per SKU — to spot erosion early when feedstock volatility spikes.
-
Conversion yield and scrap rates at converters — critical for negotiating unit-based pricing and for evaluating capital investments in higher-efficiency lines.
-
Adoption rates for recyclable/recycled-content SKUs by channel partners and HS code impacts from evolving regulation.
-
Service-level metrics and lead time variability by region — important for foodservice and healthcare customers where stockouts are costly.
What we are intentionally withholding in this preview
To preserve the commercial integrity and tactical value of the study for subscribers, this introduction does not disclose the detailed regional, type, and application-level line-item breakouts that underpin the model. Readers seeking the granular splits — including the full regional demand matrix, application-level demand elasticities, and SKU-level pricing priors — should consult the full report. Those datasets are the basis for our SKU-level playbooks, acquisition screens, and pricing sensitivity analyses, and they are provided with interactive spreadsheets and scenario tools in the subscriber package.
How PW Consulting can help
For leadership teams preparing 2026 budgets, negotiating long-term supply contracts, or building sustainability-compliant product lines, PW Consulting offers tailored advisory services based on this study: bespoke supply risk assessments, M&A target screening, procurement tender support, and operational improvement programs for converters. Our work combines market-grade modeling with on-the-ground converter and brand interviews, delivering recommendations you can operationalize within quarter timelines.
To access the full dataset, strategic appendices, and scenario workbooks, visit PW Consulting’s Cling Film Market report page or contact our industry team for a briefing. The macro trajectory is clear — steady demand, pockets of premiumization, and sustainability-led disruption — but the competitive and geographies-by-application contours in 2026 will decide who captures the upside. Use this study to align your 2026 decisions with an evidence-based roadmap that balances growth, resilience, and regulatory readiness.
For detailed analysis of this topic, please visit the official page: Cling Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com