

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Optical Films Market to Grow 7.1% CAGR to USD 399M by 2032

Optical Films Market — Strategic Outlook for 2026 Decision Makers
Executive summary
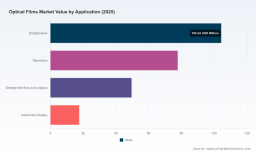
By 2025 the global optical films market had scaled into a clearly commercial phase, reaching an estimated USD 249.15 Million (base year 2025). The market has expanded from roughly USD 177.15 Million in 2020 and, under current structural drivers, is projected to continue at a compound annual growth rate (CAGR) of 7.1% into the 2026–2032 forecast window — reaching an expected USD 399.0 Million by 2032. These headline numbers mask important inflection points that will determine winners and losers in 2026: component engineering (ultra-thin and flexible films), sustainability-driven product redesign, and a reshaping supply chain driven by tariffs, raw material volatility, and regionalization efforts.
Optical Films Market
Why this study matters for corporate strategy in 2026
- Capital allocation: validate or reprioritize investments in new film lines, coating capability, or localized manufacturing to protect margins and time-to-market.
- Supplier strategy: redesign sourcing to manage polymer and specialty-chemical exposure, and to mitigate tariff and export-restriction risk.
- Product roadmap alignment: map optical-film capabilities to end-market shifts — displays, automotive HUD/AR systems, and flexible electronics — to capture premium ASPs.
- M&A and partnership screening: quantify opportunities in consolidation and targeted partnerships that accelerate technology access or regional scale.
Market trajectory and what the aggregated numbers reveal
The reported growth path (2020 → 2025 → 2032) highlights a market moving from component commoditization toward engineered differentiation. Demand remains tied to display cycles, but the marginal growth is coming from higher-value features: thinner form factors for flexible OLEDs, brightness-enhancement stacks that reduce power draw, and films engineered for automotive HUDs and AR overlays. This evolution supports sustained mid-single-digit to high-single-digit CAGR rather than a rapid commoditization-driven price collapse.
Optical Films Market
Equally important is market structure: concentration is moderate. The three largest firms account for roughly one-third of sales, and the top five approach the mid-forties in aggregate share. That profile creates room for focused entrants and regional champions while preserving scale advantages for incumbents that control advanced polymers, coating lines, and intellectual property.
Optical Films Market
Supply-chain and cost dynamics — levers that determine 2026 outcomes
Several structural noise factors will shape decision risk and opportunity:
- Raw-material volatility: polymers such as PET and TAC, and specialty chemicals used in coatings and ITO processes, have shown price swings that materially affect gross margins. Sustainability mandates and recycling requirements add complexity — both compliance costs and an opportunity for premium positioning.
- Regulatory and tariff exposure: export restrictions and higher tariffs on specialty chemicals and certain optical components have already forced re-routing of supply and decision-makers to reassess supplier footprints. This dynamic will continue to push localization and inventory strategies.
- Labor and capacity risks: material shortages and extended lead times have driven investments in localized production and strategic stockpiling. Firms that manage lead-time variability through dual-sourcing or near-shore capacity stand to protect market share in 2026.
- Technology substitution: alternatives to traditional ITO and emerging nanostructured coatings are creating both product-risk and product-upside scenarios depending on a company’s R&D posture.
Competitive landscape — tactical implications for 2026
The competitive map comprises a mix of chemical majors, specialty-film producers, and vertically integrated electronics suppliers. Each archetype implies a different response from buyers and competitors:
- Large diversified players (scale and IP): Firms such as 3M and Eastman leverage broad chemistry expertise and global manufacturing, enabling fast product introductions and capacity expansion. Their moves (e.g., ultra-thin polarizers, new Asia Pacific capacity) set technology and cost baselines for the market.
- Regional champions and speciality suppliers: Companies like Zeon, Toray, Nitto, and Toyobo focus on transmittance, haze control and module-level integration. Their strengths are product customization and relationships with display OEMs.
- Battery and display conglomerates: Suppliers such as Samsung SDI bring integration advantages with OEM customers and can accelerate co-development for next-generation panels.
- Sustainable innovators: LG Chem’s recyclable optical film portfolio is an example of product innovation that addresses regulatory and OEM sustainability mandates, presenting a pricing and differentiation lever for first movers.
Recent corporate activity confirms these patterns: new ultra-thin polarizer launches, expanded manufacturing capacity in Asia, partnerships to develop HUD/AR-specific films, and recyclable product portfolios. These are not isolated events — they signal strategic positioning that will be decisive for contract negotiations and OEM roadmaps in 2026.
What the full PW Consulting report delivers — practical, executable modules
This study goes beyond market sizing to provide operating teams and GMs with tools to move from insight to action. Highlights include:
- Scenario-based demand forecasts: three strategic scenarios (base, tariff-stress, sustainability-accelerated) with implications for capacity, pricing, and working capital.
- Supplier scorecards and risk heat maps: standardized metrics to evaluate supply continuity, raw-material exposure, tariff vulnerability, and ESG compliance.
- Capex prioritization framework: NPV and payback templates tailored to different film technologies and regional investment cases.
- Pricing sensitivity and margin-protection model: a simple-to-deploy tool that quantifies the margin impact of polymer price swings, tariff shocks, and volume shifts.
- M&A and partner-screening playbook: target filters, valuation moats, and integration checklists focused on capability accretion (e.g., coating lines, low-haze polymer IP, recycling tech).
- Commercial playbooks: negotiation levers for OEM contracts, sample-term sheets for long-term agreements, and roadmap alignment templates for co-development with display OEMs and automotive integrators.
Recommended strategic plays for executives in 2026
Based on the market trajectory and competitive moves, PW Consulting recommends executives prioritize a portfolio of six pragmatic plays:
- Dual-track capacity strategy: combine a core long-term facility with flex capacity (contract manufacturing or modular lines) to manage demand spikes and tariff risk without overcommitting capital.
- Sustainability premium: invest selectively in recyclable or lower-carbon film lines to secure OEM sustainability mandates and capture premium pricing where composites are required.
- Raw-material hedging and vertical partners: negotiate multi-year supply agreements with polymer producers and assess minority investments in upstream specialty-chemical capacity.
- Targeted partnerships for automotive/AR: co-develop films tuned for HUD and AR to lock in design wins as automotive displays drive a layer of specialized demand.
- M&A for capability and regional scale: pursue tuck-ins that add low-haze/high-transmittance IP or regional manufacturing footprints in low-tariff jurisdictions.
- Operational digitization: deploy inline metrology and predictive quality controls to reduce scrap, tighten specifications for premium films, and accelerate time-to-sample for OEMs.
Governance, metrics and the 100-day play
Translate strategy into measurable outcomes. Key KPIs for 2026 should include:
- Gross margin by film family (engineered vs commodity)
- Capacity utilization and time-to-ramp for new lines
- Supplier concentration index and tariff exposure score
- Time-to-sample for OEM design cycles
- ESG compliance and recycled-content percentage for qualifying SKUs
A prioritized 100-day plan should establish a cross-functional war room: procurement to renegotiate polymer contracts, R&D to accelerate recyclable-film pilots, and commercial teams to secure design-win commitments with tier-1 OEMs.
Conclusion — where PW Consulting adds value
The optical films market’s headline growth (mid-to-high single digit CAGR) is straightforward; the strategic complexity is not. The interplay of technology shifts, sustainability mandates, tariff regimes, and supplier footprints creates a high-stakes environment for capital deployment and customer lock-in. PW Consulting’s report turns the underlying data into executable strategies: risk-mitigated investment cases, supplier playbooks, and commercial tools that let you win premium share without overexposing the P&L.
For corporate leaders preparing budgets, negotiating OEM contracts, or assessing M&A targets in 2026, the practical modules of this study — supplier scorecards, scenario demand curves, capex prioritization and a negotiation playbook — are the instruments that convert a favorable market trajectory into durable competitive advantage. To review the full analysis, proprietary segment detail, and the plug-and-play financial models that accompany this executive brief, please access the complete PW Consulting Optical Films Market report.
For detailed analysis of this topic, please visit the official page: Optical Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com