

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Labels Market to Expand at 5.37% CAGR Through 2032

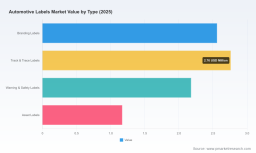
Automotive Labels Market — Strategic Outlook for 2026 Decision‑Making
As OEMs, Tier‑1 suppliers and material innovators prepare procurement and product roadmaps for 2026, the automotive labels market is no longer a commodity conversation. It is a strategic lever across vehicle safety, regulatory compliance, after‑sales traceability and sustainability. PW Consulting’s latest market study (base year 2025; forecast 2026–2032) synthesizes primary interviews, vendor benchmarking and scenario‑based forecasts to convert label specification choices into measurable business outcomes. The global market reached USD 8.67 million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.37% to about USD 12.5 million by 2032 — growth driven by electrification, regulatory tightening and the industry’s sustainability pivot.
Automotive Labels Market
Why 2026 is an Inflection Point
-
Electrification and new vehicle architectures are changing where and how labels must perform. Battery pack identification, EV‑specific safety markings and lightweight interior materials increase technical complexity for adhesives, face stocks and constructions.
Automotive Labels Market -
Regulatory scrutiny — from quality standards such as IATF 16949 to emissions/engine labelling requirements in major jurisdictions — is raising the bar for supplier qualification and in‑service validation.
Automotive Labels Market -
Sustainability requirements are shifting procurement priorities toward circular and recyclable solutions. New product introductions by adhesive and label manufacturers demonstrate that the technology to meet circularity is rapidly maturing.
-
Supply chain resilience matters more: the market shows meaningful concentration among a few large suppliers, which creates tradeoffs between scale advantages and single‑source dependency.
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
-
Strategic market forecast (2026–2032) contextualized by technology, regulation and vehicle architecture scenarios — enabling procurement and product teams to stress‑test decisions across realistic market trajectories.
-
Supplier landscape and competitive scorecards: qualitative and quantitative vendor profiles, manufacturing footprints, compliance certifications and capability maps to shorten shortlist cycles.
-
Materials and construction matrix: decision trees that map adhesive chemistries and face stocks to application zones (interior, exterior, underhood, powertrain, battery) and service life expectations.
-
Cost and value models: total cost of ownership frameworks that incorporate unit costs, qualification lead times, warranty exposure and end‑of‑life recovery potential.
-
Regulatory and certification playbook: compliance checklists (IATF 16949 and other jurisdictional requirements), test protocols, and templates for supplier qualification and OEM audits.
-
Deal‑ready tools: RFP templates, sample test plans, risk heat maps and an M&A screening approach tailored to vendors in this market segment.
Competitive Dynamics — Who Matters and Why
The market structure favors suppliers that combine technical R&D with global OEM relationships and validated manufacturing processes. PW Consulting’s research highlights a cluster of established players that routinely surface in OEM-qualified supplier lists — firms that offer end‑to‑end solutions from adhesive formulation to certified label constructions. These companies bring complementary strengths to the market:
-
3M Company — broad portfolio of durable polyolefin and polyester constructions with proven chemical resistance and established OEM compliance pathways.
-
Avery Dennison Corporation — tested solutions across underhood, interior and EV battery applications; recent product introductions and published durability validations reflect a strong product‑development cadence.
-
Brady Corporation — industrially hardened labeling solutions designed for harsh environments and OEM vehicle applications.
-
UPM Adhesive Materials — repositioned with a portfolio that explicitly targets circularity and recyclable constructions, including new adhesive platforms aimed at reuse and material recovery.
-
CCL Industries Inc. — pressure‑sensitive label specialist with proven constructions for durable and compliant automotive markings.
-
Resource Label Group — local, UL‑recognized solutions and rapid customization capabilities for North American OEMs and parts suppliers.
-
Whitlam Group, UP‑Labels GmbH, Adhesive Research and H.B. Fuller — each contributes niche strengths from custom engineering and specialized adhesive chemistries to tire identification and IATF‑aligned manufacturing.
These vendors are active: recent product launches, rebranding efforts and third‑party validation campaigns indicate accelerated competition around durability, lightweight constructions and circular adhesives. For example, a leading materials supplier introduced special constructions and published independent testing in 2025; another rebranded and presented a Carbon Action label portfolio aimed at circular automotive applications the same year. PW Consulting’s supplier scorecards capture these dynamics and evaluate vendors not only on product specifications but on validation discipline, OEM acceptance rates and supply‑chain agility.
Regulation, Materials and the Sustainability Imperative
Labeling in vehicles is tightly bound to regulatory compliance and safety protocols. IATF 16949 remains a gating criterion for many OEM supplier approvals; heavy‑duty engine and emission labelling continue to reference established jurisdictional requirements. Separately, the industry’s move toward circularity is enabling new supplier value propositions: adhesive systems engineered for recyclability and label constructions designed to facilitate material reclamation are emerging as differentiators. PW Consulting’s analysis quantifies the commercial impact of these trends and provides a pathway for procurement teams to incorporate circularity performance into supplier scorecards without destabilizing qualification timelines.
Actionable Recommendations for 2026 Planning
-
Prioritize dual‑sourcing for critical application zones. Where labels interface with safety systems or battery packs, dual validated suppliers reduce program risk without materially increasing lifecycle cost.
-
Increase early‑stage testing against real‑world stress profiles. Invest in accelerated aging and underhood exposure tests during the prototyping phase to avoid late design changes.
-
Embed circularity metrics in supplier panels. Require adhesive recoverability and recyclability performance as part of RFQ evaluation criteria for any mid‑to‑long‑life programs.
-
Align procurement slots with certification cycles. Use supplier scorecards to map lead times for IATF‑aligned audits and validation runs so that label qualification aligns with vehicle program milestones.
-
Use the report’s TCO models to compare standard constructions against premium circular and high‑durability options on a lifecycle basis rather than unit price alone.
Risk Scenarios and What to Monitor
PW Consulting models three plausible scenarios through 2032 — a conservative baseline, a technology‑led adoption curve and an accelerated sustainability mandate — each with implications for material choice, supplier concentration and pricing. Key risk vectors for 2026 include raw material cost volatility, certification bottlenecks and geopolitical exposure in adhesive supply chains. Mitigation tactics include strategic inventory policies for critical face stocks, qualification of regional alternate suppliers and contractual language that preserves IP while enabling co‑engineering for circular products.
How to Use This Study in Your 2026 Planning Cycle
For CPOs, head engineers and corporate sustainability leads, the report is a toolkit: it translates market forecasts into procurement actions, technical specifications into qualification roadmaps and vendor intelligence into shortlist decisions. The study’s forecast frames capital and operating decisions, while the supplier scorecards and RFP templates accelerate execution. To protect proprietary commercial models and to preserve competitive advantage for readers, the report provides detailed segmentation tables, regional and application splits and full vendor benchmarking only within the delivered dataset and client portal.
Next Steps
-
Download the executive brief or request the full dataset to access tables, regional and application splits, and downloadable supplier scorecards.
-
Commission a PW Consulting workshop to translate the report’s scenarios into a labeled supply‑chain stress test tailored to your vehicle programs.
-
Engage our advisory team for vendor due diligence and M&A screening if you are evaluating strategic acquisitions or joint development agreements in the label and adhesive space.
PW Consulting’s Automotive Labels Market study is designed to convert a small but critical component category into a strategic advantage for 2026. By combining market‑level forecasts (5.37% CAGR to 2032), concentration analysis, supplier benchmarking and actionable procurement tools, the research equips executives to make risk‑adjusted, future‑proof decisions now — while preserving access to the granular data and supplier intelligence that will be decisive in the next vehicle development cycle.
For detailed analysis of this topic, please visit the official page: Automotive Labels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com