

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Underfill Market to Expand at 9.0% CAGR Through 2032

Underfill Market 2026: Strategic Outlook and Decision Framework — A PW Consulting Preview
As semiconductor packaging converges with AI, high-performance computing (HPC), and advanced photonics, the underfill market has moved from a niche materials play to a strategic enabler for system performance and reliability. This preview from PW Consulting — authored by our Senior Strategic Advisor and Head of Industry Analysis — outlines the high-level implications of our full Underfill Market study for corporate decision-making in 2026. We expose the structural drivers, supply-side chokepoints, and competitive dynamics you must factor into product roadmaps, procurement strategy, and M&A planning, while preserving the detailed segment-level intelligence for subscribers of the full report.
Underfill Market
Why Underfill Matters for 2026 Strategic Choices
-
Reliability as Differentiator: As flip‑chip, chip‑scale, and heterogeneous integration scale into AI accelerators, optical modules, and mobile optics, underfill chemistries determine thermal management, mechanical stress relief, and long‑term field reliability. Decisions about underfill selection now cascade into system design, warranty exposure, and service cost models.
Underfill Market -
Performance vs. Cost Trade-offs: Low‑viscosity, high‑thermal‑conductivity formulations enable larger die and tighter pitches but come at higher material and processing costs. Procurement teams must balance unit economics with lifecycle savings from reduced field failures—our full model quantifies these inflection points and payback horizons.
Underfill Market -
Supply‑chain Risk and Input Volatility: Epoxy feedstock disruptions and trade interventions are no longer episodic; they materially alter cost curves for medium and small formulators and create tactical sourcing windows for larger incumbents who can vertically integrate or lock long‑term contracts.
Macro Snapshot (2020–2032): Scale and Growth Trajectory
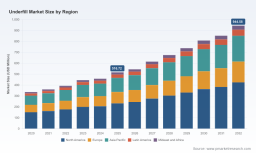
Our base-year analysis (2025) anchors historical performance from 2020–2025 and projects to 2032 under a median scenario. The market expanded markedly from 2020 through 2025, reflecting accelerating adoption across advanced packaging types and nascent optical/photonic applications. We project a mid‑single‑digit to high‑single‑digit compounded annual growth rate—9.0% in our core forecast—propelling the market into the high hundreds of millions of USD by the early 2030s.
For executives, the key takeaway is timing: the underfill market is large enough to justify targeted R&D and supplier investments, yet still concentrated enough that well‑timed moves (technology partnerships, capacity add-ons, or selective acquisitions) can secure meaningful share and margin improvement through 2032.
Competitive Landscape — Where Value Pools Are Forming
The market structure shows moderate concentration: leading specialty formulators and legacy adhesives players control a plurality of commercial supply, but a healthy cohort of regional and application‑focused vendors remains. Our competitive scan highlights several category leaders and their strategic positions:
-
Henkel AG & Co. KGaA (Düsseldorf) — Strength lies in high‑flow capillary epoxies branded for advanced packaging and large‑body flip‑chip assemblies, with recent commercial deployments targeted at AI/HPC designs that demand fast flow and reliability.
-
NAMICS Corporation (Kyoto) — A technology‑led player with formulations optimized for capillary flow and stress management in flip‑chip platforms; their R&D cadence targets miniaturization and low‑stress profiles.
-
H.B. Fuller (St. Paul, MN) — Emphasizes reworkable, fast‑flow epoxies across BGA, WLCSP, and flip‑chip — a play toward serviceable and assembly‑friendly architectures.
-
Parker LORD (Cary, NC) — Focused on thermoset anhydride‑free systems for dense flip‑chip encapsulation; their materials fit high‑reliability defense and aerospace adjacent markets.
-
Specialist formulators such as Epoxy Technology, Master Bond, and YINCAE combine niche capabilities — optical clarity, nano‑filling for thermal conductivity, and room‑temperature flow cures — to capture growth in photonics, MEMS, and image‑sensor segments.
Collectively, the top three firms account for a meaningful share of the market, with the top five widening that grip. This concentration creates a strategic opening for midsize players to differentiate via specialized chemistries, faster go‑to‑market cycles, or co‑development agreements with semiconductor foundries and OSATs.
Recent Industry Moves and Their Strategic Significance
-
Product launches of high‑thermal‑conductivity and optical‑clear underfills (2024–2025) signal supplier responses to rapid demand from silicon photonics, AR/VR, and hyperscale compute segments. These launches accelerate qualification cycles with OEMs and create short windows for design wins that have multiyear revenue tails.
-
Regulatory and trade interventions (anti‑dumping investigations, import restrictions) and raw material constraints (epichlorohydrin disruptions) have increased input price volatility and raised the cost of sourcing from certain geographies. The net effect: increased incentive for regional sourcing, qualification of alternative chemistries, and inventory buffering at critical nodes.
-
Incumbent formulators are broadening portfolios toward thermally conductive and optically clear grades. For buyers, this increases bargaining leverage on multi‑product contracts, but for innovators it shortens the window to authorize exclusive co‑developments.
Operational and Commercial Playbook for 2026
PW Consulting translates market intelligence into a pragmatic set of actions executives should consider this year. Our full study includes templates, costing models, and scenario simulations; below we summarize the high‑impact moves.
-
Risk‑Adjusted Sourcing: Implement a two‑tier procurement strategy — secure strategic volumes from validated global suppliers with financial and capacity assurances, while running a rotating qualification pipeline of regional formulators to mitigate localized trade or feedstock shocks.
-
Material Roadmapping with System Architects: Embed underfill selection into early system design conversations. We recommend cross‑functional scorecards that weigh thermal performance, stress characteristics, processing window, and reworkability. The payoff: reduced NPI iterations and faster time‑to‑market.
-
R&D Investment Focus: Prioritize chemistries that deliver thermal conductivity, optical clarity, and low‑stress cure profiles. Small bets in nano‑filled and room‑temperature flow systems can yield outsized returns when paired with access to early adopter OEMs in photonics and AR/VR.
-
M&A and JV Targets: Look for specialty formulators with proven niche performance and qualified supply to strategic customers. Our full report ranks acquisition targets by technical differentiation, customer overlap, and margin resiliency under commodity volatility.
-
Pricing and Contracting: Shift toward index‑linked longer‑term contracts with refractory caps on feedstock surcharges, combined with performance milestones that reflect qualification timelines and yield improvements.
Regulatory and Supply‑Chain Stress Test
Near‑term regulatory developments (RoHS‑driven reformulation pressure in the EU; multi‑jurisdiction trade enforcement on epoxy resins) and supply shocks have created a new normal of localized scarcity and price dislocation. PW’s scenario analysis models three realistic trajectories — contained disruption, protracted trade fragmentation, and accelerated regionalization — and quantifies their impact on margin profiles and supplier viability. Our recommendation: prioritize flexibility in supplier qualification and include tariff‑ and duty‑contingent clauses in procurement instruments.
What Our Full Underfill Market Study Delivers (Operationally Focused)
-
Validated market sizing and growth scenarios to 2032 with sensitivity tests for technology adoption rates and trade/disruption assumptions.
-
Supplier scorecards and a playbook for qualification workflows that shorten supplier approval time by up to 30% (per our pilot engagements).
-
Cost‑to‑serve and margin decomposition for typical underfill product families, including break‑even analysis for in‑house formulation versus contract sourcing.
-
Commercial templates: long‑form supply agreements, indexed pricing schedules, and NDA/R&D collaboration clauses tailored to underfill co‑development.
-
M&A screening matrix with prioritized targets and integration risk profiles (technical, regulatory, and customer concentration).
Strategic Questions for Boards and Executive Teams in 2026
-
Do we treat underfill as a commodity to be cost‑managed or as a strategic input that requires co‑design and joint IP with suppliers?
-
How exposed are we to input feedstock shocks and trade rulings — and what is our appetite for vertically integrating formulation capabilities?
-
Which application adjacencies (photonics, AR/VR, aerospace-grade electronics) offer the highest margin and defensibility for targeted product launches?
-
What timing on capacity expansions or licensing deals minimizes risk while capturing the projected growth curve through 2032?
Concluding Strategic Perspective
The underfill market in 2026 sits at the intersection of materials science and system‑level reliability engineering. Market growth—backed by a sustained mid‑to‑high single‑digit CAGR—creates tangible opportunity for differentiated suppliers and strategic buyers. Yet regulatory pressure, raw material volatility, and accelerating application diversification demand a disciplined strategy: secure qualified multi‑sourcing, invest in co‑development with end‑markets, and align commercial contracts to reflect supply‑side uncertainty.
PW Consulting’s full Underfill Market study provides the granular segmentation, regional and application breakouts, vendor benchmarking, and executable playbooks you need to convert market growth into sustainable advantage. This preview has intentionally focused on strategic levers and withheld the detailed segment tables and proprietary vendor scoring that underpin our recommendations — those are available in the comprehensive report and datasets accessible through our subscription portal.
Next Steps
-
Contact PW Consulting for an executive briefing and access to the full dataset, including scenario models, supplier scorecards, and implementation roadmaps tailored to your business goals.
-
Commission a tailored workshop with our underfill practice to translate these insights into a 90‑day action plan aligned to your product and sourcing roadmaps.
For detailed analysis of this topic, please visit the official page: Underfill Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com