

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Histidine Market to Reach USD 338.85 Million by 2032 — PW Consulting Insight

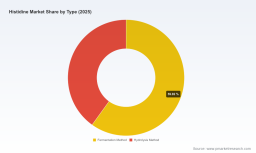
Histidine Market: Strategic Imperatives for 2026 Decision-Makers
As the histidine market enters a new phase of commercially relevant expansion, decision-makers must calibrate strategy against an evolving demand base, concentrated supplier footprints, and shifting trade dynamics. Our latest PW Consulting market study — grounded on a 2025 base year, with a historical window from 2020–2025 and a forecast through 2026–2032 — projects a robust compound annual growth rate (CAGR) of 6.8%. The global market, estimated at approximately USD 215.0 Million (revenue unit: Million) in 2025, is set to climb materially by 2032 under current trends. This briefing highlights the report’s practical value for 2026 planning while intentionally preserving the proprietary segmentation and pricing matrices behind our full release.
Histidine Market
Why histidine matters to 2026 strategy
Histidine is no longer a niche amino acid confined to legacy feed and food use cases. Acceleration in cell-culture therapies, parenteral nutrition formulations, and higher-value biopharma applications has expanded both the purchasing stakes and the quality bar. For corporate leadership, three strategic realities stand out:
Histidine Market
- Growing, but selective demand: Market volumes and revenues are increasing predictably (2025 baseline USD 215.0 Million; forecast shows a clear uptrend to the 2032 horizon), yet growth pockets are uneven and quality-sensitive — privileging suppliers that can meet GMP, low-endotoxin and low-metal specifications.
- Supplier concentration and capability-driven sourcing: Industry concentration metrics indicate that the market is meaningfully clustered among a handful of specialized producers. That concentration elevates supplier risk and makes differentiated capability (fermentation-derived high-purity grades, GMP supply chains) a decisive commercial lever.
- Trade and regulatory volatility: Recent policy moves affecting chemical intermediates and exports have real near-term implications for raw material access, costs and contract security — factors that must be embedded into 2026 sourcing and investment choices.
Key macro signals embedded in our analysis
- Base year clarity: the study uses 2025 as the analytical anchor to ensure all forward-looking scenarios reflect the most recent commercial and regulatory environment.
- Historical trend closure: the 2020–2025 historical series grounds our adoption curves, enabling robust attribution of cyclic vs secular drivers behind demand.
- Forward visibility: the 2026–2032 forecast is built on a 6.8% CAGR and scenario-based adjustments; the headline projection shows substantial upside for firms that secure high-purity channels and commercialized product differentiation.
- Concentration context: market concentration indicators are incorporated to quantify counterparty exposure and to shape diversification strategies.
What the full report delivers (practical, transaction-ready outputs)
- Market sizing and modeled forecasts tailored to multiple adoption scenarios — baseline, upside (accelerated biopharma adoption), and downside (regulatory friction).
- Demand-driver decomposition that isolates biopharma-grade adoption, feed/food steady-state demand, and the contribution profile of emerging applications.
- Supplier capability mapping and comparative scorecards (quality, capacity, regulatory readiness, geographic exposure) to support vendor selection and contingency planning.
- Technology and route economics comparing fermentation and hydrolysis production pathways, including capex/opex profiles, scalability constraints and margin sensitivity.
- Pricing intelligence and channel dynamics — transactional benchmarks, observed premium bands for GMP/high-purity grades, and seasonality patterns (note: detailed price curves and unit-level tables are reserved for the full report).
- Regulatory and trade scenario playbooks, with impact matrices tied to likely policy moves in production hubs and export regimes.
- Commercial growth playbooks: channel strategies, partnership archetypes, and contracting templates for multi-year supply security.
- Investment and M&A assessment framework — valuation ranges, break-even timelines and operational triggers for greenfield vs brownfield investments.
- Actionable procurement tools: supplier diversification scorecards, risk heatmaps, and contract clause recommendations for quality and continuity.
Competitive landscape — what to watch
The competitive set is composed of established specialty chemical and life-science suppliers, fermentation-focused incumbents, and regional producers focused on commodity grades. Representative firms covered in the study include Ajinomoto, Kyowa Hakko Bio, Evonik, Merck KGaA, Pfanstiehl, Daesang and Changzhou Highassay — each with distinct positioning:
Histidine Market
- Firms with fermentation-optimized platforms emphasize high-purity GMP grades tailored for cell culture media and parenteral uses; these suppliers are increasingly sought for secure supply of high-value applications.
- Legacy chemical suppliers and regional producers offer cost-competitive volumes for feed and standard food applications, but face pressure to meet the higher regulatory and quality bar demanded by biopharma customers.
- Niche players and contract manufacturers (including toll-providers) are emerging as tactical partners for firms seeking flexibility without committing to capex-heavy expansions.
Strategic partnerships and alliances are already reshaping the supply landscape. A notable example included in our dataset is a March 2025 strategic collaboration where a major fermentation-based producer moved to co-develop and secure additional global supply. This type of alliance signals a broader trend: firms are layering partnerships to mitigate raw-material exposure and to accelerate access to GMP-capable supply chains.
Regulatory and trade developments with immediate relevance to 2026
Policy shifts affecting chemical intermediates and export controls have the potential to alter the sourcing calculus for buyers and producers alike. Recent public records indicate temporary adjustments to export control posture on certain dual-use intermediates; these changes can reduce friction in the short term but introduce uncertainty as timelines, end-user verification and enforcement frameworks remain fluid. Procurement teams must therefore adopt conditional contracting that balances near-term opportunity capture with clauses for continuity and force majeure protections.
Strategic recommendations for 2026
Based on the intersections of demand trajectory, supplier concentration and policy ambiguity, PW Consulting recommends that companies structure a phased, risk-weighted response in 2026:
- Secure multi-tiered supply: Adopt a multi-source strategy that combines a primary GMP-certified supplier for critical applications with secondary regional or contract manufacturers for non-critical volumes. Embed escalation and audit rights in contracts.
- Prioritize capability over lowest-cost: For cell-culture and parenteral products, prioritize suppliers with proven low-endotoxin, low-metal capabilities and documented GMP traceability even at a premium — the cost of failure in these segments exceeds short-term savings.
- Accelerate partnership options: Evaluate strategic partnerships, toll-manufacturing agreements, or minority investments in fermentation capacity. These options balance speed-to-market and control without immediate full-scale capex.
- Operationalize regulatory monitoring: Set up a cross-functional early-warning system to track trade and export policy shifts in key producing jurisdictions and translate alerts into procurement triggers.
- Embed contingency financial planning: Incorporate volatility buffers into 2026 budgets — both for raw material price variation and for potential costs from quality remediation or supplier substitution.
Near-term timeline — recommended 2026 milestones
- Q1 2026: Complete supplier capability audits for all high-priority SKUs; lock short-term supply with contingency clauses.
- Q2 2026: Finalize one or more partnership/toll agreements to secure scalable fermentation capacity for high-purity grades.
- Q3 2026: Implement a live regulatory-tracking dashboard and test contractual escalation protocols via tabletop simulations.
- Q4 2026: Review and adjust sourcing strategy against observed price and supply outcomes; consider strategic investments if demand acceleration persists.
Where this briefing intentionally leaves questions
To preserve the strategic value of the full PW Consulting deliverable, this introduction intentionally omits granular segmentation tables, unit-price curves, and the proprietary supplier-scorecard datasets that underpin negotiations and valuation models. These elements are available in the full report and are provided in machine-readable form to support procurement, commercial and M&A diligence.
Next steps
For leadership teams preparing 2026 budgets and strategic plans, the full PW Consulting Histidine Market Report supplies the transactional-level detail necessary to execute on the recommendations above: contract-ready supplier templates, detailed price and volume scenarios, and supplier-specific risk assessments. Contact PW Consulting to access the full dataset, tailored supplier scorecards, and our scenario-modelling toolkit to convert this market trajectory into defensible procurement and investment decisions.
For detailed analysis of this topic, please visit the official page: Histidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com