

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Driving Recorder Market to Grow at 8.5% CAGR (2026-2032)

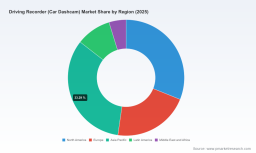
Driving Recorder (Car Dashcam) Market — Strategic Outlook for 2026 Decision-Making
As global road safety, fleet telematics and in-vehicle intelligence converge, the Driving Recorder (car dashcam) market has moved from a niche safety accessory into a strategically important product class for OEMs, Tier‑1 suppliers, fleet operators and aftermarket vendors. Our PW Consulting market study (base year 2025, historical 2020–2025, forecast 2026–2032) shows a sustained expansion trajectory driven by hardware quality improvements, AI-enabled video analytics and tighter regulatory scrutiny. The market reached a meaningful milestone in 2025 and is projected to continue growing at a compounded annual growth rate of 8.5% through the 2026–2032 forecast window.
Driving Recorder (Car Dashcam) Market
Why this report matters for 2026 strategy
-
Timing: 2026 is a hinge year. Product roadmaps that integrate higher-resolution imaging, onboard AI and cloud connectivity are moving from prototype to commercial programs. Decisions made in 2026—about component sourcing, cloud partnerships, and product positioning—will determine whether a business captures premium value or competes on low-margin hardware.
Driving Recorder (Car Dashcam) Market -
Market momentum: After recovering from pandemic-era supply shocks and uneven demand through 2020–2023, the market expanded into 2024–2025 and enters a predictable upswing in unitization and ASPs driven by multi-channel and AI-enabled offerings.
Driving Recorder (Car Dashcam) Market -
Structural pressures: Two systemic forces—escalating semiconductor and memory constraints, and intensified national security-focused export controls—are reshaping sourcing strategies and commercial cycles. These constraints are already affecting product launch timing and margins.
What our PW Consulting report provides (practical, action-ready deliverables)
-
Integrated market sizing and seven-year forecasts (2026–2032) with scenario snapshots tuned to supply‑chain disruption, rapid AI adoption, and regulatory tightening.
-
Competitive mapping and vendor benchmarking that evaluates product portfolios, route-to-market, software stack maturity and cloud capability—scored against commercial KPIs.
-
Technology roadmap analysis that compares imaging sensors, codec strategies, onboard compute versus edge/cloud processing and ADAS convergence trends.
-
Supply‑chain risk register including supplier concentration, lead-time stress tests, and procurement playbooks to mitigate memory and semiconductor scarcity.
-
Commercial playbooks: pricing scenarios, subscription/recurring-revenue models, fleet monetization levers and OEM co‑development templates.
-
M&A and partnership heatmaps highlighting likely consolidation targets, white‑space entrants and strategic fit matrices for investors and corporate development teams.
-
Regulatory impact assessment covering export controls, data privacy and cross-border telemetry rules with recommended compliance architectures.
Market shape and competitive dynamics — what incumbents and challengers are doing
The market exhibits a moderate fragmentation profile: a handful of vendors capture a material share of value while numerous specialty players compete on feature differentiation, price and distribution. This structure favors both continued product specialization (multi‑channel, parking surveillance, AI analytics) and opportunistic consolidation. Below are strategic snapshots of key players we benchmarked in the study.
-
Viofo (Shenzhen, China) — Strengths: competitive hardware engineering, sensor sourcing and professional-grade feature sets. Strategic implication: along with other China-origin OEMs, Viofo is well positioned to scale manufacturing quickly; its win pathway depends on moving beyond hardware into software services and channel partnerships for value capture.
-
BlackVue / Pittasoft (Seongnam-si, South Korea) — Strengths: premium positioning, cloud-enabled surveillance and fleet-focused architectures. Strategic implication: high-value features like cloud parking surveillance and remote evidence retrieval command recurring revenue opportunities, but rely on robust service platforms and infrastructure partnerships.
-
70mai (Shanghai, China) — Strengths: rapid feature innovation, AI-enabled safety functions and strong consumer channel penetration. Strategic implication: can scale software updates and consumer subscriptions, but must protect margins against component inflation and defend brand differentiation as lower-cost rivals adopt similar features.
-
Garmin (Olathe, USA) — Strengths: integration with navigation/GPS ecosystems and voice/UX differentiation. Strategic implication: Garmin can leverage its mapping and voice platforms to upsell integrated solutions to vehicle buyers and fleet customers.
-
Thinkware (Coquitlam, Canada) — Strengths: ADAS alerts, parking surveillance and imaging sensor quality; recent product introductions underscore an aggressive premium strategy. Strategic implication: Thinkware’s play for fleet and premium aftermarket buyers signals competitive pressure on margins among high-end suppliers who must justify price through service and analytics.
-
Vantrue (United States) — Strengths: high-end multi-channel video and strong security-focused value proposition. Strategic implication: niche segmentation around multi-camera architectures and secure logging offers a defensible position against commoditization.
-
Nextbase (United Kingdom) — Strengths: brand recognition, quality design and fleet-oriented solutions. Strategic implication: known brands can transition to fleet and subscription models, but need to accelerate cloud/analytics capability.
Recent industry developments and their strategic consequences
-
Fleet AI adoption: Geotab’s 2025 GO Focus Plus AI dashcam deployment demonstrated meaningful behavior change in pilots—highlighting the rising importance of integrated video intelligence platforms for reducing risk and insurance spend. For suppliers, this raises the bar on software analytics and long‑term service value.
-
OEM convergence: Magna’s public advances in integrating higher-resolution imaging and onboard recording into ADAS modules signal potential encroachment by Tier‑1s into traditional dashcam territory—creating both a white-label OEM opportunity and a margin squeeze for independent vendors.
-
Product differentiation: 2026 launches from established players introduced hybrid solutions that couple higher-resolution sensors with RADAR and advanced parking modes—validating that multi-sensor convergence is migrating from premium experiments to mainstream capabilities.
-
Supply strain and cost: memory prices and semiconductor lead times have materially worsened since late 2025, elevating BOM risk and elongating product delivery timelines. Procurement strategies and product architectures must be stress-tested against lead-time scenarios.
-
Policy and trade: a wave of export-control and national-security legislation is reshaping sourcing flexibility for certain component categories. Companies with cross-border supply chains should evaluate compliance exposure now—especially those dependent on constrained imaging and compute components.
Recommended strategic moves for 2026
-
Initiate scenario-based product roadmapping that incorporates three procurement states (optimistic, baseline, stressed). Prioritize modular architectures that allow for component swaps without full redesigns.
-
Lock in strategic supply through long‑term agreements and qualified second-source suppliers for memory and key SoCs. For critical components, consider co-investment or allocation agreements when feasible.
-
Accelerate software-led monetization: subscription services (cloud storage, analytics), telematics bundles for fleets, and embedded post‑event analytics materially improve lifetime value and dampen hardware volatility.
-
Explore partnerships with cloud providers and telematics platforms to offload storage and analytics costs while preserving evidence integrity and privacy compliance.
-
For investors and M&A teams: target companies with robust software platforms and recurring revenue, or specialized sensor/AI capabilities that are hard to replicate under current supply constraints.
-
Prepare for compliance complexity: embed export-control risk assessments into supplier selection and contractual clauses; evaluate geofencing or selective feature flags to maintain market access.
Concluding perspective — the strategic value of the full report
For executives making resource-allocation and product roadmap choices in 2026, access to accurate, scenario-driven market sizing and supplier intelligence is no longer optional. Our base-year analysis captures the market condition through 2025 and projects forward under an 8.5% CAGR assumption across 2026–2032, offering a structured view of demand, price pressure and value‑pool shifts. The full PW Consulting study contains the granular, actionable datasets—region- and application-level forecasts, vendor market shares and price curves, segment-specific unit economics and a downloadable supplier-risk matrix—that are intentionally withheld in this preview to preserve the competitive edge our clients require.
If your 2026 strategy depends on securing supply, defending margin, or capturing recurring-service value in the driving-recorder ecosystem, this report will give you the tactical frameworks and decision-grade intelligence to act confidently. For the complete dataset, vendor scorecards and proprietary scenario models, please consult the full PW Consulting market report.
For detailed analysis of this topic, please visit the official page: Driving Recorder (Car Dashcam) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com