

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Cable Management Market to Reach USD 470.28 Million by 2032 at 9.25% CAGR
By pmarketresearch, 2026-07-23
Cable Management System Market — Strategic Outlook for 2026 Decision‑Makers
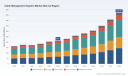
As organizations plan capital allocation and product strategy for 2026, the cable management system market is moving from a mature, utility-style procurement category into a dynamic component of digital infrastructure and industrial resilience. Our latest PW Consulting market study synthesizes five years of historical performance and a rigorous 2026–2032 forecast to translate market dynamics into actionable choices. In brief: the market that measured roughly USD 215 million in 2025 is projected to expand at a compound annual growth rate of 9.25% over the forecast window, with a multi‑year trajectory that more than doubles the sector’s revenue base by the early 2030s. This growth is neither uniform nor risk‑free — it is concentrated at the intersection of data‑center scale‑outs, regulatory tightening, and supply‑chain volatility.
Cable Management System Market
Why this matters for 2026 corporate decisions
- Investment timing and prioritization: With a robust near‑term growth rate, 2026 is a pivot year for capitalizing on structural tailwinds (high‑density computing, electrification, and industrial automation). Companies that move early to secure manufacturing capacity, certification pipelines, and supply contracts will avoid the margin compression that follows commodity shockwaves.
- Product architecture and differentiation: Buyers are increasingly demanding modular, serviceable, and thermally aware cable management systems — particularly for liquid‑cooled and high‑density racks. This shifts value from raw materials into design, installation tooling, and integrated services.
- Regulatory and compliance risk: New and revised standards (notably the fourth edition of UL 62275 published in May 2025, ongoing NFPA 70 reorganization in 2026, and CLC/TS 50658:2025 on fire‑resistant systems) materially change certification roadmaps. Non‑compliance now risks exclusion from major infrastructure tenders and increased time‑to‑market.
- Supply‑chain resilience: Raw‑material price swings (steel, PVC, composites experiencing double‑digit volatility in early 2025) require procurement models that balance fixed contracts, hedging, and strategic vertical partnerships.
Key demand drivers shaping the market
- Data center expansion and densification: Continued investment in hyperscale and colocation facilities — including substantial U.S. construction spending — is intensifying demand for scalable cable routing, high‑density rack management, and liquid‑cooling compatible systems.
- Industrial digitalization and electrification: Manufacturing modernization, EV charging infrastructure, and distributed energy resources are driving non‑IT applications that require ruggedized and fire‑compliant cable containment solutions.
- Regulatory tightening and safety standards: New standards are raising the technical bar on mechanical performance, fire resistance, and traceability, pushing suppliers to invest in testing and certification early in the product lifecycle.
- Material and manufacturing innovation: Composite and polymer alternatives are gaining traction where corrosion resistance and weight reduction deliver operational value, while stainless and galvanized steels remain dominant where mechanical robustness is critical.
Strategic playbook for 2026 — recommended moves
- Rebalance portfolio toward high‑value systems: Prioritize modular solutions for data centers and certified fire‑resistant systems for critical infrastructure. Emphasize services — installation, lifecycle monitoring, and retrofitting — to capture recurring revenue.
- Accelerate certification pathways: Map regulatory change to product roadmaps now. Allocate engineering and testing capital to meet UL, NFPA, and CEN timelines; delayed certification is the fastest way to miss major tenders.
- Harden supply chains with multi‑tier strategies: Combine long‑term agreements for core metals with alternative sourcing for polymers and composites. Evaluate local assembly hubs to mitigate lead‑time risk for large regional projects.
- Commercial tactics for price volatility: Adopt indexed pricing clauses, value‑packaging (hardware + installation), and outcome‑based contracts for large installs where clients will accept higher upfront CapEx for predictable life‑cycle costs.
- Data‑center specialist go‑to‑market: Build partnerships with integrators and cooling OEMs. Productize rack‑level cable management that is pre‑tested for liquid‑cooling exposures and high‑density cabling scenarios.
What the PW Consulting report delivers (practical, executable content)
This study is oriented to action. We avoid abstract generalities and instead provide tools procurement, product, and strategy teams can use immediately:
Cable Management System Market
- Scenario‑based demand model covering conservative, base, and upside cases across 2026–2032 with sensitivity to data‑center capex and raw‑material swings.
- Stress‑tested financial templates for product launch ROI, incorporating certification timelines, material cost inflation, and service revenue assumptions.
- Supplier benchmarking and a qualitative vendor scorecard focused on technology breadth, certification readiness, geographic reach, and aftermarket service capability.
- Regulatory compliance matrix aligned to UL, NFPA, and CEN standards, with recommended test plans and timeline checklists to meet 2026 procurement windows.
- Go‑to‑market playbooks for winning large data‑center and industrial tenders, including sample contract clauses and installation service offerings.
- Risk heatmaps and mitigation playbooks for procurement, manufacturing, and product certification risks.
Note: the public executive summary highlights trends and recommended actions. Our full deliverable includes the detailed segmentations, vendor market shares, and the spreadsheet model that operational teams use to run “what‑if” scenarios. These core datasets are intentionally reserved to provide our clients with exclusive decision advantage.
Cable Management System Market
Competitive landscape — positioning and implications
The competitive field remains fragmented. Aggregate concentration metrics indicate a market where leading global electrical and infrastructure players co‑exist with specialized niche vendors and regional manufacturers. A modest top‑three concentration underscores opportunities for differentiated offerings rather than purely scale‑driven competition.
- Global systems integrators and electrical majors (e.g., Eaton, Schneider Electric, Legrand): These firms bring deep infrastructure portfolios and channel reach for commercial, industrial, and data‑center projects. Their advantage is integrated solutions and global service networks — making them preferred vendors on complex, multi‑site tenders.
- Data‑center and telecom specialists (e.g., Panduit, The Siemon Company): Strengths lie in high‑density management, labeling, and rack‑level ecosystems. Their speed to adopt data‑center innovations positions them well for hyperscaler and colocation business.
- Industrial and safety‑focused suppliers (e.g., Niedax, Roxtec, NORMA Group): These players capture demand where mechanical protection, environmental sealing, and fire resistance are table stakes — notably in heavy industry, offshore, and hazardous environments.
- Fast innovators and material specialists (e.g., Enduro Composites, local manufacturers): Composites and polymer specialists are disrupting niches where corrosion resistance and weight matter. Their commercial scale is smaller, but their technology can be embedded by larger OEMs via partnerships or acquisitions.
Recent vendor activity illustrates a market with steady product innovation and project‑level growth: product launches targeted at data‑center routing systems, large project deliveries of cable cleats to sizeable infrastructure projects, and ongoing standards updates that force product refresh cycles. These dynamics favor suppliers who combine product R&D with certification and project execution capabilities.
Risk factors and mitigation
- Material price volatility: 2025 saw significant swings in galvanized steel and PVC inputs. Mitigation: diversify material options, negotiate blended fixed/variable supply contracts, and prioritize higher‑margin engineered products.
- Standards acceleration: Revised UL and CEN documents raise compliance costs. Mitigation: proactive certification investments and early participation in standards working groups to shape test protocols.
- Fragmented purchase behavior: Many buyers still source on price alone. Mitigation: shift contracting to value metrics (downtime risk reduction, install time savings, maintainability) and embed services to lock long‑term relationships.
- Execution risk on large projects: Complex installations (hyperscale data centers, industrial retrofits) expose suppliers to schedule and liability risks. Mitigation: subcontract scaffolding and electrical installers through vetted partners and provide performance guarantees where feasible.
Closing perspective — what to do next in 2026
For boards and executive teams planning 2026 allocations, the decision is less about whether the cable management market grows (it does) and more about where you will capture value as it evolves. Will you compete on low‑cost commodity trays, or will you own the interface between cabling and critical infrastructure strategy — certified, serviceable, and integrated with thermal and safety ecosystems?
PW Consulting’s Cable Management System Market study equips leaders with the forecast model, regulatory roadmap, supplier intelligence, and executable playbooks to make that choice with confidence. If your team is preparing a 2026 investment case — whether for R&D, capacity expansion, M&A, or channel development — the detailed segmentation, vendor shares, and Excel scenario models in the full report are designed to be the backbone of that decision.
To access the full datasets, segmentation tables, and our downloadable modelling toolkit, visit the report page where PW Consulting maintains the confidential deliverables that corporate strategists and procurement leads use to finalize 2026 commitments.
For detailed analysis of this topic, please visit the official page: Cable Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Gaming Mouse & Keyboards Market: Strategic Preview for 2026 Decision‑Makers
As gaming peripherals accelerate toward a new inflection point, executives and investors tasked with 2026 planning need a compact, strategy‑grade briefing that separates durable signals from industry noise. PW Consulting’s forthcoming Gaming Mouse & Keyboards Market study (base year 2025; forecast 2026–2032) consolidates five years of historical performance and a rigorous forecast built on a 6.98% compound annual growth rate (CAGR). This preview outlines the strategic value of that research for near‑term corporate decisions while preserving the granular segmentation and scenario outputs that drive competitive advantage—content intentionally reserved for the full report.
Gaming Mouse & Keyboards Market
Market Snapshot: Trajectory and Momentum
The market demonstrated steady expansion through 2020–2025 and closed 2025 as the research base year used throughout our analysis. Under PW Consulting’s central forecast, the sector continues to expand through 2026–2032 at a near‑7% CAGR, reflecting both product premiumization and widening adoption of advanced feature sets across casual and competitive gamer segments. The projected progression from the 2025 baseline to the 2032 horizon highlights a multi‑year runway for new product introductions, channel evolution, and supply chain repositioning.
Gaming Mouse & Keyboards Market
Why this study matters for 2026 decisions
- Timing of product investments: With clear growth momentum and technology cadence mapped through 2032, the report quantifies windows for high‑return product launches and when R&D investments will most likely translate to market share gains.
- Channel and pricing strategy: Our demand elasticity and price‑tier analysis enable CFOs and commercial leaders to test pricing scenarios for premium wireless offerings versus value‑oriented wired lines without exposing raw segment numbers in this preview.
- Supply chain and sourcing: The study converts macro regulatory shifts into procurement playbooks—showing when to hedge, when to lock multi‑year contracts, and where component redesigns mitigate critical‑material exposure.
- M&A and partnership targets: Concentration metrics and capability maps in the full report reveal which capability gaps are most valuable to fill through buyouts or strategic alliances.
Key growth drivers and structural trends
Several durable forces underpin the forecasted near‑7% CAGR. Technological miniaturization, latency reductions in RF and proprietary wireless protocols, and rising expectations around ergonomics and modularity are increasing per‑unit value. Simultaneously, the competitive gaming ecosystem continues to professionalize: esports revenue and viewership growth shift buying patterns toward feature‑rich, tournament‑grade peripherals, while an expanding base of casual gamers demands optimized value propositions.
Gaming Mouse & Keyboards Market
Material innovations and form‑factor experimentation—ultra‑light mice, low‑profile mechanical switches, and hybrid wireless/wired designs—are not fads but iterative responses to measurable user performance gains. The market is responding: leading vendors are layering differentiated sensor performance, switch technology, on‑device customization, and cloud‑backed firmware to lock in ecosystems and extend lifecycle revenue.
Supply chain, regulation, and geopolitical risk—what really changes in 2026
Regulatory developments around critical minerals and rare‑earth processing have moved from hypothetical risk to operational reality. A sequence of export controls, followed by temporary truces and evolving U.S. policy on processed critical minerals, has injected volatility into magnet and sensor supply lines that matter to wireless and haptic designs. These dynamics translate into several practical decisions for 2026:
- Accelerate dual‑sourcing and localized supplier development for magnets, precision switches, and high‑speed RF components.
- Invest in engineering alternatives—mechanical redesigns that reduce dependency on specific rare‑earth grades or allow substitution with compliant materials.
- Pursue inventory and contract structures that balance cost against time‑to‑market risk during peak product launches.
PW Consulting’s full analysis converts these regulatory signals into probabilistic scenarios—estimating cost‑delta impacts on BOM, marginal price pressure, and the timing of component scarcity. Those scenarios enable procurement and product teams to prioritize mitigations that protect roadmap commitments in 2026.
Competitive landscape: Who matters and why
Competition in 2026 is a blend of global platform incumbents, esports‑oriented specialists, and regional cost leaders. Market concentration is meaningful and persistent: the top three players together capture a majority of branded value, and the top five increase that share further—creating a market structure where scale, channel reach, and brand equity matter for premium segments, while agility and cost engineering open routes in value tiers.
Key firms monitored in the study include (representative profiles):
- Razer Inc. — Renowned for premium, lifestyle‑oriented peripherals with deep RGB ecosystems and low‑latency wireless options.
- Logitech International S.A. — Focused on ultra‑light wireless mice and cross‑device keyboard solutions that prioritize multi‑platform compatibility.
- Corsair Gaming, Inc. — Emphasizes high‑performance sensors, structural materials, and enthusiast‑grade keyboards and mice.
- SteelSeries ApS — Specializes in esports‑centric hardware with pro‑player input and precision‑first design philosophies.
- HyperX (HP Inc.) — Competes on durable, competitively priced products optimized for tournament play and streamers.
- ASUS ROG — Integrates co‑engineered peripherals with system platforms and pro gaming partnerships.
- Roccat, A4Tech, Rapoo, Genius, Mionix, Ducky, Omron — A mix of innovators, OEM suppliers, and component specialists that collectively broaden channel and price coverage.
Recent product activity through mid‑2026 underlines an industry pivot: new launches highlight carbon‑fiber and magnesium alloy constructions, ultra‑light 30–40g mice, and ultra‑wideband, low‑latency wireless keyboards. Component suppliers continue to play a decisive role—precision switches and sensors (including long‑life mechanical and Hall‑effect variants) are differentiators that directly influence warranty claims, perceived quality, and brand loyalty.
What this means for product and go‑to‑market strategies in 2026
From a product roadmap perspective, 2026 is the year to commit to a two‑prong strategy: deepen premium ecosystems while shoring up scalable, cost‑efficient lines. Practical moves include:
- Prioritizing wireless and hybrid variants in premium lines while maintaining high‑margin wired SKUs for value channels.
- Investing in firmware and cloud services to lock user profiles and cross‑device personalization—an increasingly potent source of recurring revenue.
- Designing modular product families where switch, shell, and sensor modules can be upgraded independently to extend product lifecycles and aftermarket revenue.
- Aligning esports sponsorships and pro collaborations with product release calendars to maximize visibility during competitive seasons.
Risk, scenarios, and decision frameworks
The full PW Consulting study presents three tested scenarios—Baseline, Disruption (supply constraint/regulatory tightening), and Acceleration (rapid premium adoption)—each with quantified impacts on margins, SKU profitability, and time‑to‑market. For 2026 planning, we recommend using these scenarios to stress‑test capital allocation, marketing spend, and inventory positions. Specific governance actions include establishing trigger points (component price thresholds, lead time expansions, tariff implementations) that automatically move teams from “monitoring” to “execute” modes.
What’s in the full report (operational highlights)
- Granular market sizing and forecast model (2020–2032) with downloadable datasets and sensitivity toggles.
- Segmented demand drivers by form factor, distribution channel, and user persona (detailed breakouts reserved for report subscribers).
- Supplier maps and critical‑material exposure matrices, with supplier scorecards and dual‑sourcing playbooks.
- Pricing optimization models and revenue impact simulations for alternate product mixes.
- Competitive benchmarking with feature‑level parity matrices and white space opportunity charts.
- M&A screening frameworks and an opportunities shortlist aligned to defensive and offensive growth strategies.
- Implementation checklists and 6‑, 12‑, and 24‑month tactical plans tailored to manufacturers, distributors, and OEM suppliers.
Closing guidance for leadership
2026 presents a window where firms that blend engineering excellence with supply‑chain resilience will outperform. The market’s mid‑single‑digit CAGR masks important asymmetries: premiumization is accelerating unit revenue in specific tiers even as value competition compresses margins elsewhere. Executives should prioritize actions that preserve roadmap velocity—chiefly, securing critical components, accelerating firmware and ecosystem investments, and using pro‑player launches to undergird premium product credibility.
This preview highlights the strategic contours you need to decide with confidence. For the full empirical backing, scenario outputs, and operational playbooks that translate this intelligence into executable plans, consult PW Consulting’s full Gaming Mouse & Keyboards Market report (base year 2025; forecast period 2026–2032). The complete study contains the granular segment and regional breakdowns, model workbooks, and supplier‑level intelligence that senior teams and boards rely on to make high‑stakes 2026 commitments.
For detailed analysis of this topic, please visit the official page: Gaming Mouse & Keyboards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Construction Chemicals to Top USD 101,500 Million by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-23
Construction Chemicals Market 2026: Strategic Outlook and Decision Playbook
Executive snapshot
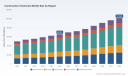
The global construction chemicals market has demonstrated steady expansion through the first half of the decade, rising from a base of roughly USD 50 billion in 2020 to an estimated USD 65.7 billion in 2025. Our forecasts — reflecting technology adoption, urbanization trajectories and infrastructure pipelines — project a continued compound annual growth rate (CAGR) of approximately 6.5% for the period 2026–2032, driving the market above USD 100 billion by 2032. For executives setting strategy in 2026, these topline dynamics matter: they create a multi-year window to scale profitable product platforms, reconfigure supply footprints, and capture share before the market mid‑cycle rebalances around new regulatory and raw-material regimes.
Construction Chemicals Market
Why this report changes 2026 decisions
- Actionable foresight, not just numbers: The research translates macro growth into decision-ready scenarios — from conservative to accelerated adoption — enabling capital-allocation choices that are defensible under multiple commodity and policy outcomes.
- Margin-first playbooks: The analysis prioritizes product and channel combinations that maintain margin resilience under raw-material inflation and should inform pricing and contract strategies for FY‑2026.
- Supply‑chain imperatives: With recent upstream tightness in key chemistries, the report offers supplier risk matrices and hedging frameworks tailored to construction‑chemical formulations.
- Regulatory and sustainability roadmaps: New product compliance requirements and green procurement curves are translated into product development roadmaps and commercialization timelines.
What the report contains — practical, operational chapters
This study was built with the practitioner in mind. Rather than a high-level narrative, it contains playbooks and executable modules designed for immediate adoption within 90–180 days by corporate strategy, commercial, R&D and supply‑chain teams.
Construction Chemicals Market
- Market model and forecast engine — an interactive baseline that maps demand drivers to revenue trajectories across 2026–2032, with scenario toggles for commodity price shocks and policy shifts.
- Value‑chain cost-to-serve analysis — componentized cost models for common product families, allowing rapid margin simulation under different raw-material sourcing assumptions.
- Segmentation and go‑to‑market playbooks — prioritized routes to market by customer-profitable cohorts, distributor strategies, and specification-influencing stakeholders.
- Regulatory compliance checklist — a practical compendium for new product registration, labelling, and the latest EU product regulation implications, including timelines and compliance cost estimates.
- Product innovation roadmap — R&D investment matrices highlighting formulation substitutions, low‑VOC/sustainable chemistries and retrofit-friendly systems with commercialization milestones.
- M&A and partnership playbook — target archetypes, valuation sensitivities, and integration checklists focused on capability gaps and regional access.
- Supplier-risk & sourcing playbook — supplier concentration heatmaps, continuity planning, and contract structures to reduce exposure to volatile commodity swings.
- Competitive benchmark pack — strategic profiles and tactical scorecards for leading vendors (product breadth, geographic strength, manufacturing footprint, and recent inorganic moves).
Competitive landscape — what the leading players are signaling
The market is shaped by a mix of global systems providers and regional specialists. Leading diversified chemical and building-materials groups maintain advantaged positions through broad product portfolios, specification relationships, and increasingly through strategic acquisitions and targeted capacity investments.
Construction Chemicals Market
- Sika AG remains the benchmark for integrated systems — strong in admixtures, waterproofing, adhesives and floor systems — and continues to compete on systems bundling and contractor-level technical support.
- BASF’s Master Builders Solutions has doubled down on manufacturing capacity in strategic geographies; recent U.S. expansions reflect a play to shorten lead times for admixtures and to service fast‑growing infrastructure projects.
- MAPEI and Pidilite are executing a differentiated strategy focused on trade channels, adhesive technologies and localized technical services, preserving margin through channel control.
- Dow, Arkema, Wacker and Nouryon play as upstream enablers: their specialty polymers and additives underpin many value-added formulations; volatility in their feedstocks can cascade into pricing for finished systems.
- Saint‑Gobain’s recent string of acquisitions has materially reshaped competitive positioning, particularly in waterproofing and emerging‑market distribution. The integration of targeted regional players accelerates its pathway to full-system offerings across geographies.
- RPM, GCP, Fosroc (now integrated into larger groups) and Chryso represent focused-play competitors — fast to market with technical innovations and agile commercial models to serve repair, retrofit and infrastructure niches.
Collectively, the top global players command a majority of market influence — creating a backdrop where scale, local service capability and formulation IP determine long-term winners.
Dynamics, headwinds and near-term shocks to plan for in 2026
- Raw‑material volatility: Recent months saw sharp movements in key precursors — from isocyanate derivatives to silicone intermediates and styrenic monomers — imposing margin compression unless mitigated by contracts or pass-through clauses.
- Regulation acceleration: New EU product compliance requirements and tightened green procurement rules are already affecting product portfolios and time-to-market. Firms that preempt compliance requirements will avoid costly reformulation sprints.
- Consolidation and local integration: Buyers are consolidating purchasing and favoring suppliers able to offer system-level warranties. Expect further M&A activity as global players seek to lock in distribution and specification channels in growth regions.
- Sustainability and specification shifts: Demand for low‑carbon, low‑VOC and circular‑material solutions is moving from niche to structural — a design requirement for many public tenders and large private developers.
Immediate strategic moves for 2026
Below are prioritized actions that we advise companies to implement within the next 12 months. These are practical, measurable, and aligned with the market trajectory reflected in our forecast.
- Embed scenario-based capital planning: Build three capital-allocation scenarios (base, stress, accelerate) that link capacity investments to commodity price thresholds and policy milestones.
- Protect margins with a two‑track commercial policy: adopt smarter contract clauses for pass-through pricing while piloting formulation changes that reduce reliance on the most volatile feedstocks.
- Accelerate product compliance readouts: dedicate a cross-functional rapid-response team to address new construction product regulations and tender-readiness for green specifications.
- Target bolt-on M&A in distribution and specification expertise: prioritize targets that close gaps in local technical service, standards certification and channel control rather than only incremental product lines.
- Implement supplier dual-sourcing for critical intermediates and negotiate inventory buffers tied to take-or-pay instruments to stabilize supply through 2026 shocks.
- Operationalize sustainability: integrate lifecycle benchmarking into product pricing and create a fast-track certification process to win public tender business that favors low‑carbon solutions.
How PW Consulting supports your 2026 agenda
Our Construction Chemicals Market study is more than a market map — it is a toolkit for execution. PW Consulting offers tailored modules to operationalize the report within your organization:
- Bespoke scenario modeling linked to your product portfolio and regional footprint.
- Targeted due diligence on acquisition candidates, including revenue synergy and integration playbooks.
- Supply-chain stress tests and raw-material hedging strategies with supplier ranking and negotiation scripts.
- R&D prioritization matrices to accelerate reformulation for regulatory and sustainability compliance.
- Commercial transformation plans to optimize distributor networks, specification penetration and pricing governance.
Next steps — where the full intelligence lives
This introduction outlines the strategic value executives can extract from a timely, operationally oriented study as they make pivotal 2026 decisions. The full report contains the granular datasets, chapter-level sensitivity tables, and company scorecards that will allow teams to convert strategy into a concrete 90‑day action plan. For organizations preparing board papers, capital requests or integration plans, accessing the complete dataset and playbooks is the next logical step.
Contact our team to schedule a briefing and to obtain the interactive forecast model and executable templates that will align your 2026 priorities with the market’s trajectory.
For detailed analysis of this topic, please visit the official page: Construction Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marine Steering Market to Reach USD 493M by 2032 at 4.94% CAGR
By pmarketresearch, 2026-07-23
Marine Steering System Market — Strategic Briefing for 2026 Decision-Makers
As shipyards, component manufacturers, fleet operators, and private-equity investors prepare their 2026 playbooks, clarity about the trajectory of the marine steering system market is no longer optional — it is mission critical. PW Consulting’s forthcoming research synthesizes historical performance, near-term inflection points and multi-scenario forecasts to translate macro trends into executable choices. This briefing highlights the strategic value of our study for 2026 decisions, previews the analytic depth contained in the full report, and flags the competitive and regulatory signals that will shape winners and losers — while intentionally withholding the report’s gated segment-level tables to preserve the incentive to access our complete intelligence.
Marine Steering System Market
Why this market matters in 2026
The marine steering system market is maturing: between 2020 and 2025 the industry expanded from roughly USD 277 million to about USD 352 million, reflecting a combination of fleet renewals, rising electrification and stronger aftermarket demand. Looking ahead, PW Consulting’s base-case projection anticipates a steady compound annual growth rate of approximately 4.94% through the 2026–2032 forecast window, with the total market approaching the mid-to-high hundreds of millions of dollars by 2032. That pace of growth is meaningful for manufacturers and investors because it is large enough to justify new product development, digital-service models and selective capacity investments — yet not so concentrated that scale alone guarantees margin protection.
Marine Steering System Market
Two structural features make this market strategically interesting in 2026:
Marine Steering System Market
- Fragmentation with opportunity: market concentration is low-to-moderate, implying both margin pressure from competition and opportunity for consolidation or differentiation. The top three players collectively account for a minority share of demand, and the top five likewise do not dominate — a dynamic that leaves room for focused entrants and M&A-driven scale plays.
- Technology and compliance are co-evolving: electrification, electro-mechanical steering, and integrated control systems are accelerating adoption, while classification societies and national regulators continue to refine expectations for hydraulic safety, materials and system redundancy. Companies that align product roadmaps with the regulatory baseline and deliver verifiable lifecycle economics will win procurement contests.
What the PW Consulting report delivers (operationally useful outputs)
Our full report is designed as a decision-useful toolkit for commercial and product leaders. Highlights include:
- Market-sizing & forecast engine — a transparent model that projects market demand under three scenarios (base, upside, downside) and supports bespoke sensitivity analysis for CAPEX and revenue planning.
- Go-to-market playbooks — segment-specific recommendations for OEMs, aftermarket specialists and system integrators, covering distribution models, warranty strategies and bundling of digital services.
- Product roadmap prioritization — scoring matrices that evaluate steering technologies (hydraulic, electro-hydraulic, electro-mechanical) against cost, reliability, serviceability, certification complexity and total cost of ownership for different vessel archetypes.
- Supply-chain risk matrix — supplier heatmaps, critical-material exposure (notably stainless steel and pressure-bearing components), single-source risks, and mitigation options including nearshoring and vendor qualification playbooks.
- Regulatory & standards impact assessment — actionable compliance checklists, certification timelines and engineering pre-acceptance requirements tailored to major flag states and classification societies.
- M&A and partnership screening — a prioritized target list and valuation sensitivity templates for buyers looking to consolidate capability (e.g., electrification stacks, autopilot integrations, or service-network scale).
- Commercial diligence artifacts — price benchmarking frameworks, margin waterfalls by product family, and contract templates for long-term maintenance and performance-based service agreements.
- Implementation tools — an executive dashboard, an ROI calculator for electrification investments, and a staged execution plan for migrating installed bases to hybrid or digital-steering platforms.
Note: the report’s full segment-level tables, regional splits and granular vessel-type revenue breakdowns are accessible on the report’s webpage; this briefing intentionally limits those tables to preserve the integrity of our gated analysis.
Competitive landscape — who to watch and why
The competitive field blends legacy hydraulics specialists, marine-electronics incumbents and agile regional suppliers. Key players profiled in our study include manufacturers with well-differentiated positioning:
- Kobelt Manufacturing (Canada) — a hydraulics and hybrid-systems stalwart with deep class-society certification experience. Their strength lies in full-system delivery across vessel classes and in-service support capabilities, which make them a logical partner for shipyards that demand proven reliability.
- Jefa Steering (Norway) — known for mechanical steering excellence and premium yacht-grade pedestals and autopilot drives. Jefa’s niche orientation and product quality support premium pricing and strong brand loyalty in leisure markets.
- Dometic Group (Sweden) — increasingly visible in electrification through new product launches and industry awards. Recent product introductions and recognition at major trade shows signal an aggressive push into electric steering for inboard and outboard applications, creating pressure on incumbents to match electrical integration and user ergonomics.
- Uflex USA — traditional helm and control-system supplier with strength in pleasure craft and light commercial segments; their catalog and distribution footprint make them a go-to for OEM retrofits and dealer networks.
- Hypro Marine & Deyuan Marine — specialists in heavy-duty hydraulic cylinders and full-systems for high-performance and commercial craft. Their technical focus on materials and cylinder reliability addresses the post-delivery maintenance economics that fleet operators monitor closely.
- Kawasaki Heavy Industries — a strategic player where large commercial and naval procurement favors labor-saving, IoT-enabled gear. Kawasaki’s unified E-series exemplifies a product strategy aimed at reducing onboard labor intensity and enabling remote monitoring.
- Damen Marine Components, Wills Ridley, Jastram, Glydus India — a mix of component integrators, commercial-steering suppliers and fast-follow regional brands. Glydus, for example, is actively showcasing patent-pending “Smart Steering” tech at industry trade venues, indicating that IP-driven differentiation is alive outside of traditional Western incumbents.
Recent market signals are instructive: Dometic’s late-2025 launch of an Optimus-series electric steering system and its recognition at IBEX demonstrate a near-term focal point of innovation — electrification that pairs ergonomic control with digital diagnostics. Meanwhile, trade-show activity from regional firms underscores the competitive pressure on price and feature parity in mature segments.
Regulatory and standards environment — operational implications
Regulatory updates and standards continue to shape product design and procurement timelines. Recent rulings and standards of note (summarized in our Dynamics chapter) relate to hydraulic steering safety arrangements, material-strength requirements for pressure-retaining components, and international standards that govern hydraulic steering design and testing. Practically, these developments translate into:
- Longer lead times for certification testing and documentation when introducing hydraulic or hybrid products;
- Engineering trade-offs between using higher-specification materials (which improve longevity and safety) and maintaining competitive unit economics;
- Procurement clauses that increasingly require documented compliance to specific regulations as a condition for tender award.
Strategic imperatives for executives in 2026
Based on the market trajectory and competitive dynamics, PW Consulting recommends executives prioritize the following strategic moves in 2026:
- Electrification-as-a-core-offering: Accelerate validated electric and electro-mechanical product lines for vessel classes where lifecycle economics and docking/household electrification justify the investment.
- Service-led monetization: Build aftermarket and subscription services (diagnostics, remote monitoring, preventive maintenance) to defend margins amid product commoditization.
- Modular platforms and certification roadmaps: Invest in modular architectures that reduce time-to-market across vessel types and front-load certification activities to shorten sales cycles for major accounts.
- Targeted partnerships and tuck-ins: Pursue bolt-on acquisitions and strategic alliances for sensor-integration, cybersecurity for onboard systems, and local assembly to reduce logistics exposure.
- Scenario-driven capacity planning: Use the report’s scenario engine to align capital expenditures with downside-protection triggers and upside scaling milestones.
How PW Consulting’s research accelerates your 2026 decisions
Our study is designed to convert market signals into decisions that can be implemented within 6–18 months. The combination of a transparent forecasting model, supplier-level diligence, regulatory compliance playbooks and commercial negotiation artifacts means your product, commercial and M&A teams can move from hypothesis to execution faster — with less trial-and-error.
To preserve the strategic value of our insights and to align with our “trailer” approach, this briefing surfaces the report’s analytic structure and executive takeaways while withholding gated segment tables and granular regional or vessel-type revenue splits. For procurement-ready price benchmarks, segment-level growth drivers, and supplier scorecards — all calibrated to the 2026 decision calendar — access the full Marine Steering System Market report on the PW Consulting portal.
Contact PW Consulting’s maritime practice for an executive briefing, a walkthrough of the forecast model, or a rapid commercial-diligence engagement tailored to your acquisition or product roadmap priorities.
For detailed analysis of this topic, please visit the official page: Marine Steering System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Auto Cylinder Sleeve Market USD 6.18B (2025) to USD 8.82B by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-23
Automobile Cylinder Sleeve Market — 2026 Strategic Preview
Preamble: why this preview matters
As OEMs, tier suppliers, investors and policy-makers prepare for critical allocation and capital decisions in 2026, a focused, evidence-backed view of the automobile cylinder sleeve market is indispensable. PW Consulting’s latest study — with a 2025 base year, a historical window covering 2020–2025 and a forecast horizon running through 2032 — synthesizes market sizing, technology trajectories, regulatory impact and supplier economics into a practical playbook. The market has expanded markedly in recent years (from roughly USD 3.7 billion in 2020 to about USD 6.18 billion in 2025) and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.2% over the 2026–2032 period, reaching an estimated USD 8.8+ billion by 2032. This preview highlights the strategic implications embedded in that growth path and helps leaders prioritize where to compete and how to allocate scarce engineering and capital resources in 2026.
Automobile Cylinder Sleeve Market
What corporate decision-makers will gain from this study
Our research translates market trends into actionable decisions across three strategic horizons:
Automobile Cylinder Sleeve Market
- Immediate (next 12 months): sourcing and supplier-risk mitigation — tactical levers to secure production continuity and control input-cost exposure.
- Near-term (12–36 months): product portfolio and manufacturing footprint decisions — which liner technologies and materials merit investment, scale-up or retirement.
- Medium-term (36–72 months): M&A, joint-development and business-model moves — options to consolidate capabilities, capture aftermarket value, or pivot toward advanced materials and coatings.
Market dynamics shaping 2026 choices
Several interlocking forces are determining where demand for cylinder sleeves will concentrate and how supply economics will evolve:
Automobile Cylinder Sleeve Market
- Regulatory tightening: Emissions and fuel-efficiency standards (for example, the most recent Euro and Bharat updates) are increasing engine thermal loads and service-interval expectations. That drives demand for liners with higher thermal fatigue resistance and dimensional stability — a non-negotiable requirement for OEM powertrain specifications.
- Material and manufacturing evolution: While traditional cast-iron solutions remain foundational for many engine programs, the industry is witnessing steady adoption of lightweight aluminum and composite alloys paired with thin-wall or cast-in liner approaches to meet vehicle-mass reduction targets. Concurrently, advanced casting and coating techniques (centrifugal casting, silicon-aluminum composites, specialized surface coatings) are improving running surfaces, heat transfer and friction characteristics.
- Engine portfolio mix and the electrification transition: The shift to electric vehicles reduces long-term growth potential for internal combustion components in some end-markets, but ICE powertrains remain the dominant installed base across many regions and vehicle classes for the forecast horizon. Strategic players must therefore balance investment in incremental ICE improvements (efficiency, durability) with hedged bets on adjacent technologies and aftermarket monetization.
- Supply-side concentration and competitive posture: The market is best described as moderately fragmented — a set of established global suppliers coexist with regional specialists and emerging material innovators. This structure creates both opportunities for scale-driven cost leadership and niches for differentiated technology plays.
- Raw-material and input-cost volatility: Steel, cast iron feedstock and specialized alloy inputs present periodic price swings. Manufacturers that lock supply, vertically integrate critical processes, or design material-agnostic platforms will gain margin resilience.
Technology and product trends to watch in 2026
Technological progress in the cylinder sleeve space is concentrated across three dimensions: materials, surface engineering and manufacturing methods. Key developments that will influence vendor selection and CAPEX decisions include:
- Advanced alloy formulations and composites that reconcile wear resistance with lower mass. Recent product introductions — for example, silicon-aluminum composite liners — demonstrate an industry pivot toward hybrids that retain performance while shaving weight.
- Surface coatings and micro-texturing that reduce friction and improve lubricant retention, enabling tighter combustion tolerances required by the newest emissions regimes.
- Centrifugal casting and patent-protected cast-in approaches that facilitate thin-wall liner integration with aluminum blocks, enabling OEMs to meet stringent fuel-economy targets without compromising durability.
For procurement and engineering teams, the implication is clear: qualification roadmaps must explicitly include coating vendors, manufacturing-process validation, and life-cycle testing regimes aligned with regulatory timelines.
Competitive landscape — what incumbents and challengers are doing
The sector’s competitive dynamic blends legacy OEM-tier incumbents, regional champions and material innovators. The following high-level positioning captures each firm’s strategic footprint and the implications for partnerships, supplier consolidation and customer lock-in:
- MAHLE GmbH (Stuttgart, Germany) — Strengths lie in in-house centrifugal cast cylinder liners tailored for passenger and commercial vehicle engines, including large-bore applications. Their emphasis on robust materials and low-wear running surfaces positions them as a go-to supplier for OEMs requiring validated production scalability and stringent OE specifications.
- Tenneco Inc. (Ann Arbor, USA) — Offers advanced liners with focus on optimized materials, coatings and designs that enhance heat transfer and reduce friction. Their breadth across light- and heavy-duty segments makes them a strategic partner for OEMs seeking platform-wide standardization of running-surface performance.
- TPR Co., Ltd. (Osaka, Japan) — Notable for patented cast-in liner technologies (e.g., AsLock®) and thin-wall wet/dry liners compatible with aluminum blocks, TPR is embedded in Japanese OEM supply chains and represents a model for tight OEM-supplier co-development.
- Kolbenschmidt GmbH (Frankfurt, Germany) — Integrates cylinder liners within a broader piston-system portfolio, emphasizing OE-grade performance and engineering alignment with piston and ring systems.
- Zhongyuan Cylinder Liner Company (China) & Aichi Machine Industry (Japan) — Regional players with competitive manufacturing scale and localized go-to-market advantages. They illustrate how regional supply flexibility and cost positioning influence OEM sourcing strategies.
Recent industry movements underline two strategic themes: product innovation and consolidation. New material launches (e.g., silicon-aluminum composite liners) and M&A moves among piston and liner specialists are compressing technology cycles and reducing time-to-qualification for advanced solutions. As consolidation continues in pockets, first-mover OEMs and suppliers that secure long-term development agreements will enjoy preferential access to technology roadmaps and capacity allocation.
Strategic implications and recommended actions for 2026
To convert market insight into defensible action plans, executives should prioritize the following:
- Define a clear material strategy: establish criteria for where traditional cast iron remains optimal vs. where lightweight alloys or composites deliver net lifetime value considering fuel-efficiency gains, warranty exposure and system-level weight targets.
- Lock in supplier partnerships with technology co-investment: move beyond transactional procurement toward joint development agreements that accelerate coating and casting validation while securing preferential capacity.
- Hedge raw-material exposure: implement layered procurement strategies that combine long-term contracts, strategic inventory buffers and flexible alloy sourcing to reduce input-cost-driven margin volatility.
- Rationalize production footprint using a hybrid model: retain strategic high-tech processes close to engineering centers while outsourcing volume casting to cost-efficient regional partners — but include strict quality oversight and inventory buffers for critical bore sizes.
- Pursue selective M&A or minority investments in material innovators and surface-coating specialists to accelerate access to next-generation solutions without fully internalizing R&D risk.
- Embed regulatory-forward testing protocols into product development cycles to ensure new liner designs meet evolving emissions and service-interval standards from day one.
- Develop aftermarket and service strategies: as ICE fleets remain sizable through the forecast window, aftermarket parts and reconditioning services present attractive, lower-capex revenue streams.
What the full report delivers (practical scope)
The full PW Consulting report translates the themes summarized above into instruments leaders can use immediately in 2026 planning cycles. Highlights include:
- Validated historical market sizing (2020–2025) and a transparent forecasting model covering 2026–2032, with scenario and sensitivity analyses centered on key variables (material adoption rates, regional demand shifts, regulatory stringency and input prices).
- Operationally relevant supplier benchmarking: production methods, quality certifications, capacity constraints, lead-times and commercial terms typically observed in OEM contracts.
- Risk and resilience maps: supplier-concentration heatmaps, single-source risk, and mitigation strategies suited to different corporate risk appetites.
- Technology deep dives and qualification roadmaps for incumbent and emerging liner types (including manufacturing process flowcharts, test protocols and cost-to-produce models).
- Go-to-market and M&A playbooks with prioritized target profiles, valuation heuristics, and integration checklists to accelerate deal execution.
To preserve the strategic value of the full analysis and models, we have intentionally withheld granular segment-by-segment numerical breakdowns in this preview. The full dataset — including detailed regional and application splits, supplier market-shares and price curve assumptions — is accessible via the PW Consulting portal and is the recommended input for finalizing 2026 capital and sourcing decisions.
Concluding note — navigating 2026 with clarity
The cylinder sleeve market’s trajectory through the next funding and product-development cycles is shaped by modest, steady growth (CAGR ~5.2%), evolving materials science, regulatory tightening and a supplier landscape that rewards both scale and specialization. For executives, the near-term imperative is to embed flexibility into sourcing and product portfolios, secure co-development arrangements with technology leaders, and use scenario-driven forecasting to protect margins against material-price and regulatory shocks. PW Consulting’s full report provides the numerical granularity, supplier-level intelligence and executable roadmaps to convert these strategic priorities into measurable 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Automobile Cylinder Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Trans-Resveratrol Market to Reach USD 151.9M by 2032 at 8.9% CAGR
By pmarketresearch, 2026-07-23
Trans-Resveratrol Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused strategic primer on the trans‑resveratrol market built to inform boardroom decisions in 2026. This preview synthesizes our deep quantitative modelling (base year 2025, historical window 2020–2025, forecast 2026–2032) and primary‑vendor interviews into a compact, decision‑oriented narrative. The market is demonstrating healthy expansion—our modelling shows mid‑to‑high single‑digit compound annual growth (CAGR 8.9%) from the 2025 base—making 2026 a pivotal year for choices that will determine whether companies capture upside or become cost‑exposed by 2028–2030 dynamics.
Trans Resveratrol Market
Why this report matters for 2026
- Timing of strategic moves: With the market at an inflection point, procurement, product development, and M&A windows are narrow. Choices made in 2026 will compound materially across the 2026–2032 forecast horizon.
- Risk versus opportunity: Demand growth is steady and predictable, but raw‑material pressure and supply‑side consolidation risks are accelerating—requiring integrated risk management across sourcing, formulation and commercialization.
- Value creation levers: Optimization is available through formulation differentiation, supply‑chain integration, and selective partnerships with producers of fermentation and botanical extracts.
Market trajectory—what the headline numbers tell us
By our model the trans‑resveratrol market achieved a meaningful scale in 2025 and is projected to expand substantially through 2032 at a CAGR of 8.9%. This pace implies a material increase in commercial demand for both high‑purity ingredients and tailored delivery systems, with implications for raw material sourcing, manufacturing scale‑up, and regulatory positioning. For organizations evaluating capital allocation in 2026, the forecast horizon offers a clear revenue growth runway—but also a clear need to balance growth investments with supply‑chain resilience.
Trans Resveratrol Market
Report contents — actionable modules included
The full PW Consulting market study is designed as an operational playbook for executives. Key modules include:
Trans Resveratrol Market
- Market sizing and trend modelling calibrated to 2025 as the base year and extending to 2032, with scenario trees that stress test demand against macroeconomic and supply shocks.
- Buy‑side decision frameworks for procurement and inventory policy under volatile feedstock availability.
- Technology and formulation playbooks: fermentation, plant extraction, and synthetic pathways—advantages, CAPEX/OPEX profiles, and suitability to product claims (e.g., nutraceutical vs cosmetic uses).
- Commercial go‑to‑market templates: pricing strategies, co‑marketing partnership clauses, and private label vs branded positioning.
- Due diligence checklists for M&A and strategic partnerships, including integration scorecards for supply, regulatory, and IP risk.
- Regulatory and claims matrix per major jurisdiction, and a compliance checklist for speeding time‑to‑market.
The above modules are paired with decision-support tools (interactive dashboards and scenario calculators) so commercial and procurement leaders can quantify tradeoffs instantly—however, detailed segment share tables and granular regional splits are reserved for the full report to preserve competitive value.
Market dynamics to watch in 2026
- Feedstock signals are mixed: Recent agricultural reports reveal a notable contraction in grape crush volumes in major producing regions alongside softened average prices per ton. The net effect is a split pricing signal: reduced availability of grape‑skin and pomace streams used for botanical extraction, even as raw grape prices show downward pressure in some vintages. Separately, local county datasets document pockets of tighter utilization and unsold tonnage—a sign that regional logistics and harvest economics are becoming as important as aggregate tonnage figures.
- Strategic capital moves among suppliers: Leading ingredient producers are reallocating capital and optimizing balance sheets. Notably, a major supplier completed a sizeable share buyback program in late 2025 and signalled further structural measures to enhance supply‑chain resilience in early 2026. Expect more financial‑engineering and vertical‑integration initiatives from tier‑one suppliers as they seek predictable revenue streams and margin protection.
- Fragmented supply base: While demand is growing, supplier concentration remains relatively low—creating both flexibility and fragmentation risk. Buyers who move early to secure offtake, co‑development, or exclusivity arrangements will gain negotiating leverage as competition for high‑quality, high‑purity material intensifies.
Competitive landscape — positioning and strategic implications
We profiled the market’s core suppliers to map likely competitive moves and partnership fit. Below are the distilled strategic profiles and what they mean for market participants seeking suppliers or partners in 2026.
- dsm‑firmenich (Europe/Switzerland): A clear leader in high‑potency, nature‑identical trans‑resveratrol offerings with a branded high‑purity product. Their recent capital actions imply a stronger emphasis on supply‑chain continuity and selective premium partnerships. For firms seeking validated, pharma‑grade quality and co‑branding opportunities, they are a preferred anchor—but access may be rationed for strategic partners.
- Evolva / Danstar Ferment (Switzerland): Specializes in fermentation‑derived material with very high purity. Their fermentation pathway offers scale advantages and shorter lead times versus botanical extraction, making them attractive for companies prioritizing GMP continuity and traceable sourcing. Expect competitive pricing pressure if fermentation capacity is further scaled.
- Sabinsa, Verdure Sciences, Maypro, Layn, JF Natural (U.S.-centric portfolio players): These suppliers focus on standardized extracts, powders and delivery systems tailored for nutraceutical and wellness formulations. Their strengths are formulation support, co‑marketing, and rapid commercialization—ideal for consumer goods firms that need turnkey solutions rather than raw bulk supply.
- Chengdu Yazhong Bio‑pharmaceutical & Laurus Labs (APAC manufacturers): These vendors offer pharmaceutical‑grade products and bulk ingredients that can support API and large‑volume supplement production. They are strategic for contract manufacturers or companies seeking cost‑competitive bulk supply, but buyers must validate regulatory alignment for target markets.
- Longevir (EU wholesale): Specializes in GMP‑compliant bulk from botanical sources. They can be a pragmatic partner for regional scale‑ups where traceability of botanical origin is a differentiator.
Across these profiles, two sourcing archetypes emerge for 2026: (1) premium, brand‑led partnerships focused on validated high‑purity ingredients and co‑development; (2) cost‑efficient bulk supply with scale advantages where regulatory alignment and QC systems are the gating factors.
Strategic plays for executives in 2026
- Lock in blended sourcing: Combine fermentation and botanical supply contracts to balance pricing, traceability, and availability. Negotiate staggered offtake and volume options tied to quality milestones to retain flexibility.
- Invest in formulation differentiation: Prioritize delivery systems and claim‑supporting clinical evidence. Small incremental improvements in bioavailability or taste masking yield outsized commercial returns in supplements and cosmetics categories.
- Expand supplier due diligence: Elevate supplier audits to include vineyard and processing traceability where botanical feedstocks are used, and require GMP and third‑party purity certificates for all fermentation partners.
- Evaluate M&A and JV opportunities: Consider minority investments in fermentation capability or toll‑manufacturing partnerships to secure preferential capacity without full CAPEX commitment.
- Hedge agricultural exposure: Where botanical sourcing is material, adopt multi‑year contracts indexed to defined price bands or invest in co‑operative collection agreements to capture pomace streams that would otherwise be lost.
Decision frameworks and next steps
For 2026, the practical decision framework is simple but rigorous: (1) quantify your 36–60 month demand curve under base, upside and stress scenarios; (2) map supply options to those scenarios by cost, lead time, quality and regulatory fit; (3) prioritize actions that simultaneously secure supply and enable premiumization (e.g., clinical studies, proprietary delivery formats); (4) execute a small set of binding agreements (offtake, JV, or strategic equity) that align incentives with critical suppliers.
PW Consulting’s full report provides the scenario matrices, supplier scorecards, and an interactive procurement calculator that makes step (2) operational in a single executive workshop. The granular segment tables and regional breakdowns that underpin the scorecards are intentionally omitted from this preview to preserve proprietary intelligence—and are available in the full study.
Conclusion — where to invest focus in 2026
The trans‑resveratrol market presents a clear growth runway. But the path to profitable scale requires active management of supply variability, priority access to high‑purity sources, and investments in product differentiation. Companies that treat 2026 as a year for securing supply optionality and investing in defendable product attributes will convert the mid‑single‑digit CAGR into sustainable, differentiated revenue streams across the remainder of the forecast window.
To access the full dataset, supplier scorecards, and customizable decision tools that underpin these conclusions, request the PW Consulting Trans‑Resveratrol Market report. Our team stands ready to run a tailored 90‑day strategic sprint to align your 2026 action plan with the scenarios that matter most to your business.
For detailed analysis of this topic, please visit the official page: Trans Resveratrol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Military Antenna Market - USD 4,000M in 2025, Poised for 5.6% CAGR
By pmarketresearch, 2026-07-23
Military Antenna Market — 2026 Strategic Primer for C-Suites and Procurement Leads
As PW Consulting’s lead industry analyst, I present a condensed, high-impact briefing designed to orient executive teams and procurement leaders ahead of critical 2026 decisions. Our full Military Antenna Market study (base year 2025, forecast 2026–2032) combines quantitative forecasting, supplier due diligence, and decision-ready playbooks. This primer highlights the strategic choices that matter most in 2026 — what to watch, where value will be captured, and how to convert market signals into defensible actions. The summary intentionally demonstrates our analytical depth while withholding proprietary segmentation detail to direct readers to the full report for transaction-grade intelligence.
Military Antenna Market
Market Snapshot: Macro Picture You Need to Know
By the 2025 base year the military antenna market had matured into a multi‑billion dollar sector, with our model estimating a market size of approximately USD 4.0 billion. Under current demand and supply dynamics, we forecast a compound annual growth rate (CAGR) of 5.6% through 2032, a trajectory that drives the market to the mid‑single‑billion range by the end of the forecast horizon. Two structural characteristics are particularly important for 2026 planning: first, the market remains moderately fragmented (top-three firms do not dominate), and second, growth is being fueled by cross-cutting technology trends — advanced phased arrays, anti‑jamming PNT, and airborne/space connectivity — that cut across classic frequency and platform boundaries.
Military Antenna Market
Why 2026 Is an Inflection Point
- Regulatory recalibration: Changes to export control regimes in 2025 — including adjustments to the treatment of certain controlled reception pattern antennas — have begun to alter customer procurement timelines, partner selection, and the viability of cross‑border supply relationships. Expect a transitional 12–18 month window where compliance strategies materially affect go‑to‑market timing.
- Technology squeeze points: Adoption of GaN-based RF front ends and the migration to complex phased-array architectures are colliding with limited foundry and trusted‑source packaging capacity. Component supply pressure is real and will meaningfully influence lead times and price volatility in 2026.
- Operational tempo and program wins: Renewal and expansion of naval and airborne electronic warfare programs, plus accelerating demand for resilient UAV connectivity, are increasing procurement volume. Public contract awards and qualification milestones in 2024–2025 signal procurement windows opening in 2026 — a known opportunity for late movers with capability but a compliance gap.
- Geopolitical trade instruments: Tariff regimes and sovereign procurement preferences continue to stress global supply chains, prompting buyers to weigh onshore vs trusted offshore sourcing more explicitly than in past cycles.
Actionable Themes from the Full Report
Our full study contains operationally focused modules intended for direct use by strategy, procurement, and BD teams. Highlights include:
Military Antenna Market
- Scenario-driven demand forecasts (2026–2032) with sensitivity to regulatory shocks, component constraints, and defense spending cycles.
- Supplier heatmaps and trust‑score frameworks that evaluate technical capability, production agility, export exposure, and financial health — built to support shortlist decisions and dual‑sourcing design.
- Procurement playbook templates: RFP language, qualification checklists, test protocols (including environmental and EMI/EMC benchmarks), and contract clauses to manage IP and export compliance.
- Unit cost models and total cost of ownership (TCO) calculators for common antenna classes to support trade‑off analyses between custom designs, COTS variants, and licensed solutions.
- Technology roadmaps that map investment timing (GaN, digital beamforming, low SWaP SATCOM apertures) to near‑term procurement opportunities and longer‑term platform modernizations.
- Supply‑chain resilience playbook: trusted‑source strategies, inventory hedging approaches, and preferred partnership structures for wafer, packaging, and RF module dependencies.
- M&A and JV canvases, with criteria for bolt‑on targets and capability integration plans to accelerate entry into high‑growth application niches.
Competitive Landscape: What the Market Signals Mean
The competitive set is diverse, composed of specialist antenna manufacturers, systems integrators, and legacy aerospace players. Key observations:
- Hascall‑Denke (USA): A go‑to specialist for defense antenna manufacturing and procurement channels. Recent government contract awards demonstrate their continued reliability as a prime supplier for stocked military items; useful as a partner when speed‑to‑shelf and logistics pedigree matter.
- Mobile Mark, Inc. (USA): Strong in adaptable solutions that bridge commercial wireless standards and dedicated defense frequencies. Their capability to address both legacy frequency bands and bespoke military allocations makes them a pragmatic partner for bridging COTS and custom requirements.
- Antenna Products Corporation (USA): Known for end‑to‑end design and manufacture for military and government use. They are positioned as a systems supplier for buyers seeking integrated antenna system contracts rather than component buys.
- Dayton‑Granger (USA): Offers specialized protection solutions (electrostatic, lightning) for airborne platforms, making them a differentiated supplier for airframe integration programs.
- Southwest Antennas (USA) and Antenna Experts (India): Both provide high‑performance RF/microwave and wideband designs, each with strengths in custom manufacturing — a fit for programs requiring rapid prototyping and small series production.
- Shakespeare Company (USA) and Trival Antene (France): Niche capabilities in VHF/UHF and robust mast systems for HF/VHF applications; their heritage in legacy bands makes them relevant where interoperability with older platforms is required.
- MTI Wireless Edge (Israel): Growing presence in high‑power omnidirectional and airborne anti‑jam systems; recent contract wins validate their relevance in UAV and tactical anti‑jam applications.
Recent vendor developments — public contracts and facility expansions by both prime contractors and specialized vendors — underscore that 2026 procurement windows will emphasize certified supply, proven test records, and export‑control readiness. Our competitive matrices in the full report map these developments to recommended engagement strategies for suppliers and buyers.
Strategic Implications: Tactical Moves for 2026
Based on our analysis, firms that act quickly with clarity on the following will secure the best outcomes:
- Prioritize export‑control mapping as a core competency. Changes in 2025 require legal/technical integration into procurement and sales planning — don’t treat compliance as a paperwork exercise.
- Hedge component risk by qualifying multiple GaN and trusted‑packaging sources. Lead times and price spikes are realistic; manage them through contractual options and inventory strategies.
- Adopt a modular product strategy. Modular, software‑defined antenna architectures enable incremental upgrades and ease integration under diverse platform constraints.
- Pursue selective partnerships with proven integrators to move from prototype to qualification quickly. Recent multi‑orbit qualification activity demonstrates the commercial value of being first to certify.
- Deploy a two‑track procurement posture: immediate buys to meet near‑term program needs (leveraging stocked items and qualified suppliers) and medium‑term investments (R&D, capacity rights) to capture the innovation premium.
- Consider localized manufacturing or trusted‑sourcing agreements for sensitive programs to reduce sovereign procurement friction and mitigate tariff exposure.
90/180/365 Day Roadmap — How to Convert Insight into Action
- 0–90 days: Complete a supplier stress test (capacity, export exposure, technical certifications), lock short‑term inventory positions for critical RF components, and begin RFPs with export‑aware clauses.
- 90–180 days: Finalize dual‑source contracts for high‑risk components, initiate co‑development agreements with niche antenna specialists, and commence qualification testing aligned with target platform timelines.
- 180–365 days: Execute onshore/nearshore capacity options where required, close M&A or JV opportunities that provide missing capabilities, and roll out the first modular antenna prototypes into platform trials.
Closing: Where PW Consulting Adds Immediate Value
For 2026, the strategic battleground in military antennas will be defined less by raw demand and more by who can manage complexity: export controls, constrained component ecosystems, and multi‑domain certification timelines. PW Consulting’s full Military Antenna Market report moves beyond headline forecasts to provide the executable tools procurement and business leaders need — supplier heatmaps, compliance playbooks, TCO models, and a prioritized action roadmap. These are the instruments that convert a forecast into competitive advantage.
To access the full intelligence suite, including our granular segmentation models, supplier scoring spreadsheets, and RFP templates, visit the PW Consulting Military Antenna Market page. The preview you’ve just read is purposely high‑signal and selectively redacted — the full report contains the transaction‑grade detail executives rely on for 2026 strategic commitments.
For detailed analysis of this topic, please visit the official page: Military Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gel Documentation Market to Reach USD 490M by 2032 at 5.45% CAGR
By pmarketresearch, 2026-07-23
Gel Documentation Systems Market — Strategic Outlook for 2026 Decision Makers
As laboratories, biotechs, and diagnostics providers prepare strategic budgets and product roadmaps for 2026, firms face a deceptively simple choice: treat gel documentation systems as a routine capital purchase, or reposition them as a strategic node that influences R&D velocity, regulatory readiness, and downstream service revenues. PW Consulting’s new market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) quantifies that the global gel documentation market stood at USD 337.0 Million in 2025 and, at a compound annual growth rate of 5.45%, is projected to approach USD 490.0 Million by 2032. This briefing distils the implications of that trajectory for firms making decisions in 2026 without disclosing the granular segmentation that drives our proprietary model — those details are reserved for subscribers and the full report.
Gel Documentation Systems Market
Why this report matters for 2026 planning
-
Shift from commoditised hardware to systems-level value: The market expansion is not uniform across suppliers or use cases. What used to be a buyer’s market for standalone imaging boxes is evolving into a market for systems that bundle hardware, cloud-enabled analysis, and compliance-ready data management. Procurement teams that ignore software and lifecycle services risk higher total cost of ownership and slower compliance turnaround.
Gel Documentation Systems Market -
Regulation and lab accreditation are forcing structural purchases: With increasing emphasis on ISO 17025 and laboratory quality assurance, organizations must prioritize imaging solutions that provide auditable, tamper-evident records and validated workflows. The pace of purchases in 2026 will be driven as much by regulatory calendars as by pure R&D demand.
Gel Documentation Systems Market -
Supply-chain fragility impacts timing and cost: Persistent semiconductor bottlenecks and logistics constraints remain a near-term risk to equipment manufacturers and purchasers alike. Organizations should expect elongated lead times and price volatility for certain imaging components, influencing CAPEX scheduling and inventory strategies.
What the market trajectory implies for strategy
-
Opportunity in adjacent services: As pricing competition compresses margins on entry-level instruments, higher-margin opportunities emerge in software licenses, analytic modules, maintenance contracts, and cloud-based data workflows. Companies that build or partner for analytics and compliance modules can capture recurring revenue and lock-in labs through validated workflows.
-
Product roadmap reorientation: Vendors should prioritize modular platforms that support multi-mode imaging (fluorescence, chemiluminescence, visible light) and scale across lab types. R&D investment should be balanced between optics/electronics and user-facing analytics — buyers value reproducibility and easy integration with lab information systems as much as raw resolution.
-
M&A and consolidation vectors: The current market concentration suggests leading players command meaningful share but gaps remain for specialized or regional challengers. Expect continued consolidation around software, AI analytics, and service ecosystems rather than pure hardware, as acquirers seek to accelerate time-to-market for validated end-to-end solutions.
Competitive landscape — who shapes buyer choices
The competitive set includes established life-science OEMs and several specialized imaging vendors. Each brings differentiated propositions that matter for procurement committees:
-
Bio‑Rad Laboratories (Hercules, CA) — Known for systems such as GelDoc Go and GelDoc XR+ and integrated Image Lab software; recent product launches incorporate AI-assisted analysis, signalling a push to embed advanced image interpretation into routine workflows.
-
Thermo Fisher Scientific (Waltham, MA) — Offers the iBright family and automated gel documentation solutions aimed at throughput and workflow automation in research and QC environments.
-
GE HealthCare (Chicago, IL) — Positions imaging platforms as part of broader diagnostic and electrophoresis documentation pathways, emphasizing precise quantification for regulated settings.
-
Syngene (Cambridge, UK), Analytik Jena (Jena, Germany), Cleaver Scientific (UK), LI‑COR Biosciences (Lincoln, NE), Vilber Lourmat (France), Azure Biosystems (Dublin, CA), ATTO Corporation (Tokyo), Major Science (USA) — Each offers niche strengths from compact, budget-conscious instruments to quantitative, publication-grade imagers with integrated analysis suites.
Collectively, the three largest firms capture a clear majority of market share, and the top five increase that concentration further — a dynamic that has important implications for pricing discipline, channel strategies, and partnership negotiation leverage.
Recent developments to watch
-
AI-enabled image analysis: One leading vendor launched an AI-infused imaging system in 2025 that automates band recognition and quantification, setting a new benchmark for end-user expectations on analysis speed and objectivity. Vendors who do not accelerate software capabilities risk relegation to price competition.
-
Quality and compliance enforcement: Regulators and accreditation bodies have amplified expectations for auditable imaging and data retention. Equipment that supports secure, validated workflows will command premium consideration during procurement.
-
Component availability constraints: Continued semiconductor and logistics issues mean manufacturers must design supply-resilient architectures and transparent lead-time commitments into 2026 purchasing plans.
Report contents — what PW Consulting delivers (practical, actionable elements)
This study is designed for C-suite executives, product leaders, procurement heads, and corporate development teams who need to make material decisions in 2026. The full report includes:
-
A top-down market model (historical and forecast) with sensitivity testing and scenario outputs that stress-test growth assumptions under alternative regulatory, supply-chain, and innovation scenarios.
-
Demand-side segmentation by region, product type, light source, detection technique, application, and end-user — modelled with a transparent methodology and accompanied by heat maps that expose pockets of accelerated adoption. (Note: granular segment figures are contained in the full report.)
-
Buyers’ decision framework — procurement checklists, TCO comparators, validation and qualification KPIs, and vendor evaluation scorecards tailored for ISO-compliant labs.
-
Competitive benchmarking — feature-function matrices, software capability scoring, post-sales service metrics, channel and pricing strategies, and patent/technology mapping to identify white-space and defensive plays.
-
M&A and partnership playbook — target screening criteria, premium drivers, integration pitfalls, and a short-list of strategic acquisition archetypes that make sense in a concentrated market.
-
Supply-chain and manufacturing risk assessment — component exposure analysis and recommended mitigation strategies including dual-sourcing, buffer inventory guidelines, and design adjustments to reduce semiconductor dependency.
-
Implementation roadmaps for buyers and vendors — from pilot selection to validation to scale-up, including templates for proof-of-concept, data migration, and change-management to ensure adoption and regulatory acceptance.
How to use the insights in 2026 decision cycles
-
For equipment buyers — integrate software and compliance criteria into total cost evaluations. Push vendors for roadmap commitments on analytics and validated workflows; consider multi-year service agreements that cap maintenance uncertainty from supply constraints.
-
For product and R&D leaders — prioritize modular, software-centric development. Investing in reproducible analytics and audit trails delivers differentiable value far faster than incremental hardware upgrades alone.
-
For corporate development teams — assess acquisition targets that accelerate analytics or offer sticky service models. Valuation premiums will accrue to businesses that can demonstrate recurring revenues and validated compliance footprints.
-
For operations and procurement — implement lead-time buffers for critical components and qualify alternative suppliers. Negotiate supply contracts with explicit clauses for capacity allocation during disruptions.
What this analysis does not reveal — and why
In line with our “preview” approach, this article purposefully omits the granular segmentation figures and region/application-specific shares that underpin our market model. Those detailed data points — the specific breakdowns by region, product family, light source, detection technique, application, and end-user — are part of the full PW Consulting package and are essential for precise target-setting, budgeting, and deal negotiation. The summary above presents the strategic contours and executable recommendations you need to prioritize decisions in 2026; the full dataset converts those priorities into tactical actions and quantified roadmaps.
Final recommendations — three moves to make in 2026
-
Adopt a systems mindset: Treat gel documentation procurement as a multi-year capability build (hardware + software + compliance), not a one-off equipment purchase.
-
Prioritise analytics and validation: Allocate R&D and purchasing budgets toward solutions that reduce hands-on image processing and increase reproducibility for regulated workflows.
-
De-risk the supply chain: Lock in critical component supply and test alternative configurations now to avoid CAPEX delays and price spikes later in the forecast window.
For decision-makers preparing capital and product roadmaps in 2026, PW Consulting’s full Gel Documentation Systems Market report provides the actionable data and methodological transparency needed to convert strategic intent into measurable outcomes. Contact our research team to access the complete segmentation tables, downloadable financial model, and a tailored briefing for your organisation.
For detailed analysis of this topic, please visit the official page: Gel Documentation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com