

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
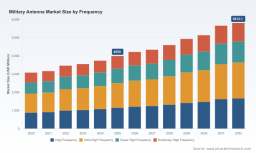
PW Consulting: Military Antenna Market - USD 4,000M in 2025, Poised for 5.6% CAGR

Military Antenna Market — 2026 Strategic Primer for C-Suites and Procurement Leads
As PW Consulting’s lead industry analyst, I present a condensed, high-impact briefing designed to orient executive teams and procurement leaders ahead of critical 2026 decisions. Our full Military Antenna Market study (base year 2025, forecast 2026–2032) combines quantitative forecasting, supplier due diligence, and decision-ready playbooks. This primer highlights the strategic choices that matter most in 2026 — what to watch, where value will be captured, and how to convert market signals into defensible actions. The summary intentionally demonstrates our analytical depth while withholding proprietary segmentation detail to direct readers to the full report for transaction-grade intelligence.
Military Antenna Market
Market Snapshot: Macro Picture You Need to Know
By the 2025 base year the military antenna market had matured into a multi‑billion dollar sector, with our model estimating a market size of approximately USD 4.0 billion. Under current demand and supply dynamics, we forecast a compound annual growth rate (CAGR) of 5.6% through 2032, a trajectory that drives the market to the mid‑single‑billion range by the end of the forecast horizon. Two structural characteristics are particularly important for 2026 planning: first, the market remains moderately fragmented (top-three firms do not dominate), and second, growth is being fueled by cross-cutting technology trends — advanced phased arrays, anti‑jamming PNT, and airborne/space connectivity — that cut across classic frequency and platform boundaries.
Military Antenna Market
Why 2026 Is an Inflection Point
- Regulatory recalibration: Changes to export control regimes in 2025 — including adjustments to the treatment of certain controlled reception pattern antennas — have begun to alter customer procurement timelines, partner selection, and the viability of cross‑border supply relationships. Expect a transitional 12–18 month window where compliance strategies materially affect go‑to‑market timing.
- Technology squeeze points: Adoption of GaN-based RF front ends and the migration to complex phased-array architectures are colliding with limited foundry and trusted‑source packaging capacity. Component supply pressure is real and will meaningfully influence lead times and price volatility in 2026.
- Operational tempo and program wins: Renewal and expansion of naval and airborne electronic warfare programs, plus accelerating demand for resilient UAV connectivity, are increasing procurement volume. Public contract awards and qualification milestones in 2024–2025 signal procurement windows opening in 2026 — a known opportunity for late movers with capability but a compliance gap.
- Geopolitical trade instruments: Tariff regimes and sovereign procurement preferences continue to stress global supply chains, prompting buyers to weigh onshore vs trusted offshore sourcing more explicitly than in past cycles.
Actionable Themes from the Full Report
Our full study contains operationally focused modules intended for direct use by strategy, procurement, and BD teams. Highlights include:
Military Antenna Market
- Scenario-driven demand forecasts (2026–2032) with sensitivity to regulatory shocks, component constraints, and defense spending cycles.
- Supplier heatmaps and trust‑score frameworks that evaluate technical capability, production agility, export exposure, and financial health — built to support shortlist decisions and dual‑sourcing design.
- Procurement playbook templates: RFP language, qualification checklists, test protocols (including environmental and EMI/EMC benchmarks), and contract clauses to manage IP and export compliance.
- Unit cost models and total cost of ownership (TCO) calculators for common antenna classes to support trade‑off analyses between custom designs, COTS variants, and licensed solutions.
- Technology roadmaps that map investment timing (GaN, digital beamforming, low SWaP SATCOM apertures) to near‑term procurement opportunities and longer‑term platform modernizations.
- Supply‑chain resilience playbook: trusted‑source strategies, inventory hedging approaches, and preferred partnership structures for wafer, packaging, and RF module dependencies.
- M&A and JV canvases, with criteria for bolt‑on targets and capability integration plans to accelerate entry into high‑growth application niches.
Competitive Landscape: What the Market Signals Mean
The competitive set is diverse, composed of specialist antenna manufacturers, systems integrators, and legacy aerospace players. Key observations:
- Hascall‑Denke (USA): A go‑to specialist for defense antenna manufacturing and procurement channels. Recent government contract awards demonstrate their continued reliability as a prime supplier for stocked military items; useful as a partner when speed‑to‑shelf and logistics pedigree matter.
- Mobile Mark, Inc. (USA): Strong in adaptable solutions that bridge commercial wireless standards and dedicated defense frequencies. Their capability to address both legacy frequency bands and bespoke military allocations makes them a pragmatic partner for bridging COTS and custom requirements.
- Antenna Products Corporation (USA): Known for end‑to‑end design and manufacture for military and government use. They are positioned as a systems supplier for buyers seeking integrated antenna system contracts rather than component buys.
- Dayton‑Granger (USA): Offers specialized protection solutions (electrostatic, lightning) for airborne platforms, making them a differentiated supplier for airframe integration programs.
- Southwest Antennas (USA) and Antenna Experts (India): Both provide high‑performance RF/microwave and wideband designs, each with strengths in custom manufacturing — a fit for programs requiring rapid prototyping and small series production.
- Shakespeare Company (USA) and Trival Antene (France): Niche capabilities in VHF/UHF and robust mast systems for HF/VHF applications; their heritage in legacy bands makes them relevant where interoperability with older platforms is required.
- MTI Wireless Edge (Israel): Growing presence in high‑power omnidirectional and airborne anti‑jam systems; recent contract wins validate their relevance in UAV and tactical anti‑jam applications.
Recent vendor developments — public contracts and facility expansions by both prime contractors and specialized vendors — underscore that 2026 procurement windows will emphasize certified supply, proven test records, and export‑control readiness. Our competitive matrices in the full report map these developments to recommended engagement strategies for suppliers and buyers.
Strategic Implications: Tactical Moves for 2026
Based on our analysis, firms that act quickly with clarity on the following will secure the best outcomes:
- Prioritize export‑control mapping as a core competency. Changes in 2025 require legal/technical integration into procurement and sales planning — don’t treat compliance as a paperwork exercise.
- Hedge component risk by qualifying multiple GaN and trusted‑packaging sources. Lead times and price spikes are realistic; manage them through contractual options and inventory strategies.
- Adopt a modular product strategy. Modular, software‑defined antenna architectures enable incremental upgrades and ease integration under diverse platform constraints.
- Pursue selective partnerships with proven integrators to move from prototype to qualification quickly. Recent multi‑orbit qualification activity demonstrates the commercial value of being first to certify.
- Deploy a two‑track procurement posture: immediate buys to meet near‑term program needs (leveraging stocked items and qualified suppliers) and medium‑term investments (R&D, capacity rights) to capture the innovation premium.
- Consider localized manufacturing or trusted‑sourcing agreements for sensitive programs to reduce sovereign procurement friction and mitigate tariff exposure.
90/180/365 Day Roadmap — How to Convert Insight into Action
- 0–90 days: Complete a supplier stress test (capacity, export exposure, technical certifications), lock short‑term inventory positions for critical RF components, and begin RFPs with export‑aware clauses.
- 90–180 days: Finalize dual‑source contracts for high‑risk components, initiate co‑development agreements with niche antenna specialists, and commence qualification testing aligned with target platform timelines.
- 180–365 days: Execute onshore/nearshore capacity options where required, close M&A or JV opportunities that provide missing capabilities, and roll out the first modular antenna prototypes into platform trials.
Closing: Where PW Consulting Adds Immediate Value
For 2026, the strategic battleground in military antennas will be defined less by raw demand and more by who can manage complexity: export controls, constrained component ecosystems, and multi‑domain certification timelines. PW Consulting’s full Military Antenna Market report moves beyond headline forecasts to provide the executable tools procurement and business leaders need — supplier heatmaps, compliance playbooks, TCO models, and a prioritized action roadmap. These are the instruments that convert a forecast into competitive advantage.
To access the full intelligence suite, including our granular segmentation models, supplier scoring spreadsheets, and RFP templates, visit the PW Consulting Military Antenna Market page. The preview you’ve just read is purposely high‑signal and selectively redacted — the full report contains the transaction‑grade detail executives rely on for 2026 strategic commitments.
For detailed analysis of this topic, please visit the official page: Military Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com