

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Industrial Joysticks Market to Reach USD 304 Million by 2032 (CAGR 6.8%)
By pmarketresearch, 2026-07-23
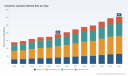
Industrial Joysticks Market 2026: Strategic Imperatives for Decision-Makers
Executive overview
The industrial joysticks market is entering a phase of steady, technology-led expansion. After recovering from pandemic-era supply shocks, the industry expanded from an estimated market size in 2020 to a materially larger base in 2025 and is projected to continue growing through 2032 at a compound annual growth rate (CAGR) of approximately 6.8%. Our modelling shows the market moving from a mid‑hundreds USD million base in 2025 into the high hundreds by the end of the forecast window — an evolution that changes the calculus for product roadmaps, manufacturing scale decisions, and M&A activity in 2026.
Industrial Joysticks Market
Why this report matters for 2026 decision cycles
- Resource allocation: With the market forecast to grow steadily in 2026 and beyond, capital planners must weigh near-term investments in ruggedization, digital connectivity, and aftersales services against longer-term platform bets. The data-driven scenarios in the full study allow CFOs and product chiefs to test investment timing against demand sensitivities.
- Product strategy: Suppliers face competing pressures: extend hardware lifecycles for heavy-duty applications while accelerating digital feature adoption (sensor fusion, contactless/Hall-effect sensing, data capture). The report isolates which technology bets deliver the highest ROI by application cluster and adoption timeframe.
- Go-to-market refinement: Channel and OEM partners are recalibrating value propositions around integrated operator experiences (chairs, HMI, simulator compatibility) and service contracts. Our go-to-market playbooks map those shifts to realistic revenue ramps for 2026 procurement cycles.
- M&A and partnership screening: The market concentration profile indicates enough scale at the top to justify bolt-ons, while substantial share remains addressable through focused regional or application plays. The report provides prioritization criteria and a shortlist methodology suited to 2026 deal strategies.
Market dynamics driving growth
Three structural dynamics underpin the anticipated expansion:
Industrial Joysticks Market
- Technology migration from mechanical to contactless sensing: The shift toward Hall-effect and contactless sensing is no longer niche. These technologies reduce maintenance, increase MTBF, and enable integration with digital control systems — features that buyers increasingly demand for heavy-duty and off-highway equipment. Product announcements and certifications over the last 18 months underscore this trajectory.
- Operator experience and systems integration: Ergonomics, lifecycle performance, and simulator-validated controls are differentiators. Vendors demonstrating long life cycles and validated ergonomic designs — including third-party recognition and simulator integration — are shortening sales cycles with major OEMs.
- Service and data monetization: Aftermarket revenue is emerging as a meaningful lever. Data capture modules and electrohydraulic control interfaces create opportunities for recurring revenue via diagnostics, firmware updates, and performance-as-a-service contracts.
Competitive landscape: strengths, moves, and strategic implications
The competitive field combines global component specialists and regionally focused systems integrators. Market concentration indicates a moderately fragmented industry: a handful of established players command meaningful scale, while numerous specialized vendors capture application-specific demand. Implications for 2026 strategy include selectivity in partnership choice and a focus on proprietary system-level capabilities.
Industrial Joysticks Market
- Curtiss‑Wright Corporation (United States) — Curtiss‑Wright’s recent product introductions emphasize rugged, high-cycle-count controllers engineered for off‑highway environments. Their new heavy‑duty joystick controller announced in 2026 demonstrates a clear focus on durability and mechanical strength for OEMs serving construction and mining segments. Strategic takeaway: competitors should anticipate heightened OEM expectations around lifecycle warranties and mechanical validation.
- J.R. Merritt Controls (United States) — A stalwart in heavy‑duty single- and multi‑axis joysticks and operator chair systems, the company leverages ISO‑certified manufacturing and close OEM relationships. Their product breadth and emphasis on custom controls provide a template for suppliers aiming to win by customization and full‑system delivery rather than component commoditization.
- elobau (Germany) — elobau’s integration of precision joysticks with simulator testing and HMI solutions highlights the premium placed on operator validation and ergonomic awards. Public demonstrations at major industry events reinforce the role of experiential proof-points in procurement decisions.
- OEM Controls (United States) — Focused on rugged electrohydraulic controllers, modular systems, and data capture, OEM Controls exemplifies the emergent hybrid model: hardware plus data services. For manufacturers, this underscores the commercial value of embedding diagnostics and telemetry early in product design.
Recent trade-show activity and product releases through 2026 confirm that the leading vendors are doubling down on durability, digital compatibility, and validated operator ergonomics. Regulators and standards bodies are also shaping product design: industry reporting indicates a meaningful proportion of newer joystick designs incorporate digital connectivity — a trend that directly impacts integration architectures and cybersecurity postures.
What the full PW Consulting report contains (practical, decision-ready tools)
We designed the study to be operationally useful for teams tasked with 2026 strategy execution. Highlights include:
- Market-sizing and scenario modelling: A transparent TAM/SAM/SOM model with three demand scenarios (conservative, base, aggressive) keyed to macroeconomic sensitivities and adoption curves for key technologies.
- Technology adoption playbook: Roadmaps for Hall‑effect/contactless adoption, integration of telemetry, and lifecycle engineering tradeoffs with implied cost-of-goods sensitivity.
- Supplier and component scorecards: Comparative assessments for sensor suppliers, actuator partners, and HMI integrators based on quality, lead-time volatility, and price trajectory.
- Go‑to‑market blueprints: Segment-specific channel strategies, tender playbooks for OEM procurement teams, and aftermarket monetization templates that finance extended warranties and remote diagnostics.
- Manufacturing & sourcing guidance: Capacity planning tools, localization decision matrices, and a short list of critical supply risks — with mitigation levers for 2026 procurement cycles.
- M&A and partnership screening framework: A methodology to rank targets using strategic fit, margin uplift potential, and integration complexity — plus a reproducible valuation sensitivity model.
Strategic recommendations for executives in 2026
- Prioritize durability-linked features for heavy-duty OEMs: Allocate R&D to increase mechanical lifetime and validate through third‑party testing/simulator integration — buyers are willing to pay for proven lifecycle benefits.
- Embed connectivity selectively: Focus on modular telemetry that enables diagnostics and firmware updates without creating unnecessary cybersecurity exposure or BOM inflation.
- Design for serviceability: Package joysticks with diagnostics and aftermarket service offerings to capture higher-margin recurring revenue.
- Target partnership over price competition: For suppliers lacking scale, pursue integration partnerships (operator chairs, HMI, simulator companies) to offer system-level value that is harder to commoditize.
- Use M&A strategically: Seek bolt-ons that add proprietary sensor technology or diagnostic capabilities rather than duplicative product lines; the market’s moderate concentration favors accretive add-ons that increase share and margin.
Risks, uncertainties, and sensitivity considerations
Key risks that will materially change the 2026 playbook include component supply volatility (especially for sensing and semiconductors), faster-than-expected shift to digital controls, and changes in OEM procurement cycles tied to broader capex trends in construction and agriculture. Our sensitivity analysis in the full report quantifies the impact of +/- 200 bps variation in adoption and supply constraints across the forecast horizon.
How to use this research today
- Private equity and corporate development teams: Use the M&A filters and valuation sensitivity model to prioritize targets and structure earnouts around service revenue and durability milestones.
- Product and R&D leaders: Map the technology adoption playbook to 18‑ and 36‑month development cycles, and prioritize features that accelerate OEM acceptance.
- Procurement and supply chain: Implement the supplier scorecards to adjust buying strategies, hedge critical components, and build dual-sourcing where payback is fastest.
- Sales and commercial teams: Apply the tender playbooks and pricing templates to negotiate multi-year deals that include performance guarantees and aftermarket commitments.
Conclusion — the strategic edge for 2026
The industrial joysticks market presents a classic industrial-technology investment opportunity: steady aggregate growth underpinned by discrete technological shifts that reward timely, focused investment. For organizations deciding resource allocation in 2026, the core questions are not whether the market will grow — it will — but how to position product, service, and partnership strategies to capture outsized returns while managing supply and adoption risks.
PW Consulting’s full Industrial Joysticks Market study provides the empirical backbone and executable playbooks needed to make those choices with confidence. This article is a curated preview of our findings; the complete report contains the detailed subsegment intelligence, supplier-level benchmarking, and downloadable financial models that leading teams will use to finalize 2026 investment plans. Visit our report page to access the full dataset and actionable annexes.
For detailed analysis of this topic, please visit the official page: Industrial Joysticks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Battery Market 2026: Strategic Imperatives for Decision‑Makers — A PW Consulting Preview
Executive preview
As companies plan capital allocation, product roadmaps, and M&A strategies for 2026, the battery market is evolving from a growth story to a high‑stakes strategic battleground. Our new Battery Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) models this transformation in granular, decision‑ready detail. At the macro level, the market demonstrates robust expansion: the total market grew steadily through 2020–2025 and, under our baseline, continues to expand at a compound annual growth rate of roughly 10.06% across the forecast window. The result is a market that more than doubles in scale over the next several years, creating both sizable upside for winners and increasing operational complexity for incumbents and new entrants alike.
Battery Market
Why 2026 is a strategic inflection point
2026 matters for three linked reasons. First, raw material dynamics are injecting volatility into cost structures: lithium pricing at the start of 2026 was materially higher than in 2025, driven by stronger-than-expected demand from energy storage and transient supply disruptions. Second, regulatory and safety frameworks are tightening in key markets — clarifications from national agencies and updated state codes are already changing compliance obligations for manufacturers, integrators, and installers. Third, the competitive structure remains concentrated: a small group of incumbent manufacturers and systems suppliers continue to capture a large share of low‑voltage and industrial battery demand, but the mix of technologies and applications is shifting, opening windows for specialized players and new chemistries.
Battery Market
What our preview tells you — top strategic takeaways
-
Act on timing, not just scale: With a pro‑growth baseline CAGR of ~10%, the market presents large addressable opportunities. But winners will be those that sequence investments to match technology maturation, raw material cycles, and regulatory milestones rather than simply expanding capacity indiscriminately.
Battery Market -
De‑risk supply with multi‑layer sourcing strategies: The 2026 lithium price spike underscores the need for hedging, long‑term offtake, and diversification into alternative chemistries and recycled feedstocks.
-
Embed safety and standards engineering early: New codes and guidance — from national agencies to state implementations — are already influencing project approvals and insurance terms. Safety engineering is now a go/no‑go commercial variable.
-
Prioritize modular and serviceable architectures: As applications bifurcate between mobility, stationary storage, and consumer devices, product platforms that enable service, remanufacture, and second‑life pathways will command better margins and lower total lifecycle risk.
What the full report contains — practical tools for 2026 decision‑making
The full Battery Market report is designed as an operational playbook for corporate strategy, commercial planning, and investment committees. It includes:
-
Demand simulations and scenario‑ware: Baseline, upside, and downside demand scenarios through 2032 tied to technology adoption curves and application dynamics.
-
Top‑line market modeling with unit economics: Time‑series market sizing (2020–2025 historical and 2026–2032 forecasts) and sensitivity dashboards that let users reweight inputs (raw material prices, adoption rates, recycling penetration) to see P&L impacts.
-
Cost curve and plant breakeven tools: Regionalized manufacturing cost models, scale thresholds, and capital intensity analyses to guide greenfield vs brownfield decisions.
-
Commercial playbooks: Go‑to‑market options by application (mobility, stationary storage, consumer) with recommended pricing, warranty, and service models for each archetype.
-
Regulatory impact matrix: Mapping of major code changes, recording/incident requirements, and permitting timelines, with specific remediation actions for compliance teams.
-
Competitive profiles and M&A target screening: Executive summaries of incumbent manufacturers and promising challengers, plus acquisition scorecards that combine strategic fit, technology readiness, and integration risk.
-
Circularity and supply security playbooks: Scenarios and supplier roadmaps for building recycled feedstock supply, including collection economics and policy levers that accelerate closed‑loop models.
Competitive landscape — who matters and why
The market remains top‑heavy, with a few global players controlling a disproportionate share of low‑voltage and industrial business. That concentration creates both barriers for new entrants and attractive targets for strategic buyers. Key incumbent profiles from our analysis include:
-
Clarios — A global leader in low‑voltage mobility batteries and solutions. Clarios combines scale manufacturing with deep OEM relationships, making it a natural anchor for automaker electrification strategies and aftermarket consolidation plays.
-
EnerSys — A diversified energy storage and industrial batteries supplier, EnerSys has positioned itself across stationary and motive power segments. Its strength lies in systems integration capability and a broad product portfolio that supports enterprise and telecom customers.
-
East Penn Manufacturing — A specialist with deep expertise in sealed lead‑acid technologies and industrial applications. East Penn’s value is in manufacturing discipline, channel relationships, and cost competitiveness in legacy chemistries.
-
Stryten Energy — Focused on advanced industrial and motive power solutions, Stryten has been investing in technology upgrades and aftermarket services that improve lifetime value in B2B channels.
-
Interstate Batteries, CD Trojan, Continental and other regional players — These firms maintain important distribution, service, and niche manufacturing capabilities. Their local networks and channel control make them attractive partners for OEMs and utilities seeking fast deployment.
-
Asia‑based manufacturers (selected Taiwan firms and others) — Several Taiwanese and Asian producers bring cost‑competitive lithium‑ion and lead‑acid supply as well as rapid OEM responsiveness; they are central to global sourcing strategies, particularly for consumer electronics and light mobility.
From a strategic point of view, incumbents are pursuing three common plays: (1) horizontal consolidation to capture aftermarket services, (2) vertical integration into materials and recycling to protect margins, and (3) systems‑level offerings that bundle cells, BMS, and software as a route to higher lifetime revenues. The market concentration metrics in our model reinforce that top firms will retain outsized influence, but disruption vectors remain significant where technology or service innovation emerges.
Regulation, safety, and raw material pressures — the dynamics that will rewire value chains
Recent industry events and policy moves illustrate the shape of near‑term risk and opportunity. Regulatory clarifications (for example, workplace reporting requirements for incidents involving rechargeable lithium batteries) and updated state energy storage codes are already altering installation and operational protocols. Industry forums and trade groups are mobilizing — for instance, a new Sodium Battery Industry Group was convened in 2026 to accelerate alternative chemistry development — signalling an active effort to broaden technology options away from constrained lithium supply. Meanwhile, safety incidents and recalls in 2026 have heightened consumer safety scrutiny and amplified potential liability for OEMs and distributors.
Operationally, these dynamics translate into concrete decisions: product design must incorporate safer chemistries and packaging, procurement must secure long‑dated raw material contracts or invest in recycling capability, and deployment teams must bake compliance checkpoints into project timelines. For corporate development teams, regulatory divergence across jurisdictions increases the value of acquiring regional players with established compliance track records.
How to use this study in 2026 decision-making
-
Boardroom investment reviews: Use our scenario outputs to stress‑test capital projects against high & low raw material paths and against accelerated regulatory tightening.
-
M&A screening: Apply the proprietary acquisition scorecards to prioritize targets that unlock feedstock security, channel access, or software/data advantages.
-
Procurement strategy: Reconcile short‑term spot exposure with medium‑term hedges and recycling partnerships; our price sensitivity tools quantify P&L exposure for each option.
-
Product and service roadmap: Rebalance R&D budgets toward serviceability, safety engineering, and second‑life optimization to preserve margins under pricing pressure.
What we intentionally withhold here (and why you should read the full report)
To preserve the strategic value of the study for clients and subscribers, this preview demonstrates methodology, senior‑level findings, and actionable implications while intentionally omitting the full segmented tables, regional and application share breakdowns, and granular company financials that form the core of transaction and operational decisions. Those tables — plus downloadable modeling workbooks, raw material sensitivity matrices, and plant‑level cost models — are included in the full report and the companion data package available on our Battery Market page.
Next steps
If your 2026 planning cycle includes supply contracts, capacity investments, technology pivots, or M&A, this study is designed to be a primary input to those decisions. For access to the full dataset, segmentation matrices, and the interactive forecast model, visit PW Consulting’s Battery Market report page or contact our research desk to schedule a live briefing and scenario workshop tailored to your portfolio.
For detailed analysis of this topic, please visit the official page: Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Biofeedback Instruments Market to reach USD 337.64M by 2032 — CAGR 4.83%
By pmarketresearch, 2026-07-23
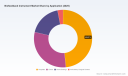
Biofeedback Instrument Market: Strategic Preview for Decision-Makers — PW Consulting
Executive snapshot
As organizations plan budgets, product roadmaps, and M&A activity for 2026, the biofeedback instrument market presents a distinct mix of steady growth, regulatory maturation, and competitive consolidation. Our market model — anchored on a 2025 base year and a contiguous historical window (2020–2025) — shows the global market reaching approximately USD 242.7 Million in 2025 and tracking to a mid-single-digit compound annual growth rate (CAGR) of 4.83% through our forecast horizon (2026–2032). Under our central scenario, the market advances to roughly USD 337.6 Million by 2032. These topline dynamics frame a market that is neither explosive nor stagnant: sufficient scale to support specialized platform plays, adjacent clinical technology integration, and targeted consolidation plays.
Biofeedback Instrument Market
Why this matters for 2026 strategy
- Investment timing: The steady ~4.8% CAGR signals predictable revenue trajectories for both device manufacturers and software-first entrants — a profile that favors bolt-on innovation, subscription monetization, and staged geographic expansion over speculative, capital-intensive build-outs.
- Portfolio prioritization: Clinical adoption curves are shifting from instrument-centric purchases toward integrated hardware-software ecosystems (neurofeedback + DTx, multimodal physiologic monitoring + analytics). Product and partnership decisions made in 2026 will determine whether firms capture recurring, service-linked revenue streams.
- M&A and partnership windows: Market concentration metrics indicate meaningful but not prohibitive dominance — the top three firms control a plurality of share, and the top five aggregate a clear majority. This creates opportunity for mid-sized entrants to be attractive targets for strategic acquirers seeking complementary technologies or channel access.
What our report delivers — practical, transaction-ready intelligence
This report is designed as a strategic toolkit for executives, investors, and clinical leaders preparing for 2026. It balances rigor with operational applicability: we model market size and trajectory, map clinical and commercial adoption, and deliver executable playbooks. Highlights include:
Biofeedback Instrument Market
- Market modelling and scenarios: Detailed base-year calibration (2025), historical trend analysis (2020–2025), and three forward scenarios (conservative, base, aggressive) through 2032 — with sensitivity testing on pricing, regulatory timelines, and reimbursement rollouts.
- Go-to-market and commercial playbooks: Channel economics for hospitals, ambulatory centers, clinics, and home-care propositions; pricing archetypes; salesforce sizing and ROI templates tailored to different product types (e.g., neurofeedback systems, peripheral physiologic sensors, and software/DTx bundles).
- Regulatory and reimbursement roadmaps: Step-by-step guidance for 510(k) pathways, quality systems alignment (GMP/GxP expectations), and payer engagement strategies — including templates to document clinical necessity for CPT-based reimbursement and to expedite local coverage decisions.
- Competitive and partner diligence: A prioritized list of acquisition candidates, licensing partners, and integration targets based on technology fit, customer overlap, and manufacturing capabilities.
- Supply chain and manufacturing risk matrix: Supplier concentration mapping, component lead-time stress tests, and contingency playbooks to accelerate time-to-market under constrained component availability.
- Commercial case studies and pilot frameworks: Ready-to-deploy clinical pilot protocols, endpoint definitions for payers, and customer success KPIs to accelerate adoption and capture evidence for reimbursement.
- Data annexes and templates: Forecast tables, unit economics models, and slide-ready charts for investor briefings (note: the report overview here intentionally withholds certain detailed segment tables to protect client value—complete data available in the full report).
Competitive landscape — what to watch in 2026
The market is characterized by a mix of specialized medtech manufacturers, neurotechnology innovators, and software-first digital therapeutics (DTx) players. The top-of-market position is dispersed among established instrumentation firms and newer entrants that combine sensor hardware with platform software. The following strategic readouts summarize the competitive posture of the leading players we analyze in the full study.
Biofeedback Instrument Market
- Thought Technology Ltd. (Montreal, Canada — https://thoughttechnology.com/)
Strengths: Deep clinical and research adoption driven by an extensive product catalogue in psychophysiological instrumentation and a legacy of integrations for real‑time auditory/visual feedback. Strategic implication: well placed to defend institutional footprints and to upsell cloud/analytics services to research groups and performance centers.
- ELMIKO BIOSIGNALS sp. z o.o. (Milanówek, Poland — https://www.elmiko.pl/en/home-en/)
Strengths: Focused neurofeedback and EEG platforms with a reputation in neurology clinics. Strategic implication: attractive M&A target for global players wanting stronger footholds in European clinical pathways and specialized EEG expertise.
- Mind Media BV (Netherlands — https://mindmedia.com/)
Strengths: Innovative neurotechnology with emphasis on combined hardware/software experiences (qEEG, neurofeedback). Strategic implication: prime partner for DTx companies seeking validated sensor suites and for licensing of analytics modules.
- Laborie Medical Technologies (Canada — https://www.laborie.com/)
Strengths: Vertical focus on urology/urogynecology and gastroenterology with clinically differentiated biofeedback workflows. Strategic implication: demonstrates how niche clinical focus and reimbursement competence can yield high-margin specialty franchises.
- NeuroCare Group GmbH (Munich, Germany — https://www.neurocaregroup.com/)
Strengths: Clinical-grade neurofeedback with extensions into personalized neuromodulation. Strategic implication: competitive where evidence‑based neuromodulation meets clinical therapy pathways; synergy opportunities with rehabilitation and psychiatric services.
- BrainMaster Technologies, Inc. (Bedford, Ohio, US — https://brainmaster.com/)
Strengths: Broad EEG/neurofeedback platform suite for both clinical and personal use. Strategic implication: its hybrid targeting of clinical and consumer-adjacent markets provides options for product-tiering and subscription experiments.
- Quantum World Vision (Calgary, Canada — https://www.quantumworldvision.com/)
Strengths: Specialized biofeedback and energy-balancing equipment with niche customer communities. Strategic implication: an example of how community-driven adoption can sustain premium pricing in adjunctive wellness segments.
- Shanghai NCC Medical Co., Ltd. (Shanghai, China)
Strengths: Volume manufacturing capability for EEG and EMG devices. Strategic implication: a key supplier/partner for scale producers seeking cost-effective hardware supply or contract manufacturing options in APAC.
- Nanjing Vishee Medical Technology Co., Ltd. (Nanjing, China — https://www.vishee.com/)
Strengths: Rehabilitation-focused biofeedback products including EMG and stimulation feedback. Strategic implication: complements rehabilitation therapy providers and is positioned for bundling with physical therapy pathways.
- DeepWell Digital Therapeutics (DTx), Inc. (United States — https://www.deepwelldtx.com/)
Strengths: FDA-cleared software development kit for biofeedback-enabled immersive applications; strong IP in interactive therapeutic media. Strategic implication: exemplifies software-first entrants that can expand addressable market via regulatory-cleared digital interventions.
Regulatory and reimbursement dynamics shaping tactical choices
Regulation and reimbursement are active levers in this market. Biofeedback devices are generally regulated as FDA Class II devices under 21 CFR 882.5050, with the 510(k) pathway used frequently. Recent clearances in 2024–2025 — including software development kits for immersive biofeedback and device-level 510(k) clearances for sleep assessment offerings — demonstrate both the pathway and the appetite for regulatory-backed digital/DTx integrations.
On reimbursement, established Medicare guidance recognizes biofeedback therapy under specific CPT codes when clinical documentation supports medical necessity (notably for certain pelvic floor indications). For strategic planners, the implication is clear: clinical evidence generation that links physiologic endpoints to payer‑relevant outcomes materially improves commercial economics and accelerates institutional procurement.
Actionable moves for 2026
- Prioritize evidence generation for high-opportunity clinical endpoints in the next 12–24 months to align with payer decision cycles.
- Evaluate bolt-on acquisitions that close capability gaps (analytics, cloud services, or regional regulatory expertise) rather than horizontal scale alone.
- Test hybrid go‑to‑market pilots that pair hardware pilots with subscription analytics/DTx to validate LTV/CAC before broad roll-out.
- Build regulatory playbooks and a pre-submission engagement calendar for planned 510(k) filings; use the 2024–2025 clearance precedents as templates for dossier structure and clinical evidence expectations.
- Map supply chain single points of failure and secure dual sources for critical sensor components before initiating larger production runs.
Where to find the full intelligence
This preview highlights the strategic framing and actionable contours of PW Consulting’s full Biofeedback Instrument Market study. The published report contains the granular segmentation tables, region/type/application splits, detailed forecasts, and annexed financial models that organizations require to finalize 2026 budgets and investment decisions. To preserve the value of our proprietary synthesis, this executive overview intentionally omits core segment tables and certain disaggregated figures; the full dataset and downloadable models are available through the PW Consulting report page.
Next steps
If you are evaluating market entry, product-line expansion, or acquisition targets for 2026, PW Consulting can provide a tailored briefing that extracts the most relevant scenarios from the full model and maps them to your P&L and risk appetite. Contact our research desk to schedule a strategic walk-through and obtain the complete data annex that supports the topline outcomes summarized above.
For detailed analysis of this topic, please visit the official page: Biofeedback Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ultrasound Market — USD 8.59B in 2025, 5.97% CAGR to 2032
By pmarketresearch, 2026-07-23
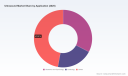
Ultrasound Market 2026: Strategic Preview for Decision Makers
Executive preview
As organizations plan capital allocation and go-to-market moves for 2026, ultrasound technologies are no longer a peripheral efficiency play — they are a structural lever across manufacturing, clinical, and food-processing value chains. PW Consulting’s Ultrasound Market research uses a 2025 base year and a 2026–2032 forecast horizon to translate observed adoption patterns into practical strategic actions. The global market has expanded materially since 2020 (from a mid‑single‑digit billion-dollar base) to an estimated USD 8.59 billion in 2025, and our model projects steady expansion at a 5.97% compound annual growth rate into the forecast window, reaching a projected USD 12.87 billion by 2032. This trajectory creates a set of timing, capability and partnership decisions that will determine winners and laggards in 2026 and beyond.
Ultrasound Market
Why this matters for 2026 choices
-
Investment horizon compression: With predictable, multi-year growth and improving unit economics for advanced sonication and ultrasonic cutting systems, 2026 is a decision year for firms that have deferred upgrades. The expected market momentum reduces adoption risk for first movers who can show short-term ROI through yield improvements and total cost of ownership reductions.
Ultrasound Market -
Operational differentiation: Ultrasonic systems now deliver more than marginal gains — they enable new product forms (multi-layer, sticky, frozen), higher line speeds, and measurable OEE uplifts. Food producers, OEMs and medical-device manufacturers that embed ultrasonic capabilities into their processes can convert process advantages into sustainable commercial differentiation.
Ultrasound Market -
Regulatory and procurement alignment: Several food‑grade certifications and inert-material endorsements (for example, titanium ultrasonic knives) have lowered regulatory friction and accelerated procurement cycles. In practice, that makes pilot-to-scale transitions faster in 2026 than in prior years.
Market dynamics shaping near-term strategy
-
Technology convergence: Innovations in generator design, sonotrode materials and modular system architectures have broadened the set of feasible use cases. Examples from 2024–2025 product introductions (from ultrasonic cutting upgrades to novel non-contact thawing systems) point to a two-track market: incremental replacements of legacy mechanical systems and new applications unlocked by emergent form factors.
-
Service and aftermarket economics: As installed bases mature, recurring service, retrofits and consumables will constitute a meaningful portion of supplier economics. Players that invest in remote monitoring, predictive maintenance and rapid field-service models will capture higher lifetime value per unit sold.
-
Concentration and competitive dynamics: The market exhibits a moderate-to-high level of supplier concentration among incumbent technology leaders, and the top three to five suppliers account for a substantial share of global shipments. That creates both opportunity for challengers (via niche specialization and systems integration) and barriers for entrants (scale, distribution, and certification).
-
Regulatory and hygienic standards: Food‑certified ultrasonic systems and inert-material approvals have removed a key hurdle for adoption in highly regulated production environments. This regulatory clarity reduces procurement risk and shortens the payback calculus for 2026 investments.
What the full report delivers (practical, actionable content)
PW Consulting’s full Ultrasound Market report is structured for rapid decision-making. It is not an academic survey — it is a playbook.
-
Market sizing and trajectory: historical performance to 2025 and modelled scenarios across the 2026–2032 forecast window, with sensitivity testing under alternative adoption rates and price erosion assumptions.
-
Go-to-market frameworks for vendors: channel strategies, OEM partnering archetypes, and timing templates for product launches, prioritized by risk-adjusted ROI.
-
Use-case ROI toolkits: pre-built financial templates that quantify expected gains from portioning, sealing, cleaning, and thawing applications, calibrated to typical line speeds and asset lifecycles.
-
Technology readiness and upgrade roadmap: component-level risk assessment (sonotrode longevity, generator obsolescence, integration complexity), plus a recommended staged rollout plan for piloting and scaling in 2026.
-
Regulatory & compliance playbook: certification checklists, hygienic design requirements, and procurement language to accelerate approval in regulated food and clinical contexts.
-
Competitive supplier scorecards: capability matrices, channel footprints, and partnership fit assessments to support make vs. buy decisions — presented as decision filters rather than raw rankings.
-
M&A and partnership playbook: identify strategic acquisition profiles, valuation heuristics for tuck‑ins, and non-dilutive collaboration structures aligned with growth goals for 2026.
Competitive landscape: what to watch in 2026
The supplier ecosystem is populated by specialist ultrasonic manufacturers and diversified industrial players. Each brings a different strategic posture — product depth, system integration, or channel reach — and our strategic profiles emphasize the implications for buyers and investors.
-
Hielscher Ultrasonics (Teltow, Germany) — Known for high‑performance homogenizers and probe‑type sonicators, Hielscher’s portfolio targets extraction, emulsification and continuous-flow food processing. Their stepped plate and intensified sonication concepts are relevant for frozen-food thawing pilots.
-
Emerson Electric Co. (St. Louis, USA) — Through Branson, Emerson has advanced ultrasonic cutting systems and cleaners focused on confectionery, bakery and dairy portioning. Recent product renewals underscore an emphasis on throughput and reduced waste for high-speed lines.
-
RINCO ULTRASONICS (Germany) — Specializes in ultrasonic welding and cutting for portioning and packaging automation. Their solutions are optimized for residue-free cuts and integration into automated production lines — an attractive profile for processors seeking lower maintenance footprints.
-
TELSONIC AG (Bronschhofen, Switzerland) — Offers cutting sonotrodes and generators with a strong emphasis on packaging sealing and confectionery portioning. Their systems are frequently deployed where precision and packaging integrity are critical.
-
Weber Ultrasonics (Germany) — Modular ultrasonic platforms oriented toward industrial cutting, sealing and utensil cleaning; notable for hygiene-focused applications and aftermarket service models.
-
Dukane (Illinois, USA) — Focuses on ultrasonic knives and generators that deliver clean, non‑sticking cuts in multi-layer bakery and cheese products. Material choices and inertness claims (e.g., titanium contacts) address regulatory concerns.
-
Herrmann Ultrasonics (Germany) — Offers food-certified sealing and cutting solutions that emphasize reduced maintenance and improved overall equipment effectiveness (OEE), which can materially shorten payback periods.
-
Marchant Schmidt (USA) — Strong in high-volume sheet-product cutting systems; their recent two-stage cutters target frozen-meal and bakery lines where throughput and consistency matter.
-
Sonics & Materials, Inc. (USA) — Provides processors and welding equipment for liquid and high-volume food lines; their portfolio supports integration into existing processing footprints.
Notable 2024–2025 developments — from new-generation cutting systems to specialized non‑contact thawing solutions — indicate an R&D cycle that will drive product refreshes and create procurement windows in 2026. Suppliers that convert innovation into field-proven reliability will gain disproportionate share.
Strategic imperatives for stakeholders in 2026
-
For equipment vendors: prioritize modular, serviceable platforms and embed predictive maintenance. Offer pilot-to-scale pricing that transfers operational risk and accelerates customer adoption.
-
For food processors and OEMs: run targeted pilots in 1–2 high-variance product lines to validate yield and OEE improvements before rolling out broadly. Use procurement windows created by supplier product cycles to negotiate upgrade packages and lifecycle service commitments.
-
For investors and acquirers: look for assets that combine proprietary sonotrode or generator IP with recurring service streams. Valuation should emphasize installed-base monetization and channel exclusivity rather than one-off equipment sales.
-
For systems integrators and service providers: build hygienic-design expertise and certification capabilities, because regulatory clarity (e.g., food-grade ultrasonic approvals) is enabling broader adoption and creates service differentiation.
How to use the report in your 2026 planning
The report is designed as an operational toolkit. If you are building a 2026 roadmap, use it to:
-
Prioritize pilot projects using our ROI templates and risk scenarios;
-
Negotiate supplier contracts anchored to demonstrated OEE gains and service SLAs;
-
Design an M&A screen to identify strategic tuck-ins that accelerate market entry or add service revenue;
-
Align procurement and regulatory teams to compress approval timelines for food‑certified ultrasonic equipment.
Final note — the trailer principle
We have presented the directional insights and strategic implications that matter for 2026 without revealing the granular segmentation and supplier scorecards that operational teams need to execute. PW Consulting’s full Ultrasound Market report contains the detailed regional and application splits, vendor financial proxies, complete scorecards, and downloadable financial models referenced in this preview. For practitioners who need executable plans — procurement-ready RFx language, validated ROI models, and integration checklists — the full dossier provides the playbooks and data tables to act in 2026 with confidence.
Call to action
Contact PW Consulting to obtain the full Ultrasound Market report and the accompanying implementation toolkits. Move from insight to action — validate pilots, set procurement timelines, and secure competitive advantage before the 2026 procurement cycles peak.
For detailed analysis of this topic, please visit the official page: Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Marketing Automation to Grow at 11.5% CAGR (2026–2032)
By pmarketresearch, 2026-07-23
Marketing Automation Software Market — Strategic Imperatives for 2026 Decisions
As enterprises prepare budgets and roadmaps for 2026, Marketing Automation sits at the intersection of revenue growth, customer experience, and regulatory risk. PW Consulting’s latest Market Research — grounded in a 2025 base year and projecting through 2032 — maps that intersection with a combination of quantitative forecasts, vendor-level benchmarking, and hands-on implementation playbooks. The market’s trajectory is unambiguous: after rising from a multi‑billion dollar base in 2020 to roughly USD 7.0 billion in 2025, our models point to sustained expansion driven by AI, wider omnichannel activation, and deeper CRM-commerce alignment — a trajectory that translates to an 11.5% compound annual growth rate (CAGR) across the forecast window and a market on track to roughly double in size by the early 2030s.
Marketing Automation Software Market
Why this research matters for 2026 strategy
Decision-makers in 2026 face three simultaneous pressures: (1) convert marketing automation investments into measurable revenue, (2) protect customer data and ensure compliance in an evolving privacy landscape, and (3) close the operational gap between platform capability and internal skillsets. Our research is designed to be directly actionable for those priorities. It does not only quantify market opportunity: it isolates the commercial levers that drive measurable ROI, surfaces vendor-risk profiles, and provides the procurement and implementation sequences required to capture value within 12–18 months.
Marketing Automation Software Market
Market trajectory: what the headline numbers conceal
Headline growth metrics — the five‑year history and the 11.5% CAGR to 2032 — reflect two distinct forces. First, incremental adoption and feature expansion among mid-market and enterprise buyers (AI-powered personalization, orchestration, analytics) are expanding average deal sizes. Second, ongoing platform diffusion — both through verticalized offerings for e‑commerce and composable stacks for enterprise architectures — is increasing the pool of addressable buyers. That said, headline growth masks meaningful heterogeneity in buyer needs, deployment models, and pricing sophistication. The full report separates those dynamics into practical decision trees and procurement templates; here we deliberately withhold granular sub‑segment tables to preserve the “preview” purpose of this executive overview.
Marketing Automation Software Market
Key forces reshaping vendor economics
- AI acceleration and workflow automation. Generative and predictive models are moving from experiment to production, reshaping how vendors price value (outcome‑based elements, AI feature add‑ons). Successful vendors are those that translate AI into predictable lift in activation and conversion, not just flashy capabilities.
- Composability vs. suite consolidation. Buyers increasingly demand modular, API-first stacks that integrate CRM, commerce, analytics, and identity services. This trend favors platforms with rich partner ecosystems or vendors that offer easy migration and integration toolkits.
- Privacy and regulatory friction. Legislative updates through late 2025 and early 2026 have elevated compliance costs and architectural constraints. Organizations must bake data governance into implementation roadmaps; failure to do so will materially increase TCO and time-to-value.
- Skills and operational adoption. Our market diagnostics quantify a non-trivial negative headwind from a shortage of specialized marketing automation talent — a constraint that, if unaddressed, will depress realized CAGR materially versus theoretical adoption curves.
Competitive landscape — concentrated but contestable
Market concentration metrics indicate that leadership is distributed: a meaningful share of revenue accrues to the largest vendors, but a healthy field of specialized and vertical players retains scale and influence. Top vendors occupy distinct strategic positions: some are enterprise orchestration platforms; others focus on mid-market simplicity or verticalized e‑commerce capabilities. Understanding those positions — and how they translate into total cost of ownership, integration risk, and upgrade paths — is central to sourcing decisions in 2026.
- HubSpot — Reinforces its platform approach with a steady cadence of feature releases. Recent product initiatives emphasize AI-driven content and search-optimization capabilities that aim to lower friction in creative and organic discovery workflows.
- ActiveCampaign — Continues to blur the line between marketing automation and knowledge-driven personalization, expanding its AI integrations to present a unified sales-marketing automation option for growth-stage buyers.
- Klaviyo — Maintains a differentiated play in lifecycle and e‑commerce marketing automation, where real-time segmentation and commerce-native integrations deliver outsized ROI for digital-first merchants.
- Braze — Positions itself as the real‑time customer engagement engine; its emphasis on cross‑channel orchestration and predictive analytics is attracting retailers and consumer apps prioritizing session-to-conversion impact.
- Salesforce Marketing Cloud, Adobe Marketo Engage, Oracle Eloqua, Microsoft Dynamics 365 Marketing — Each of these enterprise-grade platforms competes on depth: complex workflow orchestration, large-scale integrations, and enterprise governance. Buyers weighing these options must match incumbent systems, procurement complexity, and long-term roadmap alignment.
- Mailchimp — Continues to serve as a pragmatic, user-friendly option for smaller marketing teams that prioritize ease of use and rapid deployment over deep enterprise orchestration.
Recent vendor developments underscore the bifurcation between AI feature competition and platform consolidation. For example, HubSpot’s Spring 2026 release introduced enhancements designed to boost brand visibility and AI‑prompting workflows, while ActiveCampaign’s late‑2025 moves deepened AI-sourced personalization and knowledge integration. Those product moves show the degree to which AI is now a primary battleground — but not the only one. Integration costs, service model, and vendor delivery capacity remain decisive factors in procurement.
What the PW Consulting report delivers — practical, deployable tools
This research is explicitly built for executives who must make 2026 vendor choices and operational plans. The full deliverable includes:
- Quantitative market sizing and scenario forecasts to 2032, including sensitivity analyses under different regulatory and talent availability paths.
- Vendor benchmark matrix and procurement scorecards that synthesize product capability, integration risk, total cost of ownership, and vendor health.
- Implementation roadmaps with phased milestones, migration blueprints (including cloud/on‑prem considerations), and an adoption playbook mapped to common organizational structures.
- TCO and ROI calculators with configurable inputs for licensing, data-hosting, compliance, and workforce costs — enabling finance teams to stress-test investments.
- Data governance and privacy compliance checklist aligned to recent regulatory changes, plus contractual clauses and negotiation playbooks that reduce downside risk.
- AI readiness assessment and practical templates to operationalize model governance, testing, and continuous improvement loops.
- Change-management assets: capability gap matrices, role transformation guides, and a prioritised staffing plan to mitigate the specialist shortage.
We intentionally present the high‑value outputs above while reserving the granular sub‑segment tables, regional breakdowns, and vendor scorecard sheets for the full report. That level of granularity is essential to procurement and technical teams and is available in the downloadable research pack.
Operational recommendations for 2026 (concise playbook)
- Prioritize use cases with measurable LTV uplift. Select pilots that directly tie marketing automation to customer lifetime value or measurable revenue events to ensure momentum for broader rollout.
- Insist on open APIs and composable architecture. Avoid vendor lock-in by requiring clear integration paths to CRM, commerce, analytics, and identity layers.
- Embed privacy and compliance into procurement criteria. Recent regulatory updates increase the cost of non-compliance; vendors must demonstrate governance capabilities and contractual protections.
- Quantify implementation and operational labor explicitly. Account for the specialist shortfall in your financial models and fund a center of excellence or managed services partner where gaps exist.
- Negotiate flexible licensing tied to outcomes. Seek pilot-to-scale pricing and clauses that align incremental costs with realized business metrics.
- Run scenario planning now for 2028–2032. Use multi-scenario forecasts to stress-test choices; migration costs and the pace of AI adoption will materially shift outcomes over the long term.
Conclusion — what to do next
For 2026 strategic planning, this market is no longer a simple vendor selection exercise; it is a cross-functional transformation that touches product, sales, IT, legal, and finance. PW Consulting’s Market Research delivers both the directional forecast (the market’s strong, AI-fueled growth at an 11.5% CAGR) and the tactical instruments that executives and procurement teams need to act now while managing risk. If your organization must select vendors, de-risk a rollout, or build an internal competency to operationalize marketing automation, the full report provides the models, scorecards, and implementation templates to shorten time-to-value and protect downside.
To access the complete vendor scorecards, region and application splits, TCO models, and downloadable implementation templates, visit the PW Consulting research portal. The preview you’ve read here establishes the strategic context; the full report is where the operational work gets done.
For detailed analysis of this topic, please visit the official page: Marketing Automation Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Wire & Cable Market to Reach USD 84,650M by 2032 at 6.1% CAGR
By pmarketresearch, 2026-07-23
Automotive Wire & Cable Market 2026: Strategic Preview and Executive Playbook
Introduction — why this market, why now
The automotive wire and cable market is entering a period of structurally higher strategic importance. Between 2020 and 2025 the market expanded from a roughly USD 43.1 billion base to about USD 56.7 billion (USD Million, base year 2025), driven by accelerating electrification, rising vehicle electronic content, and stricter safety and environmental rules. Our forecast projects the market to grow at a compound annual growth rate (CAGR) of approximately 6.1% entering the 2026–2032 horizon, reaching an industry value in excess of USD 84.6 billion by 2032.
Automotive Wire and Cable Market
For executives preparing capital allocation, supplier strategy, product roadmaps, or M&A activity in 2026, these macro dynamics are not academic — they determine sourcing risk, margin trajectories, and the prioritization of product and process investments. This preview highlights the report’s strategic value without revealing the granular segment tables reserved for report subscribers.
Automotive Wire and Cable Market
What the market snapshot tells strategic decision-makers
-
Scale and momentum: The size of the market and its mid-single-digit CAGR create a sizeable addressable opportunity for established suppliers and capable new entrants. The growth is large enough to justify targeted investments in manufacturing and R&D, but not so concentrated that first-mover premium positions are guaranteed without execution advantages.
Automotive Wire and Cable Market -
Fragmented structure: Market concentration metrics indicate a fragmented competitive landscape (CR3: ~25%, CR5: ~33%). This fragmentation preserves room for fast-follower strategies and regional champions, while leaving room for consolidation plays where operational synergies or technology leadership can be proven.
-
Timing matters: The transitional period around 2026 is decisive — technology choices made today (insulation compounds, conductor sizing, harness architectures) will scale through the later part of this forecast and lock in supplier economics and OEM integration models.
Key dynamics reshaping demand and supply
-
Electrification and system complexity: Increasing adoption of battery electric vehicles (BEVs) and hybrid systems is raising average cable counts, introducing high-voltage architectures, and accelerating demand for specialty cables (high-voltage, battery interconnects, sensor cabling). These trends raise per-vehicle wire and cable content and change supplier qualification hurdles.
-
Regulatory overlay: Regional and international regulations are tightening material and safety requirements. Notably, European mandates are moving towards halogen-free cable materials to limit toxic gas release in fires, and new insulation compounds demonstrating flame resistance beyond 850°C have become commercially available and are being specified in over 35 vehicle-producing countries. Compliance with UNECE WP.29 and ISO 6722 test regimes has become table stakes for global OEM supply.
-
Raw material volatility: Copper remains the dominant conductor metal, and price moves materially affect cost pass-through and margin for vertically integrated vs. merchant cable suppliers. As of late March 2026 the reference copper price was about USD 5.44/lb, down from an early-2026 peak near USD 6.58/lb — a reminder that procurement strategies and hedging discipline materially impact competitiveness.
-
Supply chain resilience and localization: Pressure to shorten supply chains, combined with trade dynamics and localized EV ecosystems, makes manufacturing footprint strategy a critical differentiator. Suppliers that balance local content with centralized technology hubs will hold the strongest positions.
Strategic implications for 2026 decisions
-
Prioritize materials and safety compliance investments now. Shifts to halogen-free compounds and high-temperature ratings are not incremental — they alter process flows, supplier qualification timelines, and testing investments. OEMs and tier-1s that front-load validation in 2026 will avoid costly requalifications as regulations become more prescriptive.
-
Differentiate on systems integration rather than commodity conductors. With market fragmentation and mid-single-digit CAGR, premium margin pools will favor suppliers who bundle connectivity, harness engineering, and electronic connectivity systems — not those competing purely on raw copper price.
-
Hedge raw material exposure and optimize procurement cadence. Given observed copper price volatility, firms should combine long-term contracts, active hedging, and design choices that limit conductor overspecification without jeopardizing performance.
-
Opportunity windows for consolidation and niche plays. The recent acquisition activity in the sector signals M&A appetite: buy-side players should evaluate tuck-ins that add EV-capable product lines or regional footprint; sell-side players should assess whether scale or niche specialization maximizes exit valuation.
Competitive landscape — who matters and why
The market is populated by a mix of global wiring-system integrators and specialized cable manufacturers. Seven companies merit attention for strategic benchmarking and partnership screening:
-
Furukawa Electric Co., Ltd. (Tokyo) — recognized for high-performance wiring harnesses and specialty cables tailored to EVs and autonomy platforms. Their strength lies in combining materials expertise with system-level harness engineering.
-
Southwire Company (Carrollton, GA) — a strong North American presence notable for power cables and harness components; an important competitor where scale in commodity and semi-custom cable solutions matters.
-
TE Connectivity (Schaffhausen) — offers a wide portfolio across sensor cable, power assemblies, and modular connectivity solutions; excels at component-level engineering that supports rapid OEM adoption.
-
Yazaki Corporation (Tokyo) — a global leader in wire harnesses and in-vehicle networks; its deep OEM relationships and systems experience make it a standard-setting supplier in many vehicle platforms.
-
Leoni AG (Nuremberg) — historically strong in automotive wiring systems; its Automotive Cable Solutions division was acquired in July 2025 by TIME Interconnect (a Luxshare-ICT subsidiary), reshaping competitive dynamics and illustrating consolidation drivers.
-
Sumitomo Electric Industries (Osaka) — offers high-voltage automotive wires and cables focused on EV and powertrain applications; notable for materials science capabilities.
-
Coroplast Fritz Müller GmbH & Co. KG (Neumünster) — provides cable management and protective tapes alongside wire and cable products; they showcased e-mobility solutions at the Battery Show Europe in June 2026, underscoring the importance of complementary products for battery and EV systems.
Recent signals and what they mean
-
Leoni’s Automotive Cable Solutions acquisition (July 2025) signals acquisitive pressure from larger electronics assemblers seeking vertical integration into wiring systems — a trend that can accelerate consolidation or strategic partnerships in 2026.
-
Trade show activity such as Coroplast’s Battery Show Europe participation (June 2026) reflects increasing OEM and supplier attention to cable management solutions specific to battery systems — an area where adjacent capabilities (adhesives, tapes, protection systems) create differentiation.
-
Regulatory and materials trends, as noted above, are forcing a simultaneous expansion in product performance and a re-evaluation of manufacturing processes. This dual pressure increases capital intensity for established players and raises the bar for new entrants.
What our full report delivers (practical, operationally focused)
The full Automotive Wire and Cable Market study is built as an executive-grade playbook and a practitioner toolkit. Key deliverables include:
-
A validated market-sizing model (2020–2025 historical, 2026–2032 forecast) calibrated to industry shipment and content trends.
-
Scenario-based demand modeling that isolates the impact of EV penetration, high-voltage adoption, and regulatory shifts on total cable content per vehicle.
-
Supplier scorecards that compare technology breadth, manufacturing footprint, margin profiles, and OEM exposure for the major players noted above.
-
Procurement and cost-sensitivity tools that quantify the P&L impact of raw-material swings and alternative conductor or insulation choices.
-
Playbooks for M&A and partnership assessment, including integration checklists and valuation adjustment frameworks for technology and footprint synergies.
-
A prioritized roadmap for R&D and capital investment decisions, with time-bound recommendations for material qualification, pilot lines, and compliance testing.
How leaders should use this intelligence in 2026
-
Supply chain leaders: Rebaseline supplier risk scores using the report’s supplier maps and the copper price sensitivity analyses; re-run sourcing scenarios that reflect localized EV production hubs.
-
Product and engineering heads: Use the scenario modeling to choose between conservative overdesign vs. optimized conductor strategies; time the introduction of halogen-free materials to align with platform refresh cycles.
-
Corporate development teams: Apply the M&A playbooks to triage targets that add EV-specific capabilities, regional scale, or complementary product lines (e.g., cable management systems).
-
R&D and quality: Prioritize investments in materials testing and flame-retardant compound qualification to meet UNECE WP.29 and ISO 6722 windows and avoid rework cycles.
Accessing the granular intelligence
This article is designed as a strategic trailer: it frames the opportunity, the risks, and the choices that will shape competitive positions through 2032. The full report contains the granular segmentation, regional breakdowns, and numeric scenario outputs that are essential for transaction diligence, capital planning, and engineering-spec rollouts. Those detailed tables and the interactive models are intentionally omitted here to focus on actionable strategy; they are available through the PW Consulting report portal.
Closing — the practical next steps for 2026
Decisions taken in 2026 about material sourcing, investments in halogen-free and high-temperature insulation, and partnership or acquisition targets will determine who captures the higher-margin, system-level opportunities in the next product cycle. The market’s scale, the mid-single-digit growth trajectory, and a fragmented supplier base together create a fertile field for targeted investments and strategic consolidation — but only for organizations that align procurement, R&D, and corporate development around a unified 3–5 year plan. Use the report to translate the headline growth into prioritized actions, testable assumptions, and financial scenarios that fit your risk tolerance and strategic ambitions.
For detailed analysis of this topic, please visit the official page: Automotive Wire and Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Unsaturated Polyester Resins (UPR) Market — Strategic Briefing for 2026 Decisions
PW Consulting’s latest industry briefing synthesizes macro dynamics, competitive moves and practical playbooks that senior executives and strategy teams must act on in 2026. The unsaturated polyester resins (UPR) market has returned to structural growth after the mid-decade inflection in feedstock and regulatory costs. Our research frames that growth in numbers and, critically, translates it into prescriptive options for pricing, capacity, product strategy and M&A prioritization — while reserving the full segment-level datasets for the detailed report.
Unsaturated Polyester Resins (UPR) Market
Market Snapshot: scale, trajectory and concentration
At the market level, UPR has expanded from a 2020 baseline and reached a base-year (2025) industry value that we report in USD Million. Our forecast through 2032 projects continued expansion, reaching a materially larger market by the end of the forecast window at a compound annual growth rate (CAGR) of 6.2% over 2026–2032. This trajectory reflects demand elasticity across construction, marine and industrial composite applications, and is tempered by persistent feedstock volatility and regulatory compliance costs.
Unsaturated Polyester Resins (UPR) Market
Consolidation and scale matter. The market exhibits a mid-range level of concentration: the top three firms account for a majority share and the top five raise that share meaningfully further. These concentration dynamics create strategic advantages for incumbents who can pair procurement scale with technical differentiation; they also open defined windows for challengers that pursue narrow product or regional specialization.
Unsaturated Polyester Resins (UPR) Market
Why this briefing matters for 2026 strategic choices
- Decision velocity: 2026 is a tactical year for realigning procurement and pricing tactics as raw material volatility persists. Firms that defer will face margin compression and lost share.
- Regulatory cliffs: New digital product passport requirements and ingredients scrutiny in Europe, together with updated SVHC listings, have changed compliance from a cost line item into an operational capability that affects market access.
- Portfolio prioritization: Product and channel moves made in 2026 will determine participation in higher-growth subsegments of composites and sustainable formulations for the next five years.
Recent strategic moves and market signals executives must parse
- M&A and ownership reshaping: The sale of a major composites business in 2025 signaled willingness by large chemical groups to monetize non-core UPR assets — creating opportunities for private equity and strategic buyers to consolidate plant networks or specific technology platforms.
- Product innovation and sustainability: Leading specialty chemical players announced bio-based UPR grades aimed at automotive and construction demands, indicating the premium that OEMs are willing to pay for lower-carbon inputs.
- Capacity shifts: Recent expansions in Asia reflect where demand growth and cost advantages are concentrated; this implies a need to re-evaluate regional manufacturing footprints and logistics strategies.
- Commercial and pricing pressure: Price increase announcements in 2026 by regional producers underscore a still-fragile balance between raw material pass-through and competitive thresholds in mature markets.
Supply-side and regulatory headwinds: operational priorities
2025–2026 saw several structural shocks relevant to UPR producers and buyers. Feedstock volatility — notably in propylene glycol, phthalic anhydride and maleic anhydride — continues to exert pressure on margins and creates procurement risk. Regulatory changes, primarily in Europe, added digital compliance burdens (digital product passport requirements) and increased supply-chain monitoring after SVHC list updates. Trade policy actions that raised tariffs on certain European upstream inputs also altered cost competitiveness for exporters.
For operators and buyers this translates into three operational imperatives: (1) sophisticated feedstock hedging and index-linked contracts; (2) investments in compliance infrastructure and traceability to avoid market exclusions; and (3) tactical pricing playbooks that preserve margin without accelerating volume loss.
Competitive landscape: mapped players and strategic postures
Key players in the UPR ecosystem reflect diverse strategic models — from scale-focused producers to specialty formulators. Representative profiles and strategic postures we analyze in the report include:
- Scale-specialist groups with integrated polyester and downstream composite offerings that leverage backward integration to manage feedstock exposure and deliver cost advantage.
- Global chemical majors with UPR offerings embedded in broader performance-material portfolios and distribution networks, focusing on industrial and high-performance composites segments.
- Specialty formulators and regional manufacturers that compete on product differentiation (marine grades, gelcoats, sustainable formulations) and nimble local service models.
We evaluate specific industry players — from European and North American incumbents to Asian regional producers — in the full competitive matrix, assessing capacity footprints, technology platforms, go-to-market channels and recent strategic moves such as product launches, expansions and price actions. Examples of important developments that shape competitive dynamics are included in our analysis: strategic divestments of composite businesses, launches of bio-based resin grades for automotive and construction, capacity ramp-ups in Asia and targeted price increases across EMEA and India markets.
Strategic implications and recommended actions for 2026
Our firm recommends a prioritized set of actions for C-suite and commercial leaders that align to three horizons: immediate (0–12 months), near-term (12–36 months) and transformative (36+ months).
- Immediate (0–12 months)
- Implement dynamic procurement: move from fixed annual contracts to a hybrid of indexed purchasing and short-term forward coverage for critical feedstocks.
- Stress-test price elasticity by channel: run pilot price increases selectively in less elastic segments where regulatory-driven product differentiation justifies premium capture.
- Fast-track compliance fixes: deploy minimal viable product-passport systems to avoid market access interruptions in Europe.
- Near-term (12–36 months)
- Invest in targeted product development for bio-based and low-VOC UPR grades linked to OEM sustainability roadmaps.
- Reassess manufacturing footprint: prioritize brownfield expansions or tolling agreements in cost-advantaged regions rather than greenfield builds where possible.
- Pursue bolt-on M&A: focus on specialty formulators or regional capacity with strong customer relationships that can be integrated into distribution networks.
- Transformative (36+ months)
- Pursue platform plays: combine technical IP (e.g., gelcoat and marine resin technologies) with digital supply-chain controls to create a defensible premium business.
- Embed circularity: pilot resin formulations designed for recyclability or feedstock circularity in partnership with downstream OEMs and recycling specialists.
What the full PW Consulting UPR report delivers (practical content)
The published study translates our findings into executable artifacts that strategy, commercial and operations teams can use in 2026. Highlights include:
- Market sizing and seven-year forecasts by total market (USD Million) with scenario sensitivity to feedstock and regulatory pathways.
- Competitive benchmarking: capacity maps, technology stacks, and an M&A heat map identifying targets by strategic fit.
- Regulatory impact assessment and compliance playbooks specific to digital product passports and SVHC-driven disclosure requirements.
- Raw material cost models and hedging templates tailored to propylene glycol, phthalic anhydride and maleic anhydride exposures.
- Commercial playbooks: segmented pricing strategies, channel-specific promotions, and OEM partnership approaches for sustainable grades.
- Capex and network optimization toolkits for footprint decisions, including brownfield expansion checklists and tolling partner evaluation matrices.
- Board-ready slide decks and a 100-day rapid-response plan for companies facing acute margin pressure or regulatory deadlines.
Note: To preserve the strategic value of this briefing and encourage direct engagement, the public summary omits detailed split tables and fine-grained regional/application shares. Those segment-level datasets, company scorecards and transaction valuations are available in the full report package.
Risk register: what could derail the base forecast
- Sustained feedstock spikes: Extreme, prolonged increases in propylene glycol or anhydrides would compress margins and slow adoption of higher-cost sustainable grades.
- Tightened regulation: New restrictions on key monomers or accelerated SVHC updates could force reformulation costs and restrict market access.
- Geopolitical shocks and tariffs: Trade measures that alter input flows or raise export costs could reset regional competitiveness faster than capacity rebalances.
- Technology disruption: Accelerated substitution by alternative matrix chemistries in major end-markets like wind and transportation would reduce UPR addressable demand.
Concluding counsel for 2026
For executives planning resource allocation this year, the strategic imperative is clear: act now to shore up supply resilience, convert product sustainability initiatives into commercial premiums, and use M&A selectively to secure specialized formulations or regional market access. The UPR market’s mid-term growth is intact, but it will be stratified — favoring players who combine procurement discipline, compliance capabilities and targeted innovation.
PW Consulting’s full UPR report provides the operational detail and downloadable decision tools to convert these strategic priorities into board-level initiatives and 2026 action plans. Access to the complete segment data, company scorecards and scenario models is available through our report portal.
For detailed analysis of this topic, please visit the official page: Unsaturated Polyester Resins (UPR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Light Gauge Steel Market to Reach USD 63.02B by 2032 at 5.73% CAGR
By pmarketresearch, 2026-07-23
Light Gauge Steel Market: Strategic Intelligence for 2026 Decision-Makers
As capital allocation, sourcing strategies, and product roadmaps are recalibrated for 2026, executives in construction, prefabrication, and building-materials supply chains require a concise yet rigorous map of the Light Gauge Steel (LGS) market. PW Consulting’s new market study — benchmarked to a 2025 base year and projecting through 2032 — translates five years of historical dynamics (2020–2025) and a forward CAGR of 5.73% into actionable intelligence tailored for boardrooms, corporate development teams, and operating executives.
Light Gauge Steel Market
Why this study matters in 2026
The LGS market is at an inflection point. After steady expansion in the early 2020s and an accelerated step-change into 2024–2025, global market valuation crossed a new threshold in the 2025 base year. Our model anticipates continued expansion across the 2026–2032 forecast window, with compound annual growth supporting incremental investment and strategic repositioning. For leaders weighing near-term M&A, capacity expansion, or technology adoption decisions, the report synthesizes market momentum, risk contours, and opportunity clusters into a single decision-grade artifact.
Light Gauge Steel Market
- Timing for capital deployment: With the market growing into 2025 and continuing at a mid-single-digit CAGR, 2026 represents an advantageous window to accelerate strategic partnerships and selective greenfield or brownfield investments before the next consolidation wave.
- Supply-chain hedging: Volatility in steel feedstock and logistics requires scenario-based procurement planning — the study provides validated demand curves and supplier pressure points enabling defensible hedging strategies.
- Product & technology strategy: Advances in design-for-manufacture, automated roll-forming and installation aids are changing unit economics; the study quantifies where efficiency gains materially alter returns.
Market trajectory you can trust (concise, source-linked)
PW Consulting’s top-line market model is built from reconciled demand indicators, trade flows, and industry financials. The report documents the market’s historical development through 2025 — the base year used across our analyses — and projects to 2032. The headline trajectory is clear: the sector advances at a 5.73% CAGR across the forecast period, with the 2025 benchmark reflecting the market’s post‑pandemic recovery and structural adoption trends. These high‑level figures are integrated into the study’s investment and scenario modules to stress-test capital plans under multiple macroeconomic paths.
Light Gauge Steel Market
What the report contains: practical, executable modules
To ensure immediate applicability, the study is structured around five operational pillars that translate insight into action.
- Decision-grade market sizing & forecasting: Top-down and bottom-up models with sensitivity analyses across price, volume and substitution scenarios. Base year anchored to 2025 data; forecast horizon 2026–2032.
- Demand-driver diagnostics: End-user adoption curves, technology penetration, regulatory levers and cost‑competitiveness matrices that identify where and how demand will accelerate or stall.
- Competitive positioning & playbooks: Strategic profiles of incumbent manufacturers, systems providers and digital/automation entrants, with playbooks for market entry, defensive moves, and value-capture strategies.
- Supply-chain and operations toolkit: Benchmarks for roll-forming lines, prefabrication yields, logistics footprints, and labour productivity. Includes a decision matrix for insource vs outsource and a CapEx/OpEx tradeoff simulator.
- Risk & regulation scenarios: Four foresight scenarios (baseline, accelerated adoption, protectionist fragmentation, and commodity-shock) with quantified P&L and EBITDA sensitivity tables for each major path.
Competitive landscape: what leading players are doing
The competitive field in LGS blends global steel producers, systems integrators, and specialised manufacturers. Market concentration metrics point to a moderately consolidated ecosystem — our CR3 and CR5 estimates indicate meaningful scale advantages for the largest players. That concentration creates clear windows for mid-sized firms to specialize, partner or pursue regional roll-ups.
Strategically, incumbent and prominent suppliers occupy distinct value positions:
- Systems & components specialists (e.g., companies with deep product portfolios for studs, tracks and connectors) are competing on unit economics and integrated spec compliance, emphasizing distribution reach and lightweighting innovations.
- Regional aggregators and prefabricators are capitalizing on faster project cycles by bundling design-for-manufacture services with onsite installation support, lowering end-to-end cycle times.
- Global steel producers leverage upstream integration to protect margins and to offer strategic pricing arrangements, forcing differentiated offerings from pure-play fabricators.
Our competitive profiles — covering product stacks, manufacturing footprints, technology adoption, channel strategies and M&A appetite — spotlight who is best positioned to win in price-sensitive retrofit markets versus where specialized service providers will capture premium margins in prefabricated, high‑value projects.
Recent industry developments shaping 2026 choices
- Standards and design developments: In early 2026, the Cold‑Formed Steel Engineers Institute published a technical note addressing vibration behavior in joist-framed floors — a practical design update that materially affects specifications for mid-rise and multi-family projects. Such standards updates shorten time-to-spec for modern LGS systems and reduce engineering friction on new projects.
- Installation productivity innovations: Product introductions focused on installation precision and speed — such as a tracking/guide system launched in April 2026 — are lowering labor cost per square meter and improving on-site tolerances, shifting competitiveness toward providers that adopt these tools early.
- Market engagement and knowledge transfer: Exhibitions and knowledge forums (including major trade shows and expos in 2026) have accelerated cross-pollination between engineering practices and manufacturing capability, increasing the pace at which R&D translates into deployable solutions.
Risks, friction points and what to stress-test now
- Commodity volatility: Feedstock price swings compress margins and accelerate consolidation among low-margin producers.
- Regulatory divergence: Differing regional adoption of new design codes can create certification and engineering-friction costs for exporters and systems suppliers.
- Installation labor and skills: Automation reduces labor intensity, but the transition requires investment in training and new equipment — a capital vs. productivity tradeoff every operator must address in 2026.
- Consolidation dynamics: Moderate market concentration implies M&A activity will reshape distribution and prefabrication networks; buyers must model integration synergies rigorously.
How executive teams should use this study in 2026
Each function within a company can extract immediate value:
- Strategy & Corporate Development: Use our valuation overlays and M&A playbooks to identify targets and to construct bid cases with conservative synergies.
- Operations & Supply Chain: Leverage the production benchmarking and the insource/outsource decision matrix to reconfigure capacity and minimize cash exposure to commodity cycles.
- Product & Engineering: Integrate the standards and design intelligence to accelerate product-market fit and to reduce time-to-certification.
- Sales & Commercial: Deploy the segmentation and channel playbooks to sharpen propositions for developers, contractors and modular builders — and to design commercial incentives that reflect regionally specific adoption curves.
Methodology and confidence
PW Consulting’s estimates combine transaction-level interviews, plant-level equipment audits, trade-flow reconciliation, and scenario-based Monte Carlo simulations. The 2025 base year is reconciled across public filings, proprietary shipment data and validated vendor surveys. Our concentration indicators show a market where the three and five largest players capture a significant share of value — an important input for antitrust-sensitive M&A playbooks and for partnership design.
A trailer, not a spoiler — where to go for full detail
This introduction demonstrates the analytical depth and direct applicability of the full PW Consulting study while intentionally withholding granular segment-level metrics and dollar-by-dollar breakdowns. The full report contains those detailed segmentations, regional demand curves, unit economics by framing type, and downloadable models tailored to customizable scenarios. For teams preparing 2026 capital deployment, procurement negotiation, or product launch decisions, the complete dataset and the interactive forecast tool are indispensable.
To access the full intelligence pack — including downloadable models, supplier scorecards, and scenario P&L stress-tests — visit our report page. PW Consulting’s Light Gauge Steel Market study equips decision-makers with the foresight and tools required to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Light Gauge Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com