

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Wire & Cable Market to Reach USD 84,650M by 2032 at 6.1% CAGR

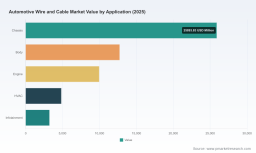
Automotive Wire & Cable Market 2026: Strategic Preview and Executive Playbook
Introduction — why this market, why now
The automotive wire and cable market is entering a period of structurally higher strategic importance. Between 2020 and 2025 the market expanded from a roughly USD 43.1 billion base to about USD 56.7 billion (USD Million, base year 2025), driven by accelerating electrification, rising vehicle electronic content, and stricter safety and environmental rules. Our forecast projects the market to grow at a compound annual growth rate (CAGR) of approximately 6.1% entering the 2026–2032 horizon, reaching an industry value in excess of USD 84.6 billion by 2032.
Automotive Wire and Cable Market
For executives preparing capital allocation, supplier strategy, product roadmaps, or M&A activity in 2026, these macro dynamics are not academic — they determine sourcing risk, margin trajectories, and the prioritization of product and process investments. This preview highlights the report’s strategic value without revealing the granular segment tables reserved for report subscribers.
Automotive Wire and Cable Market
What the market snapshot tells strategic decision-makers
-
Scale and momentum: The size of the market and its mid-single-digit CAGR create a sizeable addressable opportunity for established suppliers and capable new entrants. The growth is large enough to justify targeted investments in manufacturing and R&D, but not so concentrated that first-mover premium positions are guaranteed without execution advantages.
Automotive Wire and Cable Market -
Fragmented structure: Market concentration metrics indicate a fragmented competitive landscape (CR3: ~25%, CR5: ~33%). This fragmentation preserves room for fast-follower strategies and regional champions, while leaving room for consolidation plays where operational synergies or technology leadership can be proven.
-
Timing matters: The transitional period around 2026 is decisive — technology choices made today (insulation compounds, conductor sizing, harness architectures) will scale through the later part of this forecast and lock in supplier economics and OEM integration models.
Key dynamics reshaping demand and supply
-
Electrification and system complexity: Increasing adoption of battery electric vehicles (BEVs) and hybrid systems is raising average cable counts, introducing high-voltage architectures, and accelerating demand for specialty cables (high-voltage, battery interconnects, sensor cabling). These trends raise per-vehicle wire and cable content and change supplier qualification hurdles.
-
Regulatory overlay: Regional and international regulations are tightening material and safety requirements. Notably, European mandates are moving towards halogen-free cable materials to limit toxic gas release in fires, and new insulation compounds demonstrating flame resistance beyond 850°C have become commercially available and are being specified in over 35 vehicle-producing countries. Compliance with UNECE WP.29 and ISO 6722 test regimes has become table stakes for global OEM supply.
-
Raw material volatility: Copper remains the dominant conductor metal, and price moves materially affect cost pass-through and margin for vertically integrated vs. merchant cable suppliers. As of late March 2026 the reference copper price was about USD 5.44/lb, down from an early-2026 peak near USD 6.58/lb — a reminder that procurement strategies and hedging discipline materially impact competitiveness.
-
Supply chain resilience and localization: Pressure to shorten supply chains, combined with trade dynamics and localized EV ecosystems, makes manufacturing footprint strategy a critical differentiator. Suppliers that balance local content with centralized technology hubs will hold the strongest positions.
Strategic implications for 2026 decisions
-
Prioritize materials and safety compliance investments now. Shifts to halogen-free compounds and high-temperature ratings are not incremental — they alter process flows, supplier qualification timelines, and testing investments. OEMs and tier-1s that front-load validation in 2026 will avoid costly requalifications as regulations become more prescriptive.
-
Differentiate on systems integration rather than commodity conductors. With market fragmentation and mid-single-digit CAGR, premium margin pools will favor suppliers who bundle connectivity, harness engineering, and electronic connectivity systems — not those competing purely on raw copper price.
-
Hedge raw material exposure and optimize procurement cadence. Given observed copper price volatility, firms should combine long-term contracts, active hedging, and design choices that limit conductor overspecification without jeopardizing performance.
-
Opportunity windows for consolidation and niche plays. The recent acquisition activity in the sector signals M&A appetite: buy-side players should evaluate tuck-ins that add EV-capable product lines or regional footprint; sell-side players should assess whether scale or niche specialization maximizes exit valuation.
Competitive landscape — who matters and why
The market is populated by a mix of global wiring-system integrators and specialized cable manufacturers. Seven companies merit attention for strategic benchmarking and partnership screening:
-
Furukawa Electric Co., Ltd. (Tokyo) — recognized for high-performance wiring harnesses and specialty cables tailored to EVs and autonomy platforms. Their strength lies in combining materials expertise with system-level harness engineering.
-
Southwire Company (Carrollton, GA) — a strong North American presence notable for power cables and harness components; an important competitor where scale in commodity and semi-custom cable solutions matters.
-
TE Connectivity (Schaffhausen) — offers a wide portfolio across sensor cable, power assemblies, and modular connectivity solutions; excels at component-level engineering that supports rapid OEM adoption.
-
Yazaki Corporation (Tokyo) — a global leader in wire harnesses and in-vehicle networks; its deep OEM relationships and systems experience make it a standard-setting supplier in many vehicle platforms.
-
Leoni AG (Nuremberg) — historically strong in automotive wiring systems; its Automotive Cable Solutions division was acquired in July 2025 by TIME Interconnect (a Luxshare-ICT subsidiary), reshaping competitive dynamics and illustrating consolidation drivers.
-
Sumitomo Electric Industries (Osaka) — offers high-voltage automotive wires and cables focused on EV and powertrain applications; notable for materials science capabilities.
-
Coroplast Fritz Müller GmbH & Co. KG (Neumünster) — provides cable management and protective tapes alongside wire and cable products; they showcased e-mobility solutions at the Battery Show Europe in June 2026, underscoring the importance of complementary products for battery and EV systems.
Recent signals and what they mean
-
Leoni’s Automotive Cable Solutions acquisition (July 2025) signals acquisitive pressure from larger electronics assemblers seeking vertical integration into wiring systems — a trend that can accelerate consolidation or strategic partnerships in 2026.
-
Trade show activity such as Coroplast’s Battery Show Europe participation (June 2026) reflects increasing OEM and supplier attention to cable management solutions specific to battery systems — an area where adjacent capabilities (adhesives, tapes, protection systems) create differentiation.
-
Regulatory and materials trends, as noted above, are forcing a simultaneous expansion in product performance and a re-evaluation of manufacturing processes. This dual pressure increases capital intensity for established players and raises the bar for new entrants.
What our full report delivers (practical, operationally focused)
The full Automotive Wire and Cable Market study is built as an executive-grade playbook and a practitioner toolkit. Key deliverables include:
-
A validated market-sizing model (2020–2025 historical, 2026–2032 forecast) calibrated to industry shipment and content trends.
-
Scenario-based demand modeling that isolates the impact of EV penetration, high-voltage adoption, and regulatory shifts on total cable content per vehicle.
-
Supplier scorecards that compare technology breadth, manufacturing footprint, margin profiles, and OEM exposure for the major players noted above.
-
Procurement and cost-sensitivity tools that quantify the P&L impact of raw-material swings and alternative conductor or insulation choices.
-
Playbooks for M&A and partnership assessment, including integration checklists and valuation adjustment frameworks for technology and footprint synergies.
-
A prioritized roadmap for R&D and capital investment decisions, with time-bound recommendations for material qualification, pilot lines, and compliance testing.
How leaders should use this intelligence in 2026
-
Supply chain leaders: Rebaseline supplier risk scores using the report’s supplier maps and the copper price sensitivity analyses; re-run sourcing scenarios that reflect localized EV production hubs.
-
Product and engineering heads: Use the scenario modeling to choose between conservative overdesign vs. optimized conductor strategies; time the introduction of halogen-free materials to align with platform refresh cycles.
-
Corporate development teams: Apply the M&A playbooks to triage targets that add EV-specific capabilities, regional scale, or complementary product lines (e.g., cable management systems).
-
R&D and quality: Prioritize investments in materials testing and flame-retardant compound qualification to meet UNECE WP.29 and ISO 6722 windows and avoid rework cycles.
Accessing the granular intelligence
This article is designed as a strategic trailer: it frames the opportunity, the risks, and the choices that will shape competitive positions through 2032. The full report contains the granular segmentation, regional breakdowns, and numeric scenario outputs that are essential for transaction diligence, capital planning, and engineering-spec rollouts. Those detailed tables and the interactive models are intentionally omitted here to focus on actionable strategy; they are available through the PW Consulting report portal.
Closing — the practical next steps for 2026
Decisions taken in 2026 about material sourcing, investments in halogen-free and high-temperature insulation, and partnership or acquisition targets will determine who captures the higher-margin, system-level opportunities in the next product cycle. The market’s scale, the mid-single-digit growth trajectory, and a fragmented supplier base together create a fertile field for targeted investments and strategic consolidation — but only for organizations that align procurement, R&D, and corporate development around a unified 3–5 year plan. Use the report to translate the headline growth into prioritized actions, testable assumptions, and financial scenarios that fit your risk tolerance and strategic ambitions.
For detailed analysis of this topic, please visit the official page: Automotive Wire and Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com