

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ultrasound Market — USD 8.59B in 2025, 5.97% CAGR to 2032

Ultrasound Market 2026: Strategic Preview for Decision Makers
Executive preview
As organizations plan capital allocation and go-to-market moves for 2026, ultrasound technologies are no longer a peripheral efficiency play — they are a structural lever across manufacturing, clinical, and food-processing value chains. PW Consulting’s Ultrasound Market research uses a 2025 base year and a 2026–2032 forecast horizon to translate observed adoption patterns into practical strategic actions. The global market has expanded materially since 2020 (from a mid‑single‑digit billion-dollar base) to an estimated USD 8.59 billion in 2025, and our model projects steady expansion at a 5.97% compound annual growth rate into the forecast window, reaching a projected USD 12.87 billion by 2032. This trajectory creates a set of timing, capability and partnership decisions that will determine winners and laggards in 2026 and beyond.
Ultrasound Market
Why this matters for 2026 choices
-
Investment horizon compression: With predictable, multi-year growth and improving unit economics for advanced sonication and ultrasonic cutting systems, 2026 is a decision year for firms that have deferred upgrades. The expected market momentum reduces adoption risk for first movers who can show short-term ROI through yield improvements and total cost of ownership reductions.
Ultrasound Market -
Operational differentiation: Ultrasonic systems now deliver more than marginal gains — they enable new product forms (multi-layer, sticky, frozen), higher line speeds, and measurable OEE uplifts. Food producers, OEMs and medical-device manufacturers that embed ultrasonic capabilities into their processes can convert process advantages into sustainable commercial differentiation.
Ultrasound Market -
Regulatory and procurement alignment: Several food‑grade certifications and inert-material endorsements (for example, titanium ultrasonic knives) have lowered regulatory friction and accelerated procurement cycles. In practice, that makes pilot-to-scale transitions faster in 2026 than in prior years.
Market dynamics shaping near-term strategy
-
Technology convergence: Innovations in generator design, sonotrode materials and modular system architectures have broadened the set of feasible use cases. Examples from 2024–2025 product introductions (from ultrasonic cutting upgrades to novel non-contact thawing systems) point to a two-track market: incremental replacements of legacy mechanical systems and new applications unlocked by emergent form factors.
-
Service and aftermarket economics: As installed bases mature, recurring service, retrofits and consumables will constitute a meaningful portion of supplier economics. Players that invest in remote monitoring, predictive maintenance and rapid field-service models will capture higher lifetime value per unit sold.
-
Concentration and competitive dynamics: The market exhibits a moderate-to-high level of supplier concentration among incumbent technology leaders, and the top three to five suppliers account for a substantial share of global shipments. That creates both opportunity for challengers (via niche specialization and systems integration) and barriers for entrants (scale, distribution, and certification).
-
Regulatory and hygienic standards: Food‑certified ultrasonic systems and inert-material approvals have removed a key hurdle for adoption in highly regulated production environments. This regulatory clarity reduces procurement risk and shortens the payback calculus for 2026 investments.
What the full report delivers (practical, actionable content)
PW Consulting’s full Ultrasound Market report is structured for rapid decision-making. It is not an academic survey — it is a playbook.
-
Market sizing and trajectory: historical performance to 2025 and modelled scenarios across the 2026–2032 forecast window, with sensitivity testing under alternative adoption rates and price erosion assumptions.
-
Go-to-market frameworks for vendors: channel strategies, OEM partnering archetypes, and timing templates for product launches, prioritized by risk-adjusted ROI.
-
Use-case ROI toolkits: pre-built financial templates that quantify expected gains from portioning, sealing, cleaning, and thawing applications, calibrated to typical line speeds and asset lifecycles.
-
Technology readiness and upgrade roadmap: component-level risk assessment (sonotrode longevity, generator obsolescence, integration complexity), plus a recommended staged rollout plan for piloting and scaling in 2026.
-
Regulatory & compliance playbook: certification checklists, hygienic design requirements, and procurement language to accelerate approval in regulated food and clinical contexts.
-
Competitive supplier scorecards: capability matrices, channel footprints, and partnership fit assessments to support make vs. buy decisions — presented as decision filters rather than raw rankings.
-
M&A and partnership playbook: identify strategic acquisition profiles, valuation heuristics for tuck‑ins, and non-dilutive collaboration structures aligned with growth goals for 2026.
Competitive landscape: what to watch in 2026
The supplier ecosystem is populated by specialist ultrasonic manufacturers and diversified industrial players. Each brings a different strategic posture — product depth, system integration, or channel reach — and our strategic profiles emphasize the implications for buyers and investors.
-
Hielscher Ultrasonics (Teltow, Germany) — Known for high‑performance homogenizers and probe‑type sonicators, Hielscher’s portfolio targets extraction, emulsification and continuous-flow food processing. Their stepped plate and intensified sonication concepts are relevant for frozen-food thawing pilots.
-
Emerson Electric Co. (St. Louis, USA) — Through Branson, Emerson has advanced ultrasonic cutting systems and cleaners focused on confectionery, bakery and dairy portioning. Recent product renewals underscore an emphasis on throughput and reduced waste for high-speed lines.
-
RINCO ULTRASONICS (Germany) — Specializes in ultrasonic welding and cutting for portioning and packaging automation. Their solutions are optimized for residue-free cuts and integration into automated production lines — an attractive profile for processors seeking lower maintenance footprints.
-
TELSONIC AG (Bronschhofen, Switzerland) — Offers cutting sonotrodes and generators with a strong emphasis on packaging sealing and confectionery portioning. Their systems are frequently deployed where precision and packaging integrity are critical.
-
Weber Ultrasonics (Germany) — Modular ultrasonic platforms oriented toward industrial cutting, sealing and utensil cleaning; notable for hygiene-focused applications and aftermarket service models.
-
Dukane (Illinois, USA) — Focuses on ultrasonic knives and generators that deliver clean, non‑sticking cuts in multi-layer bakery and cheese products. Material choices and inertness claims (e.g., titanium contacts) address regulatory concerns.
-
Herrmann Ultrasonics (Germany) — Offers food-certified sealing and cutting solutions that emphasize reduced maintenance and improved overall equipment effectiveness (OEE), which can materially shorten payback periods.
-
Marchant Schmidt (USA) — Strong in high-volume sheet-product cutting systems; their recent two-stage cutters target frozen-meal and bakery lines where throughput and consistency matter.
-
Sonics & Materials, Inc. (USA) — Provides processors and welding equipment for liquid and high-volume food lines; their portfolio supports integration into existing processing footprints.
Notable 2024–2025 developments — from new-generation cutting systems to specialized non‑contact thawing solutions — indicate an R&D cycle that will drive product refreshes and create procurement windows in 2026. Suppliers that convert innovation into field-proven reliability will gain disproportionate share.
Strategic imperatives for stakeholders in 2026
-
For equipment vendors: prioritize modular, serviceable platforms and embed predictive maintenance. Offer pilot-to-scale pricing that transfers operational risk and accelerates customer adoption.
-
For food processors and OEMs: run targeted pilots in 1–2 high-variance product lines to validate yield and OEE improvements before rolling out broadly. Use procurement windows created by supplier product cycles to negotiate upgrade packages and lifecycle service commitments.
-
For investors and acquirers: look for assets that combine proprietary sonotrode or generator IP with recurring service streams. Valuation should emphasize installed-base monetization and channel exclusivity rather than one-off equipment sales.
-
For systems integrators and service providers: build hygienic-design expertise and certification capabilities, because regulatory clarity (e.g., food-grade ultrasonic approvals) is enabling broader adoption and creates service differentiation.
How to use the report in your 2026 planning
The report is designed as an operational toolkit. If you are building a 2026 roadmap, use it to:
-
Prioritize pilot projects using our ROI templates and risk scenarios;
-
Negotiate supplier contracts anchored to demonstrated OEE gains and service SLAs;
-
Design an M&A screen to identify strategic tuck-ins that accelerate market entry or add service revenue;
-
Align procurement and regulatory teams to compress approval timelines for food‑certified ultrasonic equipment.
Final note — the trailer principle
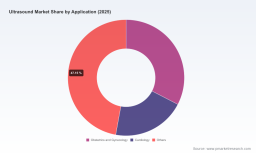
We have presented the directional insights and strategic implications that matter for 2026 without revealing the granular segmentation and supplier scorecards that operational teams need to execute. PW Consulting’s full Ultrasound Market report contains the detailed regional and application splits, vendor financial proxies, complete scorecards, and downloadable financial models referenced in this preview. For practitioners who need executable plans — procurement-ready RFx language, validated ROI models, and integration checklists — the full dossier provides the playbooks and data tables to act in 2026 with confidence.
Call to action
Contact PW Consulting to obtain the full Ultrasound Market report and the accompanying implementation toolkits. Move from insight to action — validate pilots, set procurement timelines, and secure competitive advantage before the 2026 procurement cycles peak.
For detailed analysis of this topic, please visit the official page: Ultrasound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com