

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Construction Chemicals to Top USD 101,500 Million by 2032 at 6.5% CAGR

Construction Chemicals Market 2026: Strategic Outlook and Decision Playbook
Executive snapshot
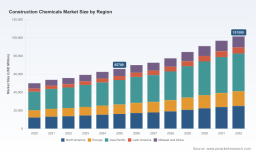
The global construction chemicals market has demonstrated steady expansion through the first half of the decade, rising from a base of roughly USD 50 billion in 2020 to an estimated USD 65.7 billion in 2025. Our forecasts — reflecting technology adoption, urbanization trajectories and infrastructure pipelines — project a continued compound annual growth rate (CAGR) of approximately 6.5% for the period 2026–2032, driving the market above USD 100 billion by 2032. For executives setting strategy in 2026, these topline dynamics matter: they create a multi-year window to scale profitable product platforms, reconfigure supply footprints, and capture share before the market mid‑cycle rebalances around new regulatory and raw-material regimes.
Construction Chemicals Market
Why this report changes 2026 decisions
- Actionable foresight, not just numbers: The research translates macro growth into decision-ready scenarios — from conservative to accelerated adoption — enabling capital-allocation choices that are defensible under multiple commodity and policy outcomes.
- Margin-first playbooks: The analysis prioritizes product and channel combinations that maintain margin resilience under raw-material inflation and should inform pricing and contract strategies for FY‑2026.
- Supply‑chain imperatives: With recent upstream tightness in key chemistries, the report offers supplier risk matrices and hedging frameworks tailored to construction‑chemical formulations.
- Regulatory and sustainability roadmaps: New product compliance requirements and green procurement curves are translated into product development roadmaps and commercialization timelines.
What the report contains — practical, operational chapters
This study was built with the practitioner in mind. Rather than a high-level narrative, it contains playbooks and executable modules designed for immediate adoption within 90–180 days by corporate strategy, commercial, R&D and supply‑chain teams.
Construction Chemicals Market
- Market model and forecast engine — an interactive baseline that maps demand drivers to revenue trajectories across 2026–2032, with scenario toggles for commodity price shocks and policy shifts.
- Value‑chain cost-to-serve analysis — componentized cost models for common product families, allowing rapid margin simulation under different raw-material sourcing assumptions.
- Segmentation and go‑to‑market playbooks — prioritized routes to market by customer-profitable cohorts, distributor strategies, and specification-influencing stakeholders.
- Regulatory compliance checklist — a practical compendium for new product registration, labelling, and the latest EU product regulation implications, including timelines and compliance cost estimates.
- Product innovation roadmap — R&D investment matrices highlighting formulation substitutions, low‑VOC/sustainable chemistries and retrofit-friendly systems with commercialization milestones.
- M&A and partnership playbook — target archetypes, valuation sensitivities, and integration checklists focused on capability gaps and regional access.
- Supplier-risk & sourcing playbook — supplier concentration heatmaps, continuity planning, and contract structures to reduce exposure to volatile commodity swings.
- Competitive benchmark pack — strategic profiles and tactical scorecards for leading vendors (product breadth, geographic strength, manufacturing footprint, and recent inorganic moves).
Competitive landscape — what the leading players are signaling
The market is shaped by a mix of global systems providers and regional specialists. Leading diversified chemical and building-materials groups maintain advantaged positions through broad product portfolios, specification relationships, and increasingly through strategic acquisitions and targeted capacity investments.
Construction Chemicals Market
- Sika AG remains the benchmark for integrated systems — strong in admixtures, waterproofing, adhesives and floor systems — and continues to compete on systems bundling and contractor-level technical support.
- BASF’s Master Builders Solutions has doubled down on manufacturing capacity in strategic geographies; recent U.S. expansions reflect a play to shorten lead times for admixtures and to service fast‑growing infrastructure projects.
- MAPEI and Pidilite are executing a differentiated strategy focused on trade channels, adhesive technologies and localized technical services, preserving margin through channel control.
- Dow, Arkema, Wacker and Nouryon play as upstream enablers: their specialty polymers and additives underpin many value-added formulations; volatility in their feedstocks can cascade into pricing for finished systems.
- Saint‑Gobain’s recent string of acquisitions has materially reshaped competitive positioning, particularly in waterproofing and emerging‑market distribution. The integration of targeted regional players accelerates its pathway to full-system offerings across geographies.
- RPM, GCP, Fosroc (now integrated into larger groups) and Chryso represent focused-play competitors — fast to market with technical innovations and agile commercial models to serve repair, retrofit and infrastructure niches.
Collectively, the top global players command a majority of market influence — creating a backdrop where scale, local service capability and formulation IP determine long-term winners.
Dynamics, headwinds and near-term shocks to plan for in 2026
- Raw‑material volatility: Recent months saw sharp movements in key precursors — from isocyanate derivatives to silicone intermediates and styrenic monomers — imposing margin compression unless mitigated by contracts or pass-through clauses.
- Regulation acceleration: New EU product compliance requirements and tightened green procurement rules are already affecting product portfolios and time-to-market. Firms that preempt compliance requirements will avoid costly reformulation sprints.
- Consolidation and local integration: Buyers are consolidating purchasing and favoring suppliers able to offer system-level warranties. Expect further M&A activity as global players seek to lock in distribution and specification channels in growth regions.
- Sustainability and specification shifts: Demand for low‑carbon, low‑VOC and circular‑material solutions is moving from niche to structural — a design requirement for many public tenders and large private developers.
Immediate strategic moves for 2026
Below are prioritized actions that we advise companies to implement within the next 12 months. These are practical, measurable, and aligned with the market trajectory reflected in our forecast.
- Embed scenario-based capital planning: Build three capital-allocation scenarios (base, stress, accelerate) that link capacity investments to commodity price thresholds and policy milestones.
- Protect margins with a two‑track commercial policy: adopt smarter contract clauses for pass-through pricing while piloting formulation changes that reduce reliance on the most volatile feedstocks.
- Accelerate product compliance readouts: dedicate a cross-functional rapid-response team to address new construction product regulations and tender-readiness for green specifications.
- Target bolt-on M&A in distribution and specification expertise: prioritize targets that close gaps in local technical service, standards certification and channel control rather than only incremental product lines.
- Implement supplier dual-sourcing for critical intermediates and negotiate inventory buffers tied to take-or-pay instruments to stabilize supply through 2026 shocks.
- Operationalize sustainability: integrate lifecycle benchmarking into product pricing and create a fast-track certification process to win public tender business that favors low‑carbon solutions.
How PW Consulting supports your 2026 agenda
Our Construction Chemicals Market study is more than a market map — it is a toolkit for execution. PW Consulting offers tailored modules to operationalize the report within your organization:
- Bespoke scenario modeling linked to your product portfolio and regional footprint.
- Targeted due diligence on acquisition candidates, including revenue synergy and integration playbooks.
- Supply-chain stress tests and raw-material hedging strategies with supplier ranking and negotiation scripts.
- R&D prioritization matrices to accelerate reformulation for regulatory and sustainability compliance.
- Commercial transformation plans to optimize distributor networks, specification penetration and pricing governance.
Next steps — where the full intelligence lives
This introduction outlines the strategic value executives can extract from a timely, operationally oriented study as they make pivotal 2026 decisions. The full report contains the granular datasets, chapter-level sensitivity tables, and company scorecards that will allow teams to convert strategy into a concrete 90‑day action plan. For organizations preparing board papers, capital requests or integration plans, accessing the complete dataset and playbooks is the next logical step.
Contact our team to schedule a briefing and to obtain the interactive forecast model and executable templates that will align your 2026 priorities with the market’s trajectory.
For detailed analysis of this topic, please visit the official page: Construction Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com