

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Auto Cylinder Sleeve Market USD 6.18B (2025) to USD 8.82B by 2032 at 5.2% CAGR

Automobile Cylinder Sleeve Market — 2026 Strategic Preview
Preamble: why this preview matters
As OEMs, tier suppliers, investors and policy-makers prepare for critical allocation and capital decisions in 2026, a focused, evidence-backed view of the automobile cylinder sleeve market is indispensable. PW Consulting’s latest study — with a 2025 base year, a historical window covering 2020–2025 and a forecast horizon running through 2032 — synthesizes market sizing, technology trajectories, regulatory impact and supplier economics into a practical playbook. The market has expanded markedly in recent years (from roughly USD 3.7 billion in 2020 to about USD 6.18 billion in 2025) and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.2% over the 2026–2032 period, reaching an estimated USD 8.8+ billion by 2032. This preview highlights the strategic implications embedded in that growth path and helps leaders prioritize where to compete and how to allocate scarce engineering and capital resources in 2026.
Automobile Cylinder Sleeve Market
What corporate decision-makers will gain from this study
Our research translates market trends into actionable decisions across three strategic horizons:
Automobile Cylinder Sleeve Market
- Immediate (next 12 months): sourcing and supplier-risk mitigation — tactical levers to secure production continuity and control input-cost exposure.
- Near-term (12–36 months): product portfolio and manufacturing footprint decisions — which liner technologies and materials merit investment, scale-up or retirement.
- Medium-term (36–72 months): M&A, joint-development and business-model moves — options to consolidate capabilities, capture aftermarket value, or pivot toward advanced materials and coatings.
Market dynamics shaping 2026 choices
Several interlocking forces are determining where demand for cylinder sleeves will concentrate and how supply economics will evolve:
Automobile Cylinder Sleeve Market
- Regulatory tightening: Emissions and fuel-efficiency standards (for example, the most recent Euro and Bharat updates) are increasing engine thermal loads and service-interval expectations. That drives demand for liners with higher thermal fatigue resistance and dimensional stability — a non-negotiable requirement for OEM powertrain specifications.
- Material and manufacturing evolution: While traditional cast-iron solutions remain foundational for many engine programs, the industry is witnessing steady adoption of lightweight aluminum and composite alloys paired with thin-wall or cast-in liner approaches to meet vehicle-mass reduction targets. Concurrently, advanced casting and coating techniques (centrifugal casting, silicon-aluminum composites, specialized surface coatings) are improving running surfaces, heat transfer and friction characteristics.
- Engine portfolio mix and the electrification transition: The shift to electric vehicles reduces long-term growth potential for internal combustion components in some end-markets, but ICE powertrains remain the dominant installed base across many regions and vehicle classes for the forecast horizon. Strategic players must therefore balance investment in incremental ICE improvements (efficiency, durability) with hedged bets on adjacent technologies and aftermarket monetization.
- Supply-side concentration and competitive posture: The market is best described as moderately fragmented — a set of established global suppliers coexist with regional specialists and emerging material innovators. This structure creates both opportunities for scale-driven cost leadership and niches for differentiated technology plays.
- Raw-material and input-cost volatility: Steel, cast iron feedstock and specialized alloy inputs present periodic price swings. Manufacturers that lock supply, vertically integrate critical processes, or design material-agnostic platforms will gain margin resilience.
Technology and product trends to watch in 2026
Technological progress in the cylinder sleeve space is concentrated across three dimensions: materials, surface engineering and manufacturing methods. Key developments that will influence vendor selection and CAPEX decisions include:
- Advanced alloy formulations and composites that reconcile wear resistance with lower mass. Recent product introductions — for example, silicon-aluminum composite liners — demonstrate an industry pivot toward hybrids that retain performance while shaving weight.
- Surface coatings and micro-texturing that reduce friction and improve lubricant retention, enabling tighter combustion tolerances required by the newest emissions regimes.
- Centrifugal casting and patent-protected cast-in approaches that facilitate thin-wall liner integration with aluminum blocks, enabling OEMs to meet stringent fuel-economy targets without compromising durability.
For procurement and engineering teams, the implication is clear: qualification roadmaps must explicitly include coating vendors, manufacturing-process validation, and life-cycle testing regimes aligned with regulatory timelines.
Competitive landscape — what incumbents and challengers are doing
The sector’s competitive dynamic blends legacy OEM-tier incumbents, regional champions and material innovators. The following high-level positioning captures each firm’s strategic footprint and the implications for partnerships, supplier consolidation and customer lock-in:
- MAHLE GmbH (Stuttgart, Germany) — Strengths lie in in-house centrifugal cast cylinder liners tailored for passenger and commercial vehicle engines, including large-bore applications. Their emphasis on robust materials and low-wear running surfaces positions them as a go-to supplier for OEMs requiring validated production scalability and stringent OE specifications.
- Tenneco Inc. (Ann Arbor, USA) — Offers advanced liners with focus on optimized materials, coatings and designs that enhance heat transfer and reduce friction. Their breadth across light- and heavy-duty segments makes them a strategic partner for OEMs seeking platform-wide standardization of running-surface performance.
- TPR Co., Ltd. (Osaka, Japan) — Notable for patented cast-in liner technologies (e.g., AsLock®) and thin-wall wet/dry liners compatible with aluminum blocks, TPR is embedded in Japanese OEM supply chains and represents a model for tight OEM-supplier co-development.
- Kolbenschmidt GmbH (Frankfurt, Germany) — Integrates cylinder liners within a broader piston-system portfolio, emphasizing OE-grade performance and engineering alignment with piston and ring systems.
- Zhongyuan Cylinder Liner Company (China) & Aichi Machine Industry (Japan) — Regional players with competitive manufacturing scale and localized go-to-market advantages. They illustrate how regional supply flexibility and cost positioning influence OEM sourcing strategies.
Recent industry movements underline two strategic themes: product innovation and consolidation. New material launches (e.g., silicon-aluminum composite liners) and M&A moves among piston and liner specialists are compressing technology cycles and reducing time-to-qualification for advanced solutions. As consolidation continues in pockets, first-mover OEMs and suppliers that secure long-term development agreements will enjoy preferential access to technology roadmaps and capacity allocation.
Strategic implications and recommended actions for 2026
To convert market insight into defensible action plans, executives should prioritize the following:
- Define a clear material strategy: establish criteria for where traditional cast iron remains optimal vs. where lightweight alloys or composites deliver net lifetime value considering fuel-efficiency gains, warranty exposure and system-level weight targets.
- Lock in supplier partnerships with technology co-investment: move beyond transactional procurement toward joint development agreements that accelerate coating and casting validation while securing preferential capacity.
- Hedge raw-material exposure: implement layered procurement strategies that combine long-term contracts, strategic inventory buffers and flexible alloy sourcing to reduce input-cost-driven margin volatility.
- Rationalize production footprint using a hybrid model: retain strategic high-tech processes close to engineering centers while outsourcing volume casting to cost-efficient regional partners — but include strict quality oversight and inventory buffers for critical bore sizes.
- Pursue selective M&A or minority investments in material innovators and surface-coating specialists to accelerate access to next-generation solutions without fully internalizing R&D risk.
- Embed regulatory-forward testing protocols into product development cycles to ensure new liner designs meet evolving emissions and service-interval standards from day one.
- Develop aftermarket and service strategies: as ICE fleets remain sizable through the forecast window, aftermarket parts and reconditioning services present attractive, lower-capex revenue streams.
What the full report delivers (practical scope)
The full PW Consulting report translates the themes summarized above into instruments leaders can use immediately in 2026 planning cycles. Highlights include:
- Validated historical market sizing (2020–2025) and a transparent forecasting model covering 2026–2032, with scenario and sensitivity analyses centered on key variables (material adoption rates, regional demand shifts, regulatory stringency and input prices).
- Operationally relevant supplier benchmarking: production methods, quality certifications, capacity constraints, lead-times and commercial terms typically observed in OEM contracts.
- Risk and resilience maps: supplier-concentration heatmaps, single-source risk, and mitigation strategies suited to different corporate risk appetites.
- Technology deep dives and qualification roadmaps for incumbent and emerging liner types (including manufacturing process flowcharts, test protocols and cost-to-produce models).
- Go-to-market and M&A playbooks with prioritized target profiles, valuation heuristics, and integration checklists to accelerate deal execution.
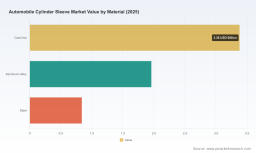
To preserve the strategic value of the full analysis and models, we have intentionally withheld granular segment-by-segment numerical breakdowns in this preview. The full dataset — including detailed regional and application splits, supplier market-shares and price curve assumptions — is accessible via the PW Consulting portal and is the recommended input for finalizing 2026 capital and sourcing decisions.
Concluding note — navigating 2026 with clarity
The cylinder sleeve market’s trajectory through the next funding and product-development cycles is shaped by modest, steady growth (CAGR ~5.2%), evolving materials science, regulatory tightening and a supplier landscape that rewards both scale and specialization. For executives, the near-term imperative is to embed flexibility into sourcing and product portfolios, secure co-development arrangements with technology leaders, and use scenario-driven forecasting to protect margins against material-price and regulatory shocks. PW Consulting’s full report provides the numerical granularity, supplier-level intelligence and executable roadmaps to convert these strategic priorities into measurable 2026 outcomes.
For detailed analysis of this topic, please visit the official page: Automobile Cylinder Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com