

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gel Documentation Market to Reach USD 490M by 2032 at 5.45% CAGR

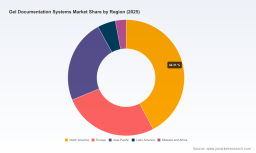
Gel Documentation Systems Market — Strategic Outlook for 2026 Decision Makers
As laboratories, biotechs, and diagnostics providers prepare strategic budgets and product roadmaps for 2026, firms face a deceptively simple choice: treat gel documentation systems as a routine capital purchase, or reposition them as a strategic node that influences R&D velocity, regulatory readiness, and downstream service revenues. PW Consulting’s new market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) quantifies that the global gel documentation market stood at USD 337.0 Million in 2025 and, at a compound annual growth rate of 5.45%, is projected to approach USD 490.0 Million by 2032. This briefing distils the implications of that trajectory for firms making decisions in 2026 without disclosing the granular segmentation that drives our proprietary model — those details are reserved for subscribers and the full report.
Gel Documentation Systems Market
Why this report matters for 2026 planning
-
Shift from commoditised hardware to systems-level value: The market expansion is not uniform across suppliers or use cases. What used to be a buyer’s market for standalone imaging boxes is evolving into a market for systems that bundle hardware, cloud-enabled analysis, and compliance-ready data management. Procurement teams that ignore software and lifecycle services risk higher total cost of ownership and slower compliance turnaround.
Gel Documentation Systems Market -
Regulation and lab accreditation are forcing structural purchases: With increasing emphasis on ISO 17025 and laboratory quality assurance, organizations must prioritize imaging solutions that provide auditable, tamper-evident records and validated workflows. The pace of purchases in 2026 will be driven as much by regulatory calendars as by pure R&D demand.
Gel Documentation Systems Market -
Supply-chain fragility impacts timing and cost: Persistent semiconductor bottlenecks and logistics constraints remain a near-term risk to equipment manufacturers and purchasers alike. Organizations should expect elongated lead times and price volatility for certain imaging components, influencing CAPEX scheduling and inventory strategies.
What the market trajectory implies for strategy
-
Opportunity in adjacent services: As pricing competition compresses margins on entry-level instruments, higher-margin opportunities emerge in software licenses, analytic modules, maintenance contracts, and cloud-based data workflows. Companies that build or partner for analytics and compliance modules can capture recurring revenue and lock-in labs through validated workflows.
-
Product roadmap reorientation: Vendors should prioritize modular platforms that support multi-mode imaging (fluorescence, chemiluminescence, visible light) and scale across lab types. R&D investment should be balanced between optics/electronics and user-facing analytics — buyers value reproducibility and easy integration with lab information systems as much as raw resolution.
-
M&A and consolidation vectors: The current market concentration suggests leading players command meaningful share but gaps remain for specialized or regional challengers. Expect continued consolidation around software, AI analytics, and service ecosystems rather than pure hardware, as acquirers seek to accelerate time-to-market for validated end-to-end solutions.
Competitive landscape — who shapes buyer choices
The competitive set includes established life-science OEMs and several specialized imaging vendors. Each brings differentiated propositions that matter for procurement committees:
-
Bio‑Rad Laboratories (Hercules, CA) — Known for systems such as GelDoc Go and GelDoc XR+ and integrated Image Lab software; recent product launches incorporate AI-assisted analysis, signalling a push to embed advanced image interpretation into routine workflows.
-
Thermo Fisher Scientific (Waltham, MA) — Offers the iBright family and automated gel documentation solutions aimed at throughput and workflow automation in research and QC environments.
-
GE HealthCare (Chicago, IL) — Positions imaging platforms as part of broader diagnostic and electrophoresis documentation pathways, emphasizing precise quantification for regulated settings.
-
Syngene (Cambridge, UK), Analytik Jena (Jena, Germany), Cleaver Scientific (UK), LI‑COR Biosciences (Lincoln, NE), Vilber Lourmat (France), Azure Biosystems (Dublin, CA), ATTO Corporation (Tokyo), Major Science (USA) — Each offers niche strengths from compact, budget-conscious instruments to quantitative, publication-grade imagers with integrated analysis suites.
Collectively, the three largest firms capture a clear majority of market share, and the top five increase that concentration further — a dynamic that has important implications for pricing discipline, channel strategies, and partnership negotiation leverage.
Recent developments to watch
-
AI-enabled image analysis: One leading vendor launched an AI-infused imaging system in 2025 that automates band recognition and quantification, setting a new benchmark for end-user expectations on analysis speed and objectivity. Vendors who do not accelerate software capabilities risk relegation to price competition.
-
Quality and compliance enforcement: Regulators and accreditation bodies have amplified expectations for auditable imaging and data retention. Equipment that supports secure, validated workflows will command premium consideration during procurement.
-
Component availability constraints: Continued semiconductor and logistics issues mean manufacturers must design supply-resilient architectures and transparent lead-time commitments into 2026 purchasing plans.
Report contents — what PW Consulting delivers (practical, actionable elements)
This study is designed for C-suite executives, product leaders, procurement heads, and corporate development teams who need to make material decisions in 2026. The full report includes:
-
A top-down market model (historical and forecast) with sensitivity testing and scenario outputs that stress-test growth assumptions under alternative regulatory, supply-chain, and innovation scenarios.
-
Demand-side segmentation by region, product type, light source, detection technique, application, and end-user — modelled with a transparent methodology and accompanied by heat maps that expose pockets of accelerated adoption. (Note: granular segment figures are contained in the full report.)
-
Buyers’ decision framework — procurement checklists, TCO comparators, validation and qualification KPIs, and vendor evaluation scorecards tailored for ISO-compliant labs.
-
Competitive benchmarking — feature-function matrices, software capability scoring, post-sales service metrics, channel and pricing strategies, and patent/technology mapping to identify white-space and defensive plays.
-
M&A and partnership playbook — target screening criteria, premium drivers, integration pitfalls, and a short-list of strategic acquisition archetypes that make sense in a concentrated market.
-
Supply-chain and manufacturing risk assessment — component exposure analysis and recommended mitigation strategies including dual-sourcing, buffer inventory guidelines, and design adjustments to reduce semiconductor dependency.
-
Implementation roadmaps for buyers and vendors — from pilot selection to validation to scale-up, including templates for proof-of-concept, data migration, and change-management to ensure adoption and regulatory acceptance.
How to use the insights in 2026 decision cycles
-
For equipment buyers — integrate software and compliance criteria into total cost evaluations. Push vendors for roadmap commitments on analytics and validated workflows; consider multi-year service agreements that cap maintenance uncertainty from supply constraints.
-
For product and R&D leaders — prioritize modular, software-centric development. Investing in reproducible analytics and audit trails delivers differentiable value far faster than incremental hardware upgrades alone.
-
For corporate development teams — assess acquisition targets that accelerate analytics or offer sticky service models. Valuation premiums will accrue to businesses that can demonstrate recurring revenues and validated compliance footprints.
-
For operations and procurement — implement lead-time buffers for critical components and qualify alternative suppliers. Negotiate supply contracts with explicit clauses for capacity allocation during disruptions.
What this analysis does not reveal — and why
In line with our “preview” approach, this article purposefully omits the granular segmentation figures and region/application-specific shares that underpin our market model. Those detailed data points — the specific breakdowns by region, product family, light source, detection technique, application, and end-user — are part of the full PW Consulting package and are essential for precise target-setting, budgeting, and deal negotiation. The summary above presents the strategic contours and executable recommendations you need to prioritize decisions in 2026; the full dataset converts those priorities into tactical actions and quantified roadmaps.
Final recommendations — three moves to make in 2026
-
Adopt a systems mindset: Treat gel documentation procurement as a multi-year capability build (hardware + software + compliance), not a one-off equipment purchase.
-
Prioritise analytics and validation: Allocate R&D and purchasing budgets toward solutions that reduce hands-on image processing and increase reproducibility for regulated workflows.
-
De-risk the supply chain: Lock in critical component supply and test alternative configurations now to avoid CAPEX delays and price spikes later in the forecast window.
For decision-makers preparing capital and product roadmaps in 2026, PW Consulting’s full Gel Documentation Systems Market report provides the actionable data and methodological transparency needed to convert strategic intent into measurable outcomes. Contact our research team to access the complete segmentation tables, downloadable financial model, and a tailored briefing for your organisation.
For detailed analysis of this topic, please visit the official page: Gel Documentation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com