

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cable Management Market to Reach USD 470.28 Million by 2032 at 9.25% CAGR

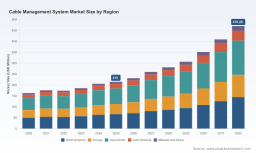
Cable Management System Market — Strategic Outlook for 2026 Decision‑Makers
As organizations plan capital allocation and product strategy for 2026, the cable management system market is moving from a mature, utility-style procurement category into a dynamic component of digital infrastructure and industrial resilience. Our latest PW Consulting market study synthesizes five years of historical performance and a rigorous 2026–2032 forecast to translate market dynamics into actionable choices. In brief: the market that measured roughly USD 215 million in 2025 is projected to expand at a compound annual growth rate of 9.25% over the forecast window, with a multi‑year trajectory that more than doubles the sector’s revenue base by the early 2030s. This growth is neither uniform nor risk‑free — it is concentrated at the intersection of data‑center scale‑outs, regulatory tightening, and supply‑chain volatility.
Cable Management System Market
Why this matters for 2026 corporate decisions
- Investment timing and prioritization: With a robust near‑term growth rate, 2026 is a pivot year for capitalizing on structural tailwinds (high‑density computing, electrification, and industrial automation). Companies that move early to secure manufacturing capacity, certification pipelines, and supply contracts will avoid the margin compression that follows commodity shockwaves.
- Product architecture and differentiation: Buyers are increasingly demanding modular, serviceable, and thermally aware cable management systems — particularly for liquid‑cooled and high‑density racks. This shifts value from raw materials into design, installation tooling, and integrated services.
- Regulatory and compliance risk: New and revised standards (notably the fourth edition of UL 62275 published in May 2025, ongoing NFPA 70 reorganization in 2026, and CLC/TS 50658:2025 on fire‑resistant systems) materially change certification roadmaps. Non‑compliance now risks exclusion from major infrastructure tenders and increased time‑to‑market.
- Supply‑chain resilience: Raw‑material price swings (steel, PVC, composites experiencing double‑digit volatility in early 2025) require procurement models that balance fixed contracts, hedging, and strategic vertical partnerships.
Key demand drivers shaping the market
- Data center expansion and densification: Continued investment in hyperscale and colocation facilities — including substantial U.S. construction spending — is intensifying demand for scalable cable routing, high‑density rack management, and liquid‑cooling compatible systems.
- Industrial digitalization and electrification: Manufacturing modernization, EV charging infrastructure, and distributed energy resources are driving non‑IT applications that require ruggedized and fire‑compliant cable containment solutions.
- Regulatory tightening and safety standards: New standards are raising the technical bar on mechanical performance, fire resistance, and traceability, pushing suppliers to invest in testing and certification early in the product lifecycle.
- Material and manufacturing innovation: Composite and polymer alternatives are gaining traction where corrosion resistance and weight reduction deliver operational value, while stainless and galvanized steels remain dominant where mechanical robustness is critical.
Strategic playbook for 2026 — recommended moves
- Rebalance portfolio toward high‑value systems: Prioritize modular solutions for data centers and certified fire‑resistant systems for critical infrastructure. Emphasize services — installation, lifecycle monitoring, and retrofitting — to capture recurring revenue.
- Accelerate certification pathways: Map regulatory change to product roadmaps now. Allocate engineering and testing capital to meet UL, NFPA, and CEN timelines; delayed certification is the fastest way to miss major tenders.
- Harden supply chains with multi‑tier strategies: Combine long‑term agreements for core metals with alternative sourcing for polymers and composites. Evaluate local assembly hubs to mitigate lead‑time risk for large regional projects.
- Commercial tactics for price volatility: Adopt indexed pricing clauses, value‑packaging (hardware + installation), and outcome‑based contracts for large installs where clients will accept higher upfront CapEx for predictable life‑cycle costs.
- Data‑center specialist go‑to‑market: Build partnerships with integrators and cooling OEMs. Productize rack‑level cable management that is pre‑tested for liquid‑cooling exposures and high‑density cabling scenarios.
What the PW Consulting report delivers (practical, executable content)
This study is oriented to action. We avoid abstract generalities and instead provide tools procurement, product, and strategy teams can use immediately:
Cable Management System Market
- Scenario‑based demand model covering conservative, base, and upside cases across 2026–2032 with sensitivity to data‑center capex and raw‑material swings.
- Stress‑tested financial templates for product launch ROI, incorporating certification timelines, material cost inflation, and service revenue assumptions.
- Supplier benchmarking and a qualitative vendor scorecard focused on technology breadth, certification readiness, geographic reach, and aftermarket service capability.
- Regulatory compliance matrix aligned to UL, NFPA, and CEN standards, with recommended test plans and timeline checklists to meet 2026 procurement windows.
- Go‑to‑market playbooks for winning large data‑center and industrial tenders, including sample contract clauses and installation service offerings.
- Risk heatmaps and mitigation playbooks for procurement, manufacturing, and product certification risks.
Note: the public executive summary highlights trends and recommended actions. Our full deliverable includes the detailed segmentations, vendor market shares, and the spreadsheet model that operational teams use to run “what‑if” scenarios. These core datasets are intentionally reserved to provide our clients with exclusive decision advantage.
Cable Management System Market
Competitive landscape — positioning and implications
The competitive field remains fragmented. Aggregate concentration metrics indicate a market where leading global electrical and infrastructure players co‑exist with specialized niche vendors and regional manufacturers. A modest top‑three concentration underscores opportunities for differentiated offerings rather than purely scale‑driven competition.
- Global systems integrators and electrical majors (e.g., Eaton, Schneider Electric, Legrand): These firms bring deep infrastructure portfolios and channel reach for commercial, industrial, and data‑center projects. Their advantage is integrated solutions and global service networks — making them preferred vendors on complex, multi‑site tenders.
- Data‑center and telecom specialists (e.g., Panduit, The Siemon Company): Strengths lie in high‑density management, labeling, and rack‑level ecosystems. Their speed to adopt data‑center innovations positions them well for hyperscaler and colocation business.
- Industrial and safety‑focused suppliers (e.g., Niedax, Roxtec, NORMA Group): These players capture demand where mechanical protection, environmental sealing, and fire resistance are table stakes — notably in heavy industry, offshore, and hazardous environments.
- Fast innovators and material specialists (e.g., Enduro Composites, local manufacturers): Composites and polymer specialists are disrupting niches where corrosion resistance and weight matter. Their commercial scale is smaller, but their technology can be embedded by larger OEMs via partnerships or acquisitions.
Recent vendor activity illustrates a market with steady product innovation and project‑level growth: product launches targeted at data‑center routing systems, large project deliveries of cable cleats to sizeable infrastructure projects, and ongoing standards updates that force product refresh cycles. These dynamics favor suppliers who combine product R&D with certification and project execution capabilities.
Risk factors and mitigation
- Material price volatility: 2025 saw significant swings in galvanized steel and PVC inputs. Mitigation: diversify material options, negotiate blended fixed/variable supply contracts, and prioritize higher‑margin engineered products.
- Standards acceleration: Revised UL and CEN documents raise compliance costs. Mitigation: proactive certification investments and early participation in standards working groups to shape test protocols.
- Fragmented purchase behavior: Many buyers still source on price alone. Mitigation: shift contracting to value metrics (downtime risk reduction, install time savings, maintainability) and embed services to lock long‑term relationships.
- Execution risk on large projects: Complex installations (hyperscale data centers, industrial retrofits) expose suppliers to schedule and liability risks. Mitigation: subcontract scaffolding and electrical installers through vetted partners and provide performance guarantees where feasible.
Closing perspective — what to do next in 2026
For boards and executive teams planning 2026 allocations, the decision is less about whether the cable management market grows (it does) and more about where you will capture value as it evolves. Will you compete on low‑cost commodity trays, or will you own the interface between cabling and critical infrastructure strategy — certified, serviceable, and integrated with thermal and safety ecosystems?
PW Consulting’s Cable Management System Market study equips leaders with the forecast model, regulatory roadmap, supplier intelligence, and executable playbooks to make that choice with confidence. If your team is preparing a 2026 investment case — whether for R&D, capacity expansion, M&A, or channel development — the detailed segmentation, vendor shares, and Excel scenario models in the full report are designed to be the backbone of that decision.
To access the full datasets, segmentation tables, and our downloadable modelling toolkit, visit the report page where PW Consulting maintains the confidential deliverables that corporate strategists and procurement leads use to finalize 2026 commitments.
For detailed analysis of this topic, please visit the official page: Cable Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com