

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Healthcare RCM Outsourcing Market: Why 11.4% CAGR and $78B Scale Signal Strategic Shifts
By pmarketresearch, 2026-09-21
Healthcare RCM Outsourcing Market: Strategic Trends and Commercial Opportunities 2026–2032
The global healthcare revenue cycle management (RCM) outsourcing market has reached a critical inflection point. Valued at approximately $36.7 billion in 2025, the market is projected to advance to $78.1 billion by 2032, reflecting a compound annual growth rate of 11.4 percent over the forecast period. This trajectory marks a significant acceleration from the historical expansion observed between 2020 and 2025, when the market grew from $21.4 billion to its current scale. The pace of change is no longer driven solely by gradual administrative outsourcing; it is being reshaped by structural cost pressures, regulatory complexity, and the rapid infusion of artificial intelligence into revenue cycle operations. For executives, investors, and healthcare operators, the question has shifted from whether to outsource RCM functions to how to architect partnerships that deliver measurable financial resilience and operational agility.
Understanding the current market landscape requires acknowledging both the scale of opportunity and the friction points that define today's operating environment. Providers across hospitals, clinics, and ambulatory surgery centers are navigating rising denial rates, persistent labor constraints, and evolving reimbursement frameworks. At the same time, payers and regulators are pushing for greater transparency, faster prior authorization decisions, and standardized interoperability. These forces are compressing margins and lengthening the path to clean claims, which in turn is driving a broader reevaluation of how revenue cycle work is staffed, automated, and managed. The market is large enough to absorb diverse service models, yet fragmented enough that strategic positioning matters more than ever. Organizations that treat outsourcing as a purely transactional cost-cutting exercise risk missing the deeper operational transformation that forward-looking partnerships now enable.
Three structural challenges define the current market and signal where strategic attention should be directed. First, denial volumes and rework costs continue to rise, undermining cash flow predictability for many provider organizations. Even as technology adoption increases, the complexity of payer rules, medical necessity reviews, and coding specificity means that manual intervention remains a significant cost driver. Second, labor availability and cost dynamics are reshaping the economics of in-house revenue cycle teams. Recruitment delays, wage inflation, and turnover create execution risk for providers trying to maintain full internal control over billing, coding, and patient access functions. Third, regulatory momentum around interoperability and prior authorization is changing the compliance bar. Providers must adapt to new data exchange expectations and administrative simplification mandates, which introduces both opportunity and implementation risk depending on the maturity of their existing systems and processes.
These challenges are not isolated; they interact. Higher denial rates increase the workload required to sustain revenue integrity. Staffing shortages make it harder to absorb that workload without bottlenecking cash flow. Regulatory changes add new procedural requirements at a moment when teams are already stretched. The practical implication is that the market is rewarding providers who can combine scale, technology, and specialized expertise rather than those who simply seek the lowest unit cost for administrative services. That shift is visible in the types of partnerships being announced and the capabilities providers are prioritizing.
Healthcare Regulatory Affairs Outsourcing Market
Key Drivers Behind Market Acceleration
Technology Innovation and the Rise of Agentic Automation
The most consequential driver in the RCM outsourcing market is the transition from basic automation to agentic, context-aware systems that can support denial prevention, prior authorization, coding, and accounts receivable optimization within a managed services environment. This is not merely a software upgrade cycle. It reflects a structural change in what outsourcing can deliver. Providers increasingly expect partners to bring not only labor but also intelligent workflows that reduce manual rework, shorten cycle times, and improve first-pass acceptance rates.
Recent industry activity underscores this shift. R1 RCM expanded its innovation focus through its R37 lab by partnering with Palantir Technologies to operationalize AI data innovation and agentic applications for revenue cycle transformation. In parallel, R1 RCM announced an agreement to acquire Phare Health, an AI platform focused on automating inpatient coding and pre-bill clinical documentation improvement, with the Phare Health team joining the R37 innovation lab. These moves illustrate how leading outsourcing providers are embedding technology development directly into their service models rather than treating automation as a bolt-on feature.
Ensemble Health Partners has taken a similar direction by launching an agentic AI platform developed in partnership with Cohere for RCM-native language model capabilities, supporting autonomous coding and frictionless revenue cycle operations. Waystar has advanced its cloud-based platform with Google Cloud to accelerate autonomous revenue cycle capabilities, including denial prevention and recovery. These developments matter because they show a market moving toward platforms that can handle complex judgment-based tasks with less human intervention, while still fitting within managed services contracts. The commercial value is clear: when AI-driven workflows reduce denial leakage and rework, the economics of outsourcing become more attractive relative to the cost of maintaining fragmented internal operations.
Regulatory and Reimbursement Pressure as a Demand Catalyst
Policy and reimbursement dynamics are reinforcing demand for outsourced RCM support. Regulatory attention on interoperability and prior authorization has raised the compliance and administrative burden for providers, particularly those managing Medicare Advantage and managed care relationships. R1 RCM, for example, has submitted comments to the Centers for Medicare & Medicaid Services on proposed rules related to advancing interoperability and improving prior authorization processes. These regulatory conversations are not abstract; they influence how quickly claims move, how much documentation is required, and how much administrative effort is needed to secure timely payment.
On the reimbursement side, uncertainty around payment rules and evolving prior authorization expectations has increased the operational complexity of revenue cycle management. Providers must be able to track changing requirements, adapt workflows, and minimize avoidable denials without expanding internal headcount indefinitely. For many organizations, that combination is a practical argument for outsourcing models that can spread regulatory adaptation costs across a broader client base and apply specialized expertise to payer-specific rules. The market response has been consistent: a meaningful share of providers are actively exploring outsourcing options for RCM tasks, including remittance advice standards and other administrative functions, while others have already moved portions of their revenue cycle work externally.
Cost Structure Pressures and Staffing Realities
Cost structure and labor dynamics remain central to the outsourcing thesis. More than 60 percent of providers are considering outsourcing RCM to address staffing shortages, inflation, and rising denials, according to recent sector analysis. That figure reflects a practical response to a difficult operating environment rather than a philosophical preference for outsourcing. When labor markets are tight and wage pressure is persistent, the fully loaded cost of an internal revenue cycle team rises faster than many providers can offset through productivity gains alone.
PW Consulting Health Care Research Center
Outsourcing offers a different cost profile. It can convert fixed labor expense into variable or service-based pricing, align capacity with volume fluctuations, and provide access to specialized skills that are expensive to recruit and retain in-house. More importantly, outsourcing partners with strong technology backbones can improve throughput and reduce error rates in ways that are difficult to replicate with staff alone. The most attractive engagements today are those that combine cost discipline with measurable performance outcomes, such as lower days in accounts receivable, improved clean claim rates, and reduced denial write-offs.
Provider Demand for End-to-End Managed Services
Demand-side behavior is shifting toward broader, more integrated outsourcing relationships. Rather than outsourcing isolated functions, providers are increasingly looking for end-to-end managed services that span patient access, patient encounter processing, and patient billing within a unified operating model. This preference is driven by the desire to reduce handoff friction, standardize data flow, and improve accountability across the revenue cycle. When responsibilities are split across multiple vendors or internal departments, coordination costs and blind spots can erode the benefits of any single technology or process improvement.
This trend is reinforced by the growing complexity of patient financial interactions. As patients take on more cost-sharing responsibility and access models expand across virtual care, outpatient settings, and ambulatory surgery centers, providers need revenue cycle processes that can handle varied billing scenarios without sacrificing patient experience. Managed services models that integrate access, encounter, and billing functions can help organizations maintain consistency while scaling across multiple facilities or care settings. The result is a market that increasingly values integration, accountability, and performance visibility as much as raw processing capacity.
Competitive Landscape and Leading Strategies
The RCM outsourcing market is characterized by a mix of specialized managed services providers, technology-forward platforms, and large integrated players with payer connectivity and analytics capabilities. Market concentration remains moderate, with the top three firms accounting for roughly 29.5 percent of market revenue and the top five collectively representing about 36.2 percent. That structure leaves substantial room for differentiated positioning, regional strength, and vertical specialization, while also rewarding providers that can combine scale with credible technology and service integration.
R1 RCM has built a distinctive position around full-service managed revenue cycle outsourcing supported by AI-driven automation. Its R37 lab and Phare platform point toward inpatient coding and denial management as areas where technology can be tightly integrated into outsourcing delivery. The recent acquisition of Phare Health and the partnership with Palantir Technologies suggest a strategy focused on building proprietary innovation capacity while expanding agentic capabilities. This approach positions R1 RCM as a provider that wants to control more of the technology roadmap underlying its services, rather than relying entirely on third-party tools.
Conifer Health Solutions has emphasized multi-year enterprise revenue cycle outsourcing partnerships that deliver tech-enabled patient access, denial management, and accounts receivable optimization for hospitals and health systems. Its recent multi-year enterprise partnership with Healthcare Systems of America for multi-facility services reflects a strategy aimed at scaling long-term relationships across complex provider networks. The commercial logic is straightforward: enterprise engagements create deeper integration, more stable revenue streams, and opportunities to apply standardized processes across multiple facilities.
Ensemble Health Partners has focused on end-to-end managed services outsourcing with an agentic AI platform developed in partnership with Cohere. Its RCM-native language model emphasis and autonomous coding ambitions place it in a group of providers seeking to differentiate through automation that is purpose-built for revenue cycle work. This is a meaningful strategic signal because it suggests a shift from generic AI adoption to domain-specific models that can better handle coding logic, documentation review, and denial-related decision-making.
Waystar continues to advance its cloud-based software platform for end-to-end RCM outsourcing and managed services, with AltitudeAI agentic automation targeting denials, prior authorization, and recoupment. Its partnership with Google Cloud highlights a technology-centric pathway to autonomous revenue cycle capabilities. Waystar's positioning is relevant for providers looking for a platform-based model that can be paired with managed services, particularly when cloud scalability and AI-driven denial prevention are priorities.
GeBBS Healthcare Solutions offers AI-enabled revenue cycle outsourcing and managed services across billing, coding, patient access, and financial operations. Its breadth across core revenue cycle functions makes it a generalist-oriented player that competes on integration and service coverage. Optum, including its Change Healthcare assets, brings integrated revenue cycle management outsourcing and BPO solutions with payer connectivity, analytics, and technology. Its scale and cross-market presence give it a different kind of advantage: the ability to align provider-facing outsourcing with broader payer and health system relationships.
Other notable participants include TruBridge, which focuses on end-to-end revenue cycle management outsourcing and managed services with technology and staffing for community hospitals, rural facilities, and federally qualified health centers; Athenahealth, with an integrated EHR and revenue cycle management platform supporting physician practices and health systems; Nthrive, with managed revenue cycle services emphasizing outpatient and provider operations; The SSI Group, which provides revenue cycle outsourcing and managed services for hospitals and health systems; and MedAssets, part of Vizient, which delivers integrated revenue cycle management outsourcing and solutions through health system partnerships.
Healthcare BPO Market
The strategic common thread across these players is a move toward deeper service integration and stronger technology differentiation. Some providers are competing on scale, enterprise relationships, and payer connectivity. Others are competing on niche focus, such as rural and community hospital needs, outpatient operations, or inpatient coding and documentation. A third group is competing on AI-native workflows and agentic automation. This diversification is healthy for the market because it gives providers multiple entry points depending on their size, complexity, and technology maturity. It also suggests that the next phase of competition will be less about who offers outsourcing and more about who can demonstrate superior outcomes through a credible mix of staffing, automation, analytics, and integration.
Market evolution is likely to continue along two parallel paths. On one hand, consolidation may increase as larger players acquire niche capabilities, especially in AI, coding automation, and denial management. On the other hand, differentiation will persist because provider needs vary widely across academic medical centers, community hospitals, ambulatory surgery centers, and physician practices. New entrants with strong AI platforms or specialized managed services models can still carve out positions if they can prove measurable improvements in revenue integrity and operational efficiency. The most resilient providers will be those that can adapt their service architecture to different provider segments without losing focus on core performance metrics.
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to shape the market's next chapter. The first is the mainstreaming of agentic AI within managed revenue cycle services. As RCM-native models and automation workflows mature, providers will increasingly expect partners to prevent denials before submission, accelerate prior authorization decisions, and reduce rework in coding and billing. The commercial opportunity here lies in services that can tie automation directly to financial outcomes, not just process speed. Providers that can demonstrate lower denial rates, faster reimbursement, and reduced manual touchpoints will have stronger positioning in competitive evaluations.
The second trend is the continued shift toward integrated, end-to-end outsourcing models that span patient access, encounter, and billing functions. Fragmented service arrangements will face growing pressure as providers seek to reduce coordination complexity and improve data continuity. This creates opportunities for partners that can operate across the full revenue cycle while maintaining segment-specific expertise. It also creates opportunities for technology platforms that can unify data, reporting, and workflow across outsourced and internally managed functions where hybrid models remain necessary.
The third trend is the growing influence of regulatory and reimbursement reform on outsourcing demand. As prior authorization processes, interoperability expectations, and remittance standards evolve, providers will need partners that can adapt quickly and help manage compliance risk. The commercial opportunity is not simply in handling more transactions, but in helping providers navigate administrative change with less disruption to cash flow and patient experience. Organizations that can combine regulatory awareness with operational execution will be better placed to win long-term engagements.
These trends carry opportunity, but they also introduce risk. AI-driven automation can improve efficiency, yet it also raises questions about model accuracy, governance, and change management. If automation is deployed without strong oversight, providers may face new categories of coding or denial-related errors that offset expected gains. Regulatory changes can also shift the value of certain services over time, especially if prior authorization burdens are reduced or if payment models change in ways that alter revenue cycle complexity. Finally, the market's growth trajectory depends on providers' willingness and ability to restructure internal operations. Outsourcing adoption may be strong in principle, but execution risk remains where leadership, data readiness, and integration capacity are limited.
Strategic Considerations for Decision-Makers
For healthcare providers evaluating RCM outsourcing, the most important discipline is to define success in operational and financial terms before selecting a partner. engagements should be assessed against clear targets such as denial reduction, days in accounts receivable, clean claim performance, and patient access efficiency, rather than treated as generic cost-reduction projects. Providers should also determine which functions truly benefit from outsourcing versus which require retained internal control for clinical, strategic, or compliance reasons. A hybrid model can work well when the boundary between outsourced and internal responsibilities is deliberately designed and supported by shared data and reporting standards.
For investors and strategic observers, the market's growth trajectory is appealing, but the differentiation story is increasingly found in technology integration, enterprise relationship quality, and segment specialization. The most durable opportunities are likely to belong to providers that can demonstrate repeatable outcomes across multiple client environments and that can adapt their models as AI, regulation, and reimbursement structures evolve. Monitoring partnership announcements, platform launches, and acquisition activity can provide early signals about where capability is concentrating and where competitive advantage is being built.
For technology and service vendors participating in the broader revenue cycle ecosystem, the opportunity lies in aligning products and services with the way providers now evaluate outsourcing: as a combined package of staffing, automation, analytics, and accountability. Solutions that reduce handoff friction, improve denial visibility, and support payer-specific workflows are more likely to fit into enterprise engagements than point tools that address only one step in the cycle. In practice, vendors that can speak to both operational efficiency and revenue integrity will have an easier path into provider decision-making discussions.
The broader takeaway is that healthcare RCM outsourcing is no longer a back-office cost discussion. It is becoming a strategic lever for revenue predictability, administrative resilience, and technology-driven operational performance. Providers that treat it accordingly will be better positioned to manage denials, staffing constraints, and regulatory change without sacrificing financial control. Those that continue to view outsourcing narrowly may leave measurable value on the table as the market shifts toward more intelligent, integrated, and outcome-focused service models.
For decision-makers seeking a deeper breakdown of segment-level dynamics, regional nuances, and company-specific positioning, the full research report provides a more detailed look at the market structure, growth path, and strategic implications across the forecast period.
For detailed analysis of this topic, please visit the official page: Healthcare RCM Outsourcing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vehicle Routing and Scheduling Market: How 4.03% CAGR Planning Redefines Logistics Strategy
By pmarketresearch, 2026-09-21
Vehicle Routing and Scheduling Market: Strategic Trends and Commercial Opportunities in the Age of Intelligent Logistics
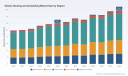
The global vehicle routing and scheduling market has entered a phase of structural transformation where route planning is no longer a back-office optimization problem but a core operational driver of margin protection, service reliability, and carbon accountability. Valued at approximately USD 12.01 billion in 2025, the market is projected to reach USD 15.83 billion by 2032, expanding at a compound annual growth rate of roughly 4.03% over the 2026–2032 forecast window. This trajectory reflects a market that is maturing in terms of software adoption, yet simultaneously becoming more complex as operational, regulatory, and technological pressures converge. For executives, investors, and procurement leaders, the strategic implication is clear: routing and scheduling capabilities are increasingly intertwined with broader freight visibility, workforce management, and sustainability commitments. The companies and fleets that treat route intelligence as a standalone tool will find diminishing returns; those that embed it into real-time operational workflows will gain measurable advantages in cost per mile, asset utilization, and service consistency.
The market expansion is not uniform across time or activity. Growth has been shaped by a combination of post-pandemic logistics normalization, rising last-mile complexity, and the gradual shift from static planning models toward more adaptive, data-driven scheduling. Historical demand between 2020 and 2025 illustrates this arc: modest recovery in the early years gave way to stronger operational investment as organizations attempted to absorb volatility in labor availability, freight volumes, and customer expectations. The forecast period onward suggests continued expansion, though not without intermittent adjustments as enterprises recalibrate spending, vendors refine product-market fit, and buyers weigh the total cost of ownership against promised efficiency gains. In this context, the market is best understood as a space where incremental efficiency improvements can compound into meaningful competitive differentiation, especially for operators managing large fleets, multi-stop delivery networks, or time-sensitive service schedules.
Market Landscape and Core Challenges
Where the Market Stands Today
Today’s vehicle routing and scheduling market is defined by a broad shift from fixed, pre-planned routes to systems that can respond to changing conditions throughout the day. Enterprises are no longer satisfied with tools that optimize once at the start of a shift; they increasingly expect platforms that can incorporate live traffic patterns, service-window constraints, driver availability, and real-time exceptions. That expectation is pushing vendors to integrate routing logic more tightly with telematics, transportation management, and field service workflows, rather than offering routing as an isolated module.
At the same time, the market remains meaningfully concentrated. A relatively small group of established providers accounts for a substantial share of enterprise adoption, while a wider field of specialist and emerging players competes on usability, vertical-specific features, or deployment speed. This split matters because it shapes how quickly innovation reaches different buyer segments. Large platforms tend to emphasize integration depth, security, and enterprise governance, while smaller or more focused vendors often move faster on user experience, specialized optimization logic, or rapid onboarding for particular use cases. The result is a market where the value proposition increasingly depends on context: the right solution for a global freight operation may differ substantially from the right solution for a regional field-service organization or a high-density urban delivery network.
Key Challenges and Decision Points
Several intersecting challenges are shaping the market’s near-term direction.
-
Operational variability versus planning stability. Route optimization becomes harder as conditions grow less predictable. Traffic disruptions, weather events, shifting delivery windows, and vehicle availability issues all create exceptions that can quickly erode the value of a theoretically optimal plan. The challenge for buyers is not simply to buy an optimizer, but to choose systems that can re-plan quickly without destabilizing the day’s operations or overwhelming dispatchers with constant changes.
PW Consulting -
Regulatory and compliance complexity. Route scheduling does not operate in a vacuum. Driving-hour restrictions, emission-sensitive zones, load limits, toll structures, and vehicle-type restrictions differ across regions and can materially affect feasible routing choices. As regulatory expectations tighten in various markets, route planning tools must account for compliance constraints while still supporting efficiency goals. This creates a tension that many operators are still learning to manage: optimizing for cost or speed in a way that does not inadvertently create compliance exposure or operational friction.
-
Labor cost pressures and workforce constraints. Labor remains one of the largest cost categories for fleet operators when routes are planned manually or managed through fragmented tools. At the same time, driver availability and retention have become strategic concerns in many markets. This combination is pushing organizations to seek routing and scheduling systems that can reduce unnecessary miles, balance workload more effectively, and support Hours of Service and driver-availability considerations. The operational prize is twofold: lower direct cost and a more sustainable workflow for drivers, which can matter just as much in a tight labor environment.
-
Data security, privacy, and system trustworthiness. Routing platforms increasingly touch sensitive operational, customer, and location data. As a result, security and privacy concerns have become a more visible part of the buying decision. Enterprises are paying closer attention to breach risk, governance, and regulatory compliance, particularly where routing data is integrated with broader logistics or customer-facing systems. Trust and reliability are no longer secondary considerations; they are part of the platform’s commercial viability.
Key Demand Drivers Shaping the Market
Technology Innovation and Optimization Maturity
A central driver of market growth is the continued maturation of optimization technology itself. Route planning has evolved from relatively static, rules-based approaches toward systems that can absorb more variables, adapt more quickly, and support more granular operational decisions. Dynamic re-optimization, in particular, has moved from a differentiating feature to an expectation in many use cases. When a dispatcher can adjust routes in response to a delayed vehicle, a new order, or a service-window change without rebuilding the entire day’s plan, the operational value is considerable.
The practical impact of this shift is visible in how vendors are packaging routing capabilities. Some are embedding route optimization inside broader logistics and transportation platforms, making it part of a continuous operational flow rather than a separate planning step. Others are pairing optimization engines with telematics and field-data capture so that scheduled plans can be compared against actual execution, creating feedback loops that improve future planning. This convergence is important because it moves routing from a static efficiency exercise toward a more measurable, iterative capability.
Policy, Regulation, and Compliance Pressure
Policy and regulatory environments are influencing both the demand for routing software and the functionality that buyers require. Driving-hour rules, regional load and vehicle restrictions, emission zones, and toll regimes can all affect which routes are viable and how schedules should be structured. In markets where these constraints are especially varied or evolving, routing tools that can encode compliance logic directly into scheduling decisions have a stronger value proposition. This is not only about avoiding penalties; it is also about reducing the operational burden of managing complex rule sets manually.
For multinational operators and cross-border logistics providers, the regulatory dimension adds another layer of importance. Different jurisdictions can impose different constraints on heavy vehicles, urban access, driver working time, and environmental performance. In such environments, routing and scheduling software becomes a mechanism for standardizing operational decision-making across regions while still respecting local constraints. That capability is increasingly relevant as supply chains and service networks become more geographically diversified.
Demand-Side Changes in Customer and Enterprise Behavior
Demand-side behavior is also reshaping the market. Customers across both consumer and business segments increasingly expect more accurate delivery or service-time predictions, faster response to exceptions, and greater transparency in logistics operations. Those expectations raise the stakes for routing and scheduling because they connect operational planning directly to customer experience. A plan that is mathematically efficient but fragile in execution may not satisfy service expectations once real-world disruptions occur.
In parallel, many enterprises are under pressure to improve not just service levels but also asset productivity and environmental performance. Route optimization supports both objectives by reducing empty miles, tightening stop sequencing, and helping organizations make better use of existing vehicles and drivers. In that sense, routing and scheduling is becoming part of a broader operational narrative around doing more with constrained assets while improving consistency and reliability.
Supply Chain and Cost Structure Pressures
Cost structure dynamics continue to influence adoption. When labor, fuel, maintenance, and compliance costs rise or become more volatile, the value of better routing becomes more visible. Even modest reductions in unnecessary miles or unproductive downtime can translate into meaningful operational savings across a large fleet or high-frequency delivery operation. This is why routing optimization is often evaluated not as a discretionary software purchase but as a lever for protecting margins in an environment where many cost inputs are difficult to control.
The same pressure is encouraging integration with broader cost and performance management. Organizations are increasingly interested in solutions that can link route decisions with fuel consumption, driver scheduling, vehicle maintenance windows, and service-level outcomes. The more routing is connected to these surrounding processes, the more it can contribute to total operating efficiency rather than isolated route improvements.
Competitive Landscape and Leading Strategies
How the Market Is Structured
The competitive landscape reflects a mix of large enterprise platforms, specialized optimization vendors, telematics-rich fleet solutions, and regional or vertically oriented providers. This diversity is one of the market’s defining features. Large platforms typically compete on breadth: integration with broader ERP, transportation, or supply chain systems, enterprise governance, security posture, and the ability to support complex global operations. Specialist and mid-tier vendors often compete on speed, usability, targeted optimization logic, and the clarity of their solution for a specific operational context.
Several organizations stand out for the way they position routing and scheduling within their broader portfolios. Descartes Systems Group emphasizes routing and dispatch capabilities oriented around logistics and distribution workflows. Oracle and SAP embed vehicle routing and scheduling within broader transportation management and fleet scheduling environments, appealing to enterprises that want routing to operate as part of a unified operational backbone. IBM supports routing and scheduling through supply chain and logistics platforms, targeting organizations that value integrated intelligence across planning and execution. Manhattan Associates has expanded route optimization within its broader logistics software ecosystem, reflecting a strategy of connecting routing more tightly to warehouse, order, and delivery execution.
There is also a notable presence of telematics-oriented and fleet-focused providers. Samsara, Verizon Connect, Fleet Complete, and Geotab integrate route optimization with telematics and fleet-management capabilities, which can be especially compelling for operators that want scheduling decisions linked to vehicle location, driver behavior, and real-time operational data. Locus highlights multi-fleet planning and real-time dynamic re-optimization for enterprise use cases, while Routific, Route4Me, and OptimoRoute are commonly associated with delivery-oriented route planning and optimization. e2open and Trimble round out the landscape with solutions that connect routing and scheduling to broader transportation, last-mile, and logistics workflows.
Differentiation and Strategic Positioning
The market’s competitive dynamics are increasingly shaped by differentiation in a few key areas.
-
Integration depth. Providers that connect routing to other operational systems have an advantage in environments where plans must flow directly into execution. Integration with transportation management, telematics, order management, or field-service platforms reduces the friction between planning and doing, which is often where the greatest operational value is realized.
-
Real-time adaptability. The ability to re-optimize quickly, without disrupting the entire schedule, is becoming a critical differentiator. Vendors that can handle live exceptions, reorder stops, and rebalance routes as conditions change are better positioned for complex, high-variability operations.
-
Vertical and use-case fit. Routing and scheduling needs differ substantially by application. Public transportation, freight and logistics, field service management, emergency services, and healthcare transportation all impose different constraints and priorities. Providers that tune their optimization logic, user experience, and integrations to specific use cases can stand out even in a crowded market.
Carpooling Market -
Compliance and operational governance. Solutions that make it easier to manage driving-hour rules, regional restrictions, and other compliance considerations are gaining relevance, particularly where regulatory variation is high. This is not just a legal matter; it is an operational design issue that affects how workable a schedule is in practice.
-
Deployment and usability. In many buyer segments, implementation speed and dispatcher usability matter as much as algorithmic sophistication. Tools that are easier to adopt and train can deliver value sooner, which is especially important for organizations that need to improve operations quickly without large transformation programs.
How the Landscape Is Evolving
The market is evolving along multiple axes at once. One trend is convergence, as routing capabilities become more embedded in larger logistics, telematics, and transportation platforms. This makes sense operationally, because route planning is most powerful when it is connected to real-time execution data and broader business processes. Another trend is fragmentation at the specialist level, where smaller or more focused providers continue to emerge around specific delivery models, regional markets, or vertical needs. Finally, there is ongoing consolidation pressure among enterprise buyers, who increasingly prefer fewer, better-integrated systems over a patchwork of point solutions.
Together, these dynamics suggest that competition will not be decided by optimization quality alone. The winners in different segments will likely be those that combine sound routing logic with strong integration, practical usability, compliance awareness, and credible security and data governance. In market terms, that means some providers will grow by extending into broader operational platforms, while others will compete by dominating a specific use case or deployment profile with exceptional fit and speed.
Future Outlook: Strategic Trends for the Next 3–5 Years
Trend 1: Routing as a Real-Time Operational Capability
Over the next several years, routing and scheduling is likely to become less about planning a day in advance and more about continuously managing a living operation. Dynamic re-optimization, exception handling, and live feedback from telematics and execution systems will increasingly define the value of a platform. For commercial operators, this means routing will matter not only at the start of a shift, but throughout the day as conditions change. The opportunity is to reduce operational drag: fewer cascading delays, better recovery from disruptions, and higher percentages of stops or services completed within intended windows.
The associated risk is that real-time capabilities can create complexity if they are not designed well. Constant replanning can overwhelm dispatchers and drivers if the system lacks clear priorities, thresholds, and human-in-the-loop controls. The most successful deployments will likely be those that balance automation with operational governance, so that optimization improves stability rather than creating noise.
Trend 2: Compliance-Aware, Sustainability-Linked Scheduling
Regulatory and sustainability pressures are expected to keep rising as planning constraints. Emissions considerations, urban access rules, driving-hour compliance, and vehicle restrictions will not remain niche concerns; they will become embedded in how feasible routes are defined and evaluated. This creates an opportunity for routing and scheduling tools to serve as a dual-purpose asset: improving efficiency while also supporting compliance and environmental objectives. In many operations, that combination is becoming more valuable than pure cost minimization.
At the same time, there is uncertainty in how regulations will evolve across regions and how consistently organizations can operationalize sustainability goals alongside service and cost targets. Market participants should expect continued variation in the pace and shape of requirements, which will favor flexible platforms over rigid ones.
Trend 3: Smarter Integration With Workforce, Telematics, and Execution Data
A third major trend is the deepening connection between routing and the systems that surround it. Telematics, driver scheduling, order or service data, and execution analytics will be more tightly linked to route decisions. This matters because routing outcomes are only as useful as the operational feedback loop that follows. When planned routes are compared with actual performance, organizations can refine constraints, identify recurring exceptions, and improve future schedules. Over time, this turns routing into a continuously improving capability rather than a one-time optimization exercise.
The opportunity here extends beyond technology. Organizations that invest in data quality, operational discipline, and clear performance metrics will benefit more from advanced routing than those that simply install a better optimizer. The technology amplifies operational intent; it does not replace it.
Strategic Implications for Decision Makers
For Fleet Operators and Logistics Providers
Operators should evaluate routing and scheduling as part of a broader operational architecture rather than as a standalone efficiency tool. The highest returns typically come when route optimization is connected to real-time execution data, dispatcher workflows, and compliance requirements. A practical approach is to prioritize solutions that can handle dynamic exceptions, support driver and vehicle constraints, and integrate with existing telematics or transportation systems without creating new data silos.
Ride Sharing Market
Equally important is realistic scoping. Different operations need different levels of sophistication. A high-density urban delivery network may benefit most from frequent re-optimization and tight time-window control, while a field-service organization may need stronger scheduling integration around technician availability and service priorities. Matching the tool to the operational model is often more important than selecting the most feature-rich platform.
For Technology and Software Investors
Investors should look for differentiation that is defensible in practice, not just in product descriptions. The most durable opportunities tend to sit where routing is tightly integrated with surrounding workflows, where compliance and security requirements create meaningful barriers, and where execution feedback improves outcomes over time. Niche fit can be valuable, but scaling often depends on the ability to connect routing to broader platforms or to serve a clearly defined vertical with strong adoption economics.
It is also worth monitoring consolidation patterns. As enterprises favor fewer, more integrated systems, providers that can either expand into adjacent operational capabilities or maintain a strong specialist position with clear customer value will be better placed than those competing primarily on commoditized planning features.
For Procurement and Enterprise Buyers
Procurement teams should evaluate total operating impact rather than software features in isolation. That means assessing how a solution affects dispatcher workload, driver experience, exception handling, compliance management, and integration with existing systems. Security, data governance, and implementation effort should be treated as core commercial criteria, not secondary checkboxes. Where possible, pilot programs should test not just plan quality but operational resilience under realistic disruption scenarios.
A useful lens is to ask whether the platform can make the operation more stable, not simply more optimized on paper. Stability under pressure, clarity of workflow, and measurable integration with execution often matter more in day-to-day operations than marginal gains in theoretical route efficiency.
Conclusion
The vehicle routing and scheduling market is moving from incremental tooling improvement toward a more central role in operational performance. Growth to roughly USD 15.83 billion by 2032, at a CAGR of about 4.03%, reflects a market where efficiency, compliance, customer expectations, and data integration are converging. The strategic question for organizations is no longer whether routing matters, but how routing is embedded into real-time operations, regulatory response, and workforce management. Those that treat it as a connected operational capability will be better positioned to control cost, protect service levels, and adapt as conditions change. For decision makers seeking a more detailed view of segment dynamics, regional variation, and vendor-specific positioning, a fuller market study can provide the depth needed to translate these trends into targeted investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: Vehicle Routing and Scheduling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Corn Starch Market: Beyond 8.1% CAGR, What's Driving $41.4B Growth by 2032
By pmarketresearch, 2026-09-21
The Corn Starch Market: Strategic Trends and Commercial Opportunities Through 2032
The global corn starch market has entered a phase of accelerated expansion, driven by converging forces across food innovation, pharmaceutical formulation, and industrial substitution. With total market revenue reaching USD 24.0 billion in 2025 and a projected compound annual growth rate of 8.1 percent through 2032, the sector is evolving from a commoditized feedstock into a specialized functional ingredient landscape. This shift demands that executives, planners, and investors recalibrate their strategic assumptions. The following analysis maps the market's structural dynamics, identifies the forces reshaping competitive positioning, and outlines actionable implications for decision-makers.
Market Landscape and Structural Challenges
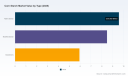
Historical trajectory underscores the market's momentum. Revenue climbed from USD 12.0 billion in 2020 to USD 15.49 billion in 2023, then accelerated sharply to USD 20.08 billion in 2024 and USD 24.0 billion in 2025. Forecasts project continued growth to USD 25.31 billion in 2026, USD 28.53 billion in 2027, and a terminal value of USD 41.4 billion by 2032. This trajectory reflects both volume expansion and value migration toward higher-margin specialty grades. The market remains moderately concentrated, with the top three players capturing 45.2 percent of revenue and the top five holding 58.6 percent, indicating room for regional challengers and niche specialists to compete on formulation expertise, certification portfolios, and supply reliability.
Despite the favorable macro trajectory, the industry faces several structural inflection points that will separate resilient operators from those caught off-guard.
- Feedstock volatility and margin asymmetry. Corn starch economics are tightly coupled to agricultural commodity cycles. While recent U.S. corn futures for the July 2026 contract traded between USD 4.11 and USD 4.73 per bushel in early 2026, below the 2022 peaks and hovering near the 2015-2019 average of USD 3.50 per bushel, the structural risk remains. Feedstock cost advantages can compress quickly, forcing producers to rely on operational efficiency, long-term supply agreements, and formulation differentiation rather than raw material arbitrage alone.
- Regulatory divergence across pharmaceuticals and foods. The excipient and functional ingredient landscape is being reshaped by region-specific mandates. In India, draft guidance from the Central Drugs Standard Control Organisation issued in March 2025 requires domestic tablet manufacturers to source at least 30 percent of excipients from plant-based or mineral origins by 2028, favoring suppliers with ISO 9001 and Good Manufacturing Practice certifications. In China, the National Medical Products Administration mandated in August 2025 that new generic applications justify the use of synthetic excipients over natural alternatives, accelerating the transition to pregelatinized corn starch in Asian pharmaceutical manufacturing. These divergent requirements elevate compliance complexity and reward suppliers with robust quality systems and regional regulatory fluency.
- Substitution pressure and functional performance thresholds. End-use industries are increasingly demanding ingredients that deliver specific rheological, textural, or health-related properties without compromising cost or label cleanliness. The European Commission's Farm to Fork Strategy update in May 2025 targets a 15 percent reduction in average per-capita saturated-fat intake by 2030, driving substitution of butter or cream with enzymatically modified waxy corn starch. Meeting these performance benchmarks requires continuous R&D investment and close co-development with downstream customers, raising the barrier for commoditized entrants.
Core Demand Drivers Reshaping the Market
The market's growth is not a single-factor story. It emerges from the intersection of technical capability, policy direction, consumer and industrial behavior, and shifting cost structures. Understanding how these forces interact clarifies where value will accumulate over the next several years.
Technological Innovation and Formulation Breakthroughs
The most consequential advances are occurring in modification science and application-specific engineering. Enzymatic modification, pregelatinization, and resistant starch development are expanding the functional envelope of corn starch beyond traditional thickening and binding roles. In pharmaceuticals, pregelatinized grades are improving tablet compression characteristics and disintegration profiles, directly supporting generic manufacturing efficiency. In food and beverage, enzymatically modified waxy corn starch is enabling fat reduction while preserving mouthfeel, aligning with clean-label and health-forward product pipelines. These capabilities are not incremental; they redefine the ingredient's role from a bulk commodity to a performance enabler, which in turn supports premium pricing and longer-term customer lock-in.
Policy and Regulatory Tailwinds
Regulation is acting as both a filter and an accelerant. The U.S. Department of Agriculture's BioPreferred Program, reauthorized in the 2024 Farm Bill with a 40 percent budget increase, requires federal agencies to prioritize products containing at least 25 percent bio-based carbon. Since 100 percent plant-derived corn starch qualifies automatically, this policy creates a structural procurement advantage for bio-based formulations in government-adjacent and institutional supply chains. Meanwhile, pharmaceutical regulatory shifts in India and China are pulling demand toward plant-based excipients with verifiable quality certifications. The net effect is a policy environment that rewards certified, traceable, and bio-based corn starch offerings while penalizing opaque or synthetic-heavy supply chains.
Demand-Side Shifts in Consumer and Industrial Behavior
Downstream demand is being reshaped by three interrelated trends. First, food and beverage formulators are prioritizing texture modification, fat replacement, and clean-label positioning, which elevates the role of modified and specialty starches. Second, pharmaceutical manufacturers are optimizing excipient selection to meet regional mandates and improve process reliability, particularly in generic drug production where cost and compliance are tightly coupled. Third, industrial applications such as paper, corrugated, and technical coatings continue to rely on starch-based solutions for binding, sizing, and surface strength, but with growing expectations for consistency and supply security. These demand signals favor suppliers that can pair technical service with robust logistics and certification documentation.
Supply Chain and Cost Structure Dynamics
Cost structures are improving in the near term, but the long-term advantage will belong to operators who build resilience. The recent moderation in U.S. corn futures has lowered feedstock costs for corn starch production, providing margin relief and enabling reinvestment in capacity and quality systems. Yet the more strategic opportunity lies in supply chain design. Regional capacity expansions are reducing logistics friction and improving service levels for local markets. Certifications and quality management systems are becoming differentiators in regulated segments. Producers that integrate feedstock procurement, modification capability, and application support into a coherent value proposition will capture more of the margin pool than those competing solely on volume.
Potato Starch Market
Competitive Landscape and Strategic Positioning
The corn starch market is shaped by a mix of global agribusiness integrators, specialty starch specialists, and regional capacity builders. Their strategies reveal how value is being captured and where gaps remain for new entrants or focused challengers.
Large, diversified players are leveraging scale, integrated supply chains, and broad application portfolios to anchor their positions. Their advantage lies in the ability to serve multiple downstream industries simultaneously, smoothing cyclicality and cross-selling functional ingredients across food, beverage, industrial, and pharmaceutical channels. These firms are increasingly emphasizing modification technology and certification readiness to compete in higher-value segments rather than relying on commodity throughput alone.
PW Consulting
Specialty and regional operators are differentiating through formulation depth, pharma-grade quality systems, and localized service. Companies with strong positions in modified starches, resistant starches, and pharmaceutical excipients are capturing demand from tablet manufacturers, infant formula producers, and dairy formulators seeking reliable, certified inputs. Their strategic edge often comes from technical collaboration, rapid customization, and the ability to meet region-specific regulatory requirements without the overhead of a fully integrated global network.
Capacity expansion is a visible signal of where demand is heading. In October 2025, Al Ghurair Foods announced the phased completion of the UAE's first corn starch plant in the Khalifa Economic Zones Abu Dhabi, targeting processing capacity of up to 1,000 tons per day for food, pharmaceutical, paper, and chemical industries, with completion expected by the first quarter of 2026. This move reflects a broader pattern of regional supply 구축 to reduce logistics dependency and serve Middle East and Africa demand with shorter lead times and localized certification support. In May 2025, Cargill inaugurated a new corn milling plant in Gwalior, India, operated through Saatvik Agro Processors, to support increasing demand from confectionery, infant formula, and dairy sectors. The expansion underscores the strategic importance of India as a growth node for food-grade and specialty starches. In August 2025, Ingredion expanded its Cardinal plant in Ontario, Canada with a CAD 28 million investment to meet domestic and export demand for tablet manufacturers and specialty starches, highlighting the continued relevance of North American capacity for pharmaceutical and technical grades.
The competitive landscape is evolving along two axes. On one hand, consolidation pressure persists among the largest players as they seek to widen application coverage and secure feedstock and logistics advantages. On the other hand, differentiation is intensifying in specialty segments where certification, modification expertise, and regional compliance matter more than sheer scale. New entrants and regional challengers can succeed by targeting underserved application-grade combinations, building strong quality and regulatory profiles, and forming strategic partnerships with downstream formulators. The market is therefore not converging into a pure commodity oligopoly; it is fragmenting into performance tiers where technical service, certification, and supply reliability command measurable premiums.
Forward-Looking Trends and Commercial Implications
Looking ahead to the mid-2020s and toward 2032, several trends are likely to define the market's trajectory and create distinct commercial opportunities.
Bio-based procurement standards will become a structural advantage
As public procurement and institutional supply chains increasingly prioritize bio-based content, 100 percent plant-derived corn starch is well positioned to benefit from automatic qualification under programs like the USDA BioPreferred reauthorization. This trend favors suppliers that can document bio-based content, maintain consistent quality, and serve government-adjacent and institutional customers with reliable logistics. Commercial opportunity lies in aligning product portfolios with bio-based procurement criteria and building the certification and traceability infrastructure to capture these contracts early.
Pharmaceutical excipient substitution will accelerate in Asia and beyond
Regulatory guidance in India and China is nudging generic manufacturers toward plant-based excipients, with pregelatinized corn starch emerging as a preferred option for tablet compression and disintegration. As these mandates take effect, demand for pharma-grade, certified corn starch is likely to grow, particularly where suppliers can demonstrate GMP compliance and consistent batch-to-batch quality. The opportunity extends beyond Asia, as multinational generic producers align their excipient sourcing with the most stringent regional requirements to simplify compliance across markets.
Functional modification will drive value migration in food and beverage
The drive to reduce saturated fat, improve texture, and maintain clean labels is expanding the role of enzymatically modified waxy corn starch and other specialty grades. As formulators seek ingredients that deliver specific sensory and functional outcomes, the market will increasingly reward modification capability and co-development expertise. Commercial advantage will accrue to suppliers that can translate technical performance into measurable product benefits, support customer innovation pipelines, and secure long-term formulation partnerships rather than one-off transactions.
These trends carry inherent uncertainties. Feedstock prices could reverse course if weather patterns, trade policy, or energy costs disrupt agricultural markets, compressing margins for producers without hedging strategies or cost flexibility. Regulatory requirements may diverge further across regions, increasing compliance costs and complicating global supply strategies. Substitution risk also remains, as alternative starches, fibers, and synthetic excipients could capture share in specific applications if they offer better cost or performance profiles. Operators should therefore treat these trends as directional signals rather than guaranteed outcomes, and build optionality into capacity, certification, and customer engagement plans.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align capacity and capability with the segments where performance and compliance command premiums. This means investing in modification technology, pharma-grade quality systems, and bio-based documentation where demand is growing, while maintaining cost discipline in commoditized segments. Close technical collaboration with downstream formulators can shorten development cycles and lock in specification preferences early. Where regional demand is strong, localized capacity or partnership models can reduce logistics risk and improve service levels, as illustrated by recent expansions in the Middle East, India, and North America.
For investors, the market offers a differentiated risk-return profile across tiers. Commodity-scale operations provide volume and cash flow but face margin sensitivity to feedstock cycles and substitution pressure. Specialty and pharma-grade positions offer higher margins and regulatory-driven demand, but require sustained investment in quality systems, certifications, and technical service. Regional capacity plays can capture growth in underserved markets, though they carry execution and regulatory risk. A balanced view should weigh feedstock exposure, certification readiness, application mix, and the ability to serve regulated segments when evaluating potential investments or partnerships.
Modified Starch Market
For procurement and supply chain leaders, the strategic imperative is to diversify toward certified, bio-based, and functionally appropriate inputs while preserving supply security. Building relationships with suppliers that can demonstrate GMP compliance, ISO quality systems, and consistent bio-based content will reduce regulatory and reputational risk, particularly in pharmaceutical and institutional procurement. Qualifying multiple grades and regions can mitigate disruption risk, while co-development with suppliers can unlock formulation improvements that reduce total cost of ownership. In a market where performance and compliance increasingly determine supplier selection, procurement strategy should be treated as a value-creation function rather than a cost-minimization exercise.
The corn starch market is transitioning from a volume-driven commodity landscape to a performance-and-compliance-led specialty market. Capturing the available opportunities requires timely access to granular segmentation data, regional regulatory mapping, and supplier-level capability assessments. Decision-makers who integrate these inputs into capacity planning, investment selection, and procurement strategy will be better positioned to navigate feedstock volatility, regulatory divergence, and functional substitution while participating in the market's projected growth trajectory through 2032.
For detailed analysis of this topic, please visit the official page: Corn Starch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electrical Insulation Paper Market: 3.9% CAGR Growth and Strategic Shifts Through 2032
By pmarketresearch, 2026-09-21
The Electrical Insulation Paper Market: Navigating Strategic Shifts and Commercial Opportunities Through 2032
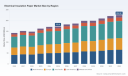
The electrical insulation paper market operates at the intersection of grid modernization, materials science, and industrial infrastructure. Valued at approximately 172.8 million USD in 2025, the sector has demonstrated a measured but steady trajectory over the past five years, recovering from a temporary contraction in 2022 before expanding to its current baseline. Looking ahead to 2032, the market is projected to reach roughly 224.9 million USD, reflecting a compound annual growth rate of 3.9 percent. This expansion is not merely a function of incremental demand; it signals a structural realignment in how electrical assets are designed, maintained, and decommissioned across mature and emerging economies alike. For executives and investors, the growth story masks a more nuanced reality: value creation will increasingly depend on technological differentiation, supply-chain resilience, and alignment with evolving regulatory frameworks.
The regional distribution of demand underscores this complexity. North America, Europe, and the Asia Pacific region collectively account for the largest share of consumption, with Asia Pacific standing out as both a volume driver and an innovation incubator. Latin America and the Middle East and Africa contribute smaller but growing portions, often tied to localized grid expansion, renewable integration, and aging asset replacement programs. Rather than treating geography as a static backdrop, it is more useful to view regional dynamics as distinct demand engines with different pacing, procurement cycles, and compliance requirements.
Market Snapshot and Core Challenges
The market's five-year arc from 2020 to 2025 reveals resilience in the face of supply disruptions and shifting project timelines. After reaching 142.8 million USD in 2020, the sector expanded to 152.1 million USD in 2021, experienced a brief pullback to 148.9 million USD in 2022, and then accelerated through 2023 and 2024 before stabilizing near 170.8 million USD and settling at 172.8 million USD in 2025. This pattern reflects the interplay of delayed infrastructure orders, inventory normalization, and the gradual ramp-up of high-voltage and distribution projects. The forward trajectory through 2032 suggests that growth will be incremental rather than explosive, with annual gains becoming more pronounced as capital expenditure cycles mature and replacement demand gains momentum.
Within this macro framework, several challenges and inflection points are reshaping how participants position themselves:
- Raw-material volatility and cost asymmetry : Cellulose-based insulation materials remain highly sensitive to pulp pricing and processing inputs. Recent cycles have shown cellulose pulp costs rising by 9–14 percent in certain production periods, contributing to roughly 28 percent fluctuation in overall production costs for insulation paper manufacturers. This volatility compresses margins for suppliers that lack long-term contract structures or value-added differentiation, while simultaneously creating pricing power for manufacturers that can secure stable feedstock or offer performance-guaranteed specifications.
- Regulatory and compliance pressure on processing : Environmental regulations governing emissions, wastewater, and chemical handling during paper processing are tightening across multiple jurisdictions. Producers operating in regulated regions face compliance costs estimated at 6–11 percent of operational expenditure. These requirements are not merely cost centers; they increasingly function as market-access gatekeepers, influencing procurement decisions for utilities and OEMs that must document the sustainability and compliance profile of their supply chains.
- Technology transition and specification shifts : The insulation paper segment is undergoing a quiet but meaningful shift in performance expectations. End users are demanding better thermal stability, longer service life, and more predictable behavior under load cycling and high-voltage stress. This creates a bifurcated market: commoditized grades compete primarily on price and availability, while engineered grades with thermal upgrading, controlled creping, and specialized coatings command premium positioning and longer-term contracts.
These challenges are not isolated. They interact with one another in ways that determine which players can scale profitably and which are forced into cyclical pricing battles. The organizations that navigate this environment effectively treat raw-material strategy, regulatory readiness, and product engineering as a single integrated capability rather than separate functional concerns.
Key Demand Drivers Behind Market Evolution
Understanding why the electrical insulation paper market is moving requires looking beyond top-line growth to the forces shaping procurement behavior, product design, and supply economics. Four drivers stand out as particularly decisive over the next several years.
Technological Innovation and Material Performance
Innovation in insulation paper is shifting from incremental grade improvements to system-level performance optimization. Manufacturers are investing in thermal upgrading technologies, controlled creping, and coating processes that enhance dielectric strength, reduce moisture absorption, and improve mechanical integrity under prolonged thermal stress. A notable example of this direction appeared in March 2026, when Weidmann Electrical Technology AG published technical guidance focused on optimizing transformer insulation systems for improved performance, cost efficiency, and supply reliability. Rather than presenting a single product launch, the release reflected a broader industry pivot toward helping customers design insulation systems that balance longevity, operational flexibility, and total cost of ownership.
This matters because insulation paper is increasingly evaluated not as a standalone material but as part of a transformer or cable insulation architecture. Buyers are more willing to pay for grades that reduce maintenance intervals, support higher loading conditions, and provide more consistent behavior across temperature and humidity ranges. For producers, the implication is clear: value is migrating toward engineered solutions and technical services, while undifferentiated commodity grades face persistent margin pressure.
Policy and Regulatory Environment
Policy frameworks are playing a larger role in shaping demand timing, product eligibility, and supplier qualification. Environmental regulations are raising the bar for emissions and processing standards, while grid policy in many regions is accelerating modernization programs that indirectly increase demand for reliable insulation materials. Utilities and equipment manufacturers are incorporating supplier compliance records into their procurement criteria, especially where public funding, environmental disclosures, or long-term service agreements are involved.
The compliance dimension also affects innovation pathways. Materials and processes that can demonstrate lower environmental impact, recyclable or sustainably sourced fiber inputs, and reduced processing emissions are becoming more relevant in bids and specification documents. This does not mean that regulation is a pure constraint; it also creates a qualification barrier that can protect established players with robust compliance infrastructure and penalize smaller competitors that struggle to absorb the operational expenditure associated with emissions control and documentation.
Electrical Insulation Tape Market
Demand-Side Behavior and Infrastructure Priorities
On the demand side, procurement behavior is being reshaped by asset age profiles, load growth, and the need to reduce outage risk. Power transformers and distribution transformers remain central to the insulation paper market, reflecting the continued reliance on transformer-based grid architecture even as alternative equipment formats evolve. At the same time, cable and wire applications, motors and generators, and capacitor-related uses contribute meaningful demand, each with its own specification requirements and replacement cycles.
A broader shift is also underway in how end users evaluate reliability. Rather than focus exclusively on lowest initial material cost, many buyers are weighing insulation performance against the financial and operational consequences of failure, especially in networks where outage costs are high or where renewable integration increases loading variability. This behavioral change favors suppliers that can provide consistency, traceability, and technical support, and it encourages longer-term purchasing relationships rather than spot-market procurement.
PW Consulting Chemical & Energy Research Center
Supply Chain and Cost Structure Dynamics
The cost structure of insulation paper production is tightly linked to kraft pulp availability, processing complexity, and logistics. Kraft pulp remains the primary raw material for cellulose-based electrical insulation paper, and its properties directly influence dielectric performance and mechanical durability. Sustainability perceptions around fiber sourcing can also influence buyer preferences, particularly where utilities or OEMs emphasize responsible procurement in their public commitments.
Recent pricing dynamics illustrate the sensitivity of the sector. Kraft pulp serves as the foundational input, and price movements can ripple quickly through producer cost models. For example, kraft pulp prices were recorded at 4,824 CNY/T on June 5, 2026, down 0.25 percent from the prior day and 23 percent over the preceding month, highlighting how quickly input costs can shift within a single production cycle. When combined with the broader pattern of cellulose-pulp price increases of 9–14 percent in recent cycles and the associated 28 percent fluctuation in production costs, the message is unambiguous: cost management is now a strategic capability, not a tactical accounting task.
Insulating Oil Market
Suppliers are responding by combining feedstock security, product mix optimization, and engineering differentiation. The most resilient operators are those that can maintain stable input access while directing more of their manufacturing capability toward grades that carry higher performance value and more defensible pricing.
Competitive Landscape and Leading Strategies
The competitive structure of the electrical insulation paper market is moderately concentrated, with the top three players accounting for roughly 35 percent of market share and the top five reaching about 42 percent. This concentration level suggests that while established manufacturers hold significant influence, there is still room for regional specialists, niche grade providers, and technology-focused entrants to compete on specification, service, or local responsiveness.
Strategic Positioning of Key Players
The market's leading participants differentiate themselves through a combination of material heritage, processing capability, product range, and technical engagement with customers.
- Weidmann Electrical Technology AG , headquartered in Rapperswil, Switzerland, is positioned around high-quality kraft flat paper and presspaper made from 100 percent electrical-grade kraft wood pulp. Its processing capabilities, including creping, coating, slitting, and transformer-focused processing, support a product portfolio aimed at performance-sensitive applications. The company's March 2026 technical guidance on optimizing transformer insulation systems highlights an approach that extends beyond material supply into system-level optimization, cost efficiency, and supply reliability. This kind of technical engagement helps anchor long-term relationships with customers that value engineering support as much as material consistency.
- Ahlstrom-Munksjö Oyj , based in Espoo, Finland, offers electrotechnical kraft insulation paper under the Elektro-Tek brand, serving power transformers, instrument transformers, and high-voltage cables. Its portfolio spans plain and creped grades, with thermal upgrading capabilities under Thermotrans. The breadth of its electrotechnical offering, combined with brand recognition in engineered paper solutions, gives the company a strong platform in segments where specification accuracy and thermal performance are critical. Its scale and material expertise also support consistent supply and documentation practices that are increasingly important to regulated buyers.
- Krempel GmbH , located in Vaihingen/Enz, Germany, leads in electrical insulation materials including kraft papers and composites for energy-sector transformers and components. Its positioning emphasizes an integrated view of insulation materials beyond paper alone, which can be attractive to customers seeking coordinated solutions across transformer and component applications. In a market where material interaction and system reliability matter, a composite-aware portfolio can support stronger specification influence and deeper engineering partnerships.
- Cottrell Paper Company, Inc. , a family-owned manufacturer in Rock City Falls, New York, has produced high-grade electrical insulating papers and specialty materials since 1926, including copaco and glazed variants for transformers and motors. Its long operational history and family-owned structure contribute to a positioning centered on continuity, specialty grade depth, and relationship-based service. For certain regional and application-specific buyers, this profile can be a meaningful differentiator, particularly where supply continuity and product familiarity are valued alongside technical performance.
How the Competitive Landscape Is Evolving
The market is not static. Several patterns are shaping its evolution:
- Consolidation pressure on scale and compliance : Larger producers benefit from broader product portfolios, stronger compliance infrastructure, and greater ability to absorb raw-material volatility. This encourages gradual consolidation or partnership activity, especially where feedstock access, technical service capacity, or regional distribution networks need reinforcement.
- Differentiation through engineered grades : As commoditized segments face pricing pressure, competition increasingly centers on thermal upgrading, grade consistency, coating technology, and technical support. Players that can validate performance claims and reduce customer risk are better positioned to maintain margins and win specification decisions.
- Regional and specialty niches remain viable : Despite concentration at the top, the market still rewards localized responsiveness, long-standing customer relationships, and specialized grades for motors, capacitors, and cable applications. New entrants and smaller manufacturers can compete by serving underserved specifications or by offering flexible service models that larger players may not prioritize in every region.
Forward-Looking Trends and Commercial Implications
If current dynamics persist, three trends are likely to shape the market over the next three to five years.
Trend One: Performance Specifications Will Become More System-Centric
Insulation paper will increasingly be evaluated in the context of complete insulation systems rather than as a standalone commodity. Thermal upgrading, controlled processing, and application-specific grading will matter more as utilities and OEMs seek to manage load cycling, extend asset life, and reduce failure risk. The commercial opportunity lies in helping customers match material grades to actual operating conditions, which can justify premium pricing and create stickier relationships. The risk is that suppliers who cannot demonstrate measurable performance benefits may be forced into price competition or replaced by alternatives that offer clearer technical value.
Trend Two: Cost and Compliance Will Function as Strategic Filters
Raw-material volatility and regulatory compliance costs will continue to influence both supplier survival and buyer selection. Producers that can stabilize input exposure, optimize product mix, and document compliance with confidence will be better placed to protect margins and win long-term contracts. The opportunity is to treat these factors as part of a broader value proposition rather than as overhead. The risk is that short-term pricing pressure leads to underinvestment in compliance and quality systems, which can erode trust and restrict access to regulated or quality-sensitive markets over time.
Trend Three: Regional Demand Will Diverge in Pace and Preference
Growth will not be uniform across regions. Some markets will be driven by grid expansion and new asset installation, while others will be shaped by replacement cycles, load growth, and selective modernization. Procurement preferences will also diverge, with some regions emphasizing price competitiveness and others prioritizing reliability, traceability, and compliance documentation. This creates opportunities for suppliers that can tailor product offerings, service models, and commercial terms to regional realities. The risk is that a one-size-fits-all strategy leaves a company over-exposed in slower-growing markets while under-serving faster-growing ones.
Strategic Recommendations for Decision Makers
For manufacturers, investors, and procurement leaders, the practical question is how to translate these dynamics into action. A few strategic priorities stand out.
For Manufacturers and Suppliers
- Shift value capture toward engineered solutions : Reduce reliance on undifferentiated commodity grades by expanding thermal upgrading, coating, and custom processing capabilities. Pair product innovation with technical support that helps customers optimize insulation system design, because performance validation is becoming a key determinant of specification wins.
- Build feedstock and cost resilience : Lock in stable input access where possible, hedge exposure to pulp price swings, and use product mix to balance margin variability. Cost volatility is large enough that manufacturers without a clear feedstock and pricing strategy will find it difficult to sustain profitability through cyclical swings.
- Invest in compliance as market access, not just cost control : Treat emissions, processing, and documentation requirements as part of the competitive moat. Buyers in regulated environments increasingly use compliance status as a qualification filter, so robust compliance capability can open doors even when price alone is not the deciding factor.
For Investors
- Focus on differentiation and system-level capability : Evaluate companies not only on volume and footprint but also on technical engagement, engineered product depth, and the ability to reduce customer risk. In a market where performance expectations are rising, these qualities are more likely to support durable pricing than pure scale alone.
- Monitor feedstock exposure and margin structure : Because production costs can fluctuate significantly with cellulose pulp pricing, investor diligence should include how a company manages input volatility, whether it has contract structures that stabilize costs, and how much of its revenue comes from premium grades versus commoditized segments.
- Watch regulatory-driven consolidation signals : Compliance costs and qualification requirements can advantage larger, better-resourced players. Investment theses should consider whether a target is positioned to gain from consolidation or whether it depends on a niche that remains defensible despite increasing scale and regulatory pressure.
For Procurement and End-User Decision Makers
- Evaluate total cost of ownership rather than material price alone : Insulation paper choices affect maintenance intervals, thermal behavior, and asset reliability. Procurement processes that weigh lifecycle risk, specification accuracy, and supplier technical support are better aligned with long-term operational goals than those focused narrowly on initial purchase cost.
- Require documentation and traceability : Given tightening compliance expectations and the importance of responsible sourcing, buyers should seek clear documentation on material origin, processing standards, and performance validation. This not only supports regulatory and sustainability objectives but also reduces uncertainty in storage, handling, and application.
- Plan for specification evolution : As insulation requirements become more system-centric, procurement teams should anticipate changes in grade selection, thermal upgrading needs, and supplier collaboration. Early engagement with suppliers on performance targets and operating conditions can prevent mismatches and improve long-term supply reliability.
The electrical insulation paper market is entering a phase where growth, competition, and value creation are increasingly determined by technical differentiation, cost resilience, and regulatory readiness. The broad trajectory through 2032 points to steady expansion, but the real strategic prize will go to organizations that can align product engineering, supply-chain planning, and compliance capability with the evolving expectations of utilities, OEMs, and regional project markets. For decision makers seeking a more granular view of segmentations, regional dynamics, and actionable commercial scenarios, the full PW Consulting study provides deeper quantitative breakdowns and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrical Insulation Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hydraulic Accumulator Market: Why 5.6% CAGR and Asia Pacific's 97M Rise Through 2032
By pmarketresearch, 2026-09-21
Hydraulic Accumulator Market: Strategic Trends and Commercial Opportunities Through 2032
The hydraulic accumulator market has entered a phase of measured, value-driven expansion, with the global market reaching an estimated 179.0 million USD in 2025 and projected to advance to 262.0 million USD by 2032, reflecting a compound annual growth rate of 5.6 percent. This trajectory, spanning historical growth from 130.0 million USD in 2020 through the post-pandemic recovery period, signals a market that has matured beyond cyclical swings and is now responding to structural shifts in industrial automation, equipment electrification, and fluid power system optimization. The headline numbers tell a story of steady compound growth, but the real strategic value lies in understanding where that growth is concentrated, which forces are reshaping competitive dynamics, and how operators can position themselves ahead of the next inflection point.
For executives and investors, the market presents a paradox: growth is broad-based yet uneven, volume is expanding but margin pressure is intensifying in segments exposed to raw material volatility, and regulatory frameworks are tightening even as commercial adoption accelerates in adjacent mobility and industrial applications. This article maps the current landscape, isolates the drivers reshaping demand and supply, examines how leading manufacturers are differentiating, and outlines the trends that will define competitive positioning over the next three to five years.
Market Snapshot and Structural Challenges
The market's evolution from 2020 to 2025 illustrates a compound trajectory shaped by both recovery and structural demand. After starting at 130.0 million USD in 2020, the market climbed through successive years, reaching 179.0 million USD in 2025. The forecast window through 2032 suggests continued expansion toward 262.0 million USD, with the pace of growth reflecting a blend of incremental adoption in established equipment categories and emerging pull from applications that leverage hydraulic energy storage for efficiency, shock absorption, and power smoothing.
Concentration and Competitive Fragmentation
Market structure remains moderately concentrated, with the top three players accounting for roughly 41.0 percent of revenue and the top five capturing approximately 45.0 percent. This concentration level indicates that while leading manufacturers hold meaningful share, the market retains room for regional specialists, application-focused suppliers, and new entrants targeting niche performance requirements. The fragmented long tail matters strategically because it means pricing power is not uniformly distributed, and competitive advantage increasingly depends on application expertise, certification portfolios, and service economics rather than scale alone.
Key Challenges and Inflection Points
- Raw material and component cost volatility: High-grade steel alloys and specialty elastomers used in accumulator shells and sealing systems have experienced price swings of 15 to 25 percent within a single year, directly influencing total cost of ownership and squeezing margins for manufacturers that cannot pass through input cost fluctuations or hedge procurement exposure.
- Regulatory compliance as a barrier and differentiator: Standards such as EN 14359 for gas-loaded accumulators, DIN EN ISO 4413 for hydraulic fluid power systems, and the Pressure Equipment Directive 2014/68/EU continue to govern design, safety, and pressure relief requirements. Compliance is no longer a checkbox; it is a competitive filter that raises the bar for new entrants and rewards incumbents with established certification infrastructure and testing capabilities.
- Shifting demand mix and application migration: Traditional reliance on construction and mobile hydraulics is being complemented by growth in machine tools, agriculture equipment, and adjacent automotive-related applications, creating a more complex demand profile that rewards manufacturers capable of serving multiple end-use segments with tailored architectures and sealing solutions.
Core Demand Drivers Reshaping the Market
The market's trajectory is not being pulled by a single force; it is being reoriented by a combination of technology, regulation, demand-side behavior, and cost structure dynamics. Each driver has distinctive implications for product roadmaps, go-to-market strategy, and investment timing.
PW Consulting Automotive & Machinery Research Center
Technology Innovation and System-Level Efficiency
Technological progress in hydraulic accumulators is increasingly focused on system-level benefits rather than component isolation. Innovations in bladder, piston, and diaphragm architectures are enabling better charge retention, faster response, and longer service life under demanding pressure cycles. Manufacturers are integrating advanced sealing materials, improved nitrogen pre-charge controls, and more robust shell designs to extend operational endurance and reduce maintenance frequency. These advances matter because they shift the value proposition from pure component replacement toward lifecycle efficiency, where lower downtime and extended service intervals can justify premium positioning.
Suppliers with in-house material capabilities and global certification portfolios are particularly well placed to accelerate these improvements, since material selection and sealing performance directly influence reliability under high-cycle conditions. The practical implication for buyers is that specification decisions increasingly hinge on documented endurance and compliance readiness rather than unit price alone.
Policy and Regulatory Environment
Regulatory frameworks are tightening in ways that both constrain and enable commercial activity. The sixteenth revision of DOT-SP 9998, granted in November 2025, authorized seamless steel hydraulic accumulators containing compressed nitrogen for commercial transportation. This development opens a pathway for accumulator use in transport-related hydraulic systems and signals a broader willingness to align safety frameworks with evolving application needs. At the same time, European standards such as EN 14359 and the Pressure Equipment Directive continue to require pressure relief devices and rigorous design controls, reinforcing a compliance-first market culture.
For manufacturers, the regulatory trend is twofold: it raises the cost of market entry for those without established testing and certification capabilities, and it creates a defensible moat for companies that can demonstrate conformance across multiple jurisdictions. For commercial transporters and equipment integrators, clearer authorization pathways reduce uncertainty and can accelerate adoption in fleets and mobile systems where hydraulic energy buffering offers measurable operational benefits.
Industrial Hydraulic Shock Absorber Market
Demand-Side Behavior and Equipment Modernization
End-use demand is being reshaped by equipment modernization cycles and the push for more efficient fluid power systems. Construction equipment remains a substantial application anchor, while machine tools and agriculture equipment contribute meaningful volume as manufacturers seek shock absorption, pressure compensation, and energy recovery features that improve machine stability and reduce wear. A smaller but strategically important share comes from automotive-adjacent applications, where hydraulic accumulators support systems that benefit from compact energy storage and rapid response characteristics.
The demand pattern suggests that buyers are increasingly evaluating accumulators as part of integrated system performance rather than as standalone spares. This behavior favors suppliers that can provide application engineering support, configuration guidance, and aftermarket service access, because total system reliability and uptime are becoming central procurement criteria.
Supply Chain and Cost Structure Dynamics
Cost structures remain under pressure from input volatility and the operational demands of serving a fragmented global customer base. High-grade steel alloys and specialty elastomers are subject to annual price swings that can materially affect landed cost and margin planning. At the same time, supply chain resilience is becoming a procurement concern, particularly for buyers who depend on timely delivery of certified components for maintenance, retrofit, and new equipment builds.
Manufacturers that combine strategic sourcing, certified component traceability, and regional service coverage are better positioned to stabilize delivery performance and reduce exposure to commodity volatility. For buyers, this means supplier selection should weigh not only price but also sourcing transparency, certification documentation, and the ability to support unplanned maintenance without extended lead times.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of global manufacturers, application specialists, and certification and testing providers that together shape both product availability and market credibility. Companies such as HYDAC International GmbH, Parker Hannifin Corporation, Danfoss Power Solutions, Bosch Rexroth AG, Accumulators, Inc., Freudenberg Sealing Technologies, STAUFF AG, NOK Corporation, Eaton Corporation, SFP Hydraulics, Inc., Roth Hydraulics GmbH, Airline Hydraulics, Teutonic Engineering, and SGS Group illustrate the diversity of positions in the market, from full-spectrum accumulator production to sealing technology expertise and independent testing and certification services.
Differentiation and Strategic Positioning
Leading manufacturers are differentiating along several practical dimensions rather than competing on specification sheets alone.
- Product breadth across accumulator types: Several incumbents offer bladder, piston, and diaphragm variants across industrial and mobile hydraulics, enabling them to serve a wider range of system sizes and application requirements without forcing customers to manage multiple specialized suppliers.
- Material and sealing expertise: Suppliers with in-house materials capabilities and global certifications can move faster on reliability improvements and compliance documentation, which is especially valuable in markets where pressure vessels and safety standards are closely scrutinized.
- Service and repair ecosystems: Manufacturers that provide repair kits, replacement components, and field support create recurring engagement with end users, turning a transactional component purchase into a long-term service relationship.
- Certification and testing credibility: Independent testing and certification providers play an important role in validating pressure vessel integrity and safety compliance. Their involvement raises market trust and can become a differentiator for manufacturers that consistently meet recognized standards.
- Regional presence and application focus: Companies with strong positions in specific geographies or end-use segments can tailor product configurations, documentation, and support to local requirements, which is valuable in markets where standards interpretation and service expectations vary.
Market Structure Evolution
The market is evolving through a combination of consolidation among larger players, continued specialization by regional and application-focused suppliers, and selective entry by firms targeting performance-driven niches. The moderate concentration levels suggest that scale matters, but it does not dominate the market to the point where smaller players are excluded. Instead, the competitive frontier is shifting toward companies that can combine credible certification, reliable material supply, application-specific engineering, and responsive service.
Gas & Liquid Separation Accumulator Market
This dynamic creates opportunity for suppliers that can demonstrate measurable reliability advantages and for buyers that can reduce lifecycle risk by partnering with manufacturers whose compliance posture and service networks match their operating environment. It also means that mergers, acquisitions, and partnership activity may increase as larger players seek to strengthen material capabilities, geographic coverage, or certification portfolios.
Future Trends and Commercial Opportunities
Looking across the 2026 to 2032 forecast window, three interconnected trends are likely to shape where value is created and where risk concentrates.
Trend One: Lifecycle Value Replaces Unit Price as the Central Buying Criterion
As equipment owners face pressure to reduce downtime and extend service intervals, accumulator purchases will be evaluated increasingly through total cost of ownership rather than initial price. This trend favors products with documented durability, stable pre-charge performance, and strong aftermarket support. The commercial opportunity lies in packaging reliability data, service access, and compliance documentation into a cohesive value proposition that reduces operating risk for end users.
The associated risk is that manufacturers without robust service infrastructure or material traceability may find it harder to compete in segments where uptime and compliance assurance matter most.
Trend Two: Regulatory Alignment Expands Use Cases in Commercial Transportation and Adjacent Mobility
The authorization of seamless steel hydraulic accumulators containing compressed nitrogen for commercial transportation marks a meaningful signal that regulatory frameworks can adapt to support new applications when safety criteria are clearly met. If this pattern continues, it could broaden the addressable market in transport-related hydraulic systems and encourage integrators to consider hydraulic energy buffering in fleet and mobile equipment designs.
The opportunity is to prepare product portfolios, documentation, and testing evidence for transport-oriented requirements before demand materializes at scale. The uncertainty is that regulatory progress can be uneven across jurisdictions, and standards such as EN 14359 and the Pressure Equipment Directive will continue to define the safety baseline, which means compliance readiness must be sustained rather than treated as a one-time achievement.
Trend Three: Material Volatility and Sourcing Strategy Become Competitive Differentiators
With high-grade steel alloys and specialty elastomers subject to significant annual price swings, companies that manage procurement strategically, maintain certified traceability, and communicate cost-transparently will be better positioned to protect margins and customer trust. The commercial opportunity is to treat sourcing resilience as a selling point, particularly for buyers who are sensitive to lead times, certification integrity, and unpredictable maintenance costs.
The risk is that unmanaged input cost volatility can erode competitiveness in price-sensitive segments and complicate long-term quoting and service pricing. Manufacturers that cannot stabilize their cost base may be forced into reactive pricing moves that weaken customer relationships.
Strategic Actions for Decision Makers
The market is creating clear points of leverage for different stakeholder groups, but capturing them requires timely, segment-specific intelligence rather than broad market assumptions.
For Manufacturers and Suppliers
- Prioritize lifecycle value messaging: Build product narratives around durability, service interval extension, and compliance documentation, supported by application-specific evidence where possible. This aligns with the shift toward total cost of ownership and helps defend positioning against commodity-driven price competition.
- Strengthen material and certification readiness: Invest in sourcing stability, traceability, and certification coverage to reduce exposure to input volatility and to meet the expectations of buyers operating under pressure equipment and fluid power standards. This is especially relevant for firms targeting transport-related and safety-intensive applications.
- Expand service and repair engagement: Where feasible, deepen aftermarket support through repair kits, replacement components, and technical assistance. Recurrent service relationships can improve customer retention and provide a buffer against transactional price pressure.
For Investors and Strategic Partners
- Focus on differentiation that compounds: Assess companies based on in-house material capability, certification breadth, service coverage, and application expertise rather than scale alone. These attributes are more likely to sustain margin and share over the forecast period than volume growth in isolation.
- Monitor regulatory-enabled expansion carefully: Track developments such as transport authorization pathways and evolving safety standards, since these can open new use cases but also raise the compliance bar. Investments should account for both the upside of expanded application scope and the cost of maintaining conformance.
- Watch consolidation signals: Moderate concentration and a long tail of specialists suggest that selective M&A or partnership activity could reshape regional coverage, material access, and certification capabilities. Strategic positioning should consider how such moves might alter competitive dynamics in target segments.
For Procurement and Equipment Integrators
- Evaluate suppliers on total operating risk: Compare accumulator options not only by unit cost but by documented reliability, certification status, service availability, and sourcing transparency. Suppliers that can reduce maintenance uncertainty and speed unplanned Repairs may deliver lower lifecycle cost even if initial pricing is higher.
- Align specifications with application reality: Match accumulator type and configuration to the actual pressure cycles, environmental conditions, and maintenance expectations of the equipment. Over-specifying or under-specifying can both create hidden cost, so application engineering support should be part of the selection process.
- Use compliance documentation as a selection filter: Verify that suppliers meet relevant standards and can provide the testing and certification evidence needed for your operating jurisdictions. This reduces integration risk and supports smoother approval processes in regulated environments.
Getting Ahead with Segment-Level Intelligence
The strategic signals in this market are clear at the macro level, but the practical decisions that determine competitive outcomes are made in the details: which applications are expanding fastest, how regional demand is shifting, where margin is being protected or eroded, and which compliance or sourcing assumptions will hold over the next planning cycle. Broad market figures establish direction, but actionable positioning depends on segment-level data, customer behavior trends, and a realistic view of where competitive advantage can be sustained.
PW Consulting's complete research report provides deeper segmentation data, company-level profiling, and tailored recommendations designed to support procurement, investment, and product strategy decisions. For teams that need to move from market awareness to executed planning, the full study offers the granularity required to translate these trends into specific next steps.
For detailed analysis of this topic, please visit the official page: Hydraulic Accumulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fiber Cement Board Market: Decoding 4.88% CAGR and Regional Shifts to 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Global Fiber Cement Board Market
The global fiber cement board market has entered a phase of measured but structurally significant expansion. Over the 2020 to 2025 period, total market revenue moved from 105.0 million USD to 133.1 million USD, reflecting a compound trajectory that accelerated notably in the latter half of the decade. The five-year forecast extending to 2032 projects the market will reach 183.8 million USD, underpinned by a CAGR of 4.88 percent. These figures point to more than cyclical recovery or inventory correction; they indicate a maturing replacement cycle where builders, architects, and property owners are steadily shifting toward materials that deliver durability, regulatory compliance, and lifecycle value. The market is not a high-growth commodity story. It is a technology-enabled building materials segment where performance specifications, code alignment, and manufacturing footprint increasingly determine competitive outcomes.
At the same time, the growth path is not uniform across regions, applications, or product densities. The aggregate numbers mask a landscape defined by divergent demand drivers, raw material transitions, and a concentrated competitive field in which a handful of established players account for a disproportionate share of revenue. For executives and investors, the central question is no longer whether fiber cement boards will continue to gain share against alternative cladding and sheathing products. The question is where margin, capacity, and differentiation will be created over the next three to five years, and which structural shifts will separate leaders from laggards.
Market Snapshot and Structural Realities
The current market environment reflects a combination of post-pandemic normalization, project pipeline recovery, and deliberate product substitution. After a contraction in 2024, when revenue dipped relative to 2023, the market rebounded in 2025 with renewed demand across key geographies and applications. This pattern suggests that earlier softness was partly tied to supply chain adjustments, pricing pressure, and project timing rather than a fundamental loss of demand for fiber cement solutions. The forward curve shows steady annual increases in the forecast window, indicating that underlying adoption drivers remain intact.
Two structural realities deserve attention. First, the market exhibits meaningful concentration, with the top three and top five players sharing the same combined market share level. This concentration signals that scale, brand trust, distribution reach, and technical certification are powerful moats. New entrants face a steep climb unless they bring a clearly differentiated value proposition, such as specialized regional compliance, innovative surface treatments, or cost-optimized manufacturing for underserved segments. Second, revenue growth is being shaped by a mix of mature replacement demand and targeted new-construction adoption, particularly where building codes, weather risk, and fire performance increasingly favor dense, non-combustible board products.
Key Challenges Shaping the Next Phase
The first challenge is the tension between performance premiums and cost sensitivity. Fiber cement boards compete against wood-based, vinyl, and traditional masonry-adjacent solutions that can offer lower upfront cost or familiar installation workflows. In price-sensitive segments, bidding pressure can compress margins unless manufacturers can anchor value in durability, reduced maintenance, lower insurance or code-related risk, and consistent aesthetic performance over time. The commercial opportunity lies in translating technical superiority into total cost of ownership narratives that resonate with developers, general contractors, and specifying architects.
The second challenge is regulatory complexity and geographic variability. Building codes, hurricane-zone requirements, fire-resistance certifications, and procurement rules differ across markets and sometimes within regions. Compliance burdens can slow specification if manufacturers cannot present clear, locally recognized certifications and test data. This is not a barrier that disappears with scale alone; it requires continuous investment in product validation, documentation, and market-specific positioning. Companies that treat compliance as a strategic asset rather than a cost center are better positioned to win in high-risk or fast-growing zones.
The third challenge is raw material and supply chain evolution. Shifts in fiber choice, cement sourcing, and production location can alter cost structures and lead-time reliability. Demand for cellulose fiber, for example, has been gaining momentum, supported by sustainability preferences and performance characteristics. This transition creates both opportunity and execution risk. Manufacturers must manage the technical integration of alternative fibers, ensure consistent board quality, and align procurement strategies with changing input availability and pricing dynamics.
Core Drivers of Market Change
Technology, Product Performance, and Specification Multipliers
Innovation in fiber cement is less about radical product reinvention and more about incremental performance gains that compound into specification advantage. Denser board formulations, improved surface finishes, consistent color stability under UV exposure, and enhanced resistance to moisture, impact, and fire conditions all increase the likelihood of repeat specification. When a manufacturer can demonstrate non-combustible behavior, long-term color integrity, and resilience under harsh environmental conditions, the product becomes easier to defend in architect-led selections and code-driven projects. Over time, these attributes function as a specification multiplier, reducing the effort required to justify premium positioning.
Recent market activity underscores the importance of linking product performance with event-driven visibility. At a major architecture and design conference in 2025, a manufacturer highlighted resilient exterior cladding solutions designed for hurricane exposure and fire resistance, with domestically produced fiber cement panels as a central part of the presentation. This type of engagement is strategically meaningful because it places performance claims directly in front of specifiers at the moment when design decisions are being shaped. In a category where trust and repeat use matter, trade presence and demonstration of localized production can reinforce both technical credibility and supply assurance.
Policy, Code Alignment, and Procurement Rules
Regulatory and procurement dynamics are reshaping demand patterns in ways that favor manufacturers with appropriate certifications and domestic production capability. In regions exposed to high-velocity wind events and elevated fire risk, approval for specific building zones and fire safety certifications can substantially improve a product’s eligibility for bids and specifications. Similarly, public and infrastructure-linked projects in North America increasingly emphasize domestic manufacturing eligibility. A manufacturer that achieves such certification gains an advantage in projects where sourcing rules require or strongly prefer locally produced materials. This is not merely a compliance detail; it is a market access lever that can influence project qualification and specification preferences.
The strategic implication is clear. Companies that proactively map code pathways, secure relevant certifications, and communicate compliance status in a credible, product-specific way are better positioned to capture demand in regulated segments. In contrast, manufacturers that treat certifications as passive credentials may find themselves slower to enter high-value projects or vulnerable to displacement by competitors with stronger documentation and local production credentials.
Demand-Side Shifts in Construction and Renovation Behavior
On the demand side, two overlapping trends are influencing adoption. The first is renovation and replacement activity driven by aging building stock and the desire to reduce maintenance frequency. Fiber cement boards appeal in these scenarios because they are associated with long service life, resistance to rot and insect damage, and lower repainting or repair burdens compared with certain alternatives. The second trend is new-construction demand in geographies where durability and risk mitigation carry greater monetary and operational weight. In coastal, high-heat, or wildfire-adjacent environments, specification choices increasingly reward materials that can help manage exposure to weather and fire risk.
Demand is also being shaped by design and finish expectations. Architects and builders are not only asking whether a board performs; they are asking whether it can deliver consistent aesthetics across large façades, support a range of surface treatments, and maintain appearance over time without excessive fading or degradation. Products that combine performance with predictable appearance and ease of integration into broader cladding systems tend to gain stronger repeat use. For commercial decision-makers, this means that the specification conversation is shifting from feature-level claims to long-term reliability and design continuity.
Supply Chain, Manufacturing Footprint, and Cost Structure
Capacity expansion and manufacturing location decisions are becoming central to competitive positioning. One of the most telling signals in recent market activity came from a major manufacturer announcing a substantial global spending program to support fiber cement production growth for the following fiscal year. A capacity investment at this scale signals confidence in sustained demand, a need to protect lead times, and a desire to maintain flexibility across multiple markets. It also reflects the reality that in concentrated categories, supply assurance can be as important as product features, particularly when project timelines are tight and specification windows are narrow.
Fiber Cement Market
At the same time, cost structures are influenced by input transitions and the economics of domestic versus international production. Manufacturers that can balance scale efficiency with localized output may be better positioned to serve procurement rules, reduce freight exposure, and respond faster to regional demand shifts. The broader point is that fiber cement is moving toward a market where manufacturing strategy, input mix, and distribution resilience are inseparable from commercial competitiveness. Businesses that optimize only for unit cost without considering service reliability, certification alignment, and specification support risk underdelivering in high-stakes segments.
Cement Boards Market
Competitive Landscape and Leading Strategies
Concentration as a Signal of Scale and Trust
The market’s concentration structure indicates that scale, established distribution, and recognized brand positioning remain powerful differentiators. The leading companies operate across multiple geographies and product lines, often combining siding, cladding, roofing-adjacent, and interior or partition applications into broader portfolios. This breadth allows them to serve repeat customers across project types and to capture value not just from a single application but from the broader specification ecosystem. It also creates difficulty for smaller competitors that lack similar multi-application reach or the ability to support large regional programs end to end.
Several established manufacturers illustrate distinct strategic approaches. One global leader in fiber cement siding and backer board production operates with a network of plants and continues to invest in capacity expansion to meet anticipated demand. Its commercial logic is rooted in scale, traceability, and the ability to sustain supply across markets while reinforcing brand trust. A Japanese manufacturer produces high-performance siding and panels with domestic manufacturing and resilience certifications, positioning product validation and quality assurance as core equity. A European group offers high-density cladding and boards through a recognized brand identity, relying on international production facilities to serve architectural and façade applications. A Swiss-based panel and cladding producer, incorporating former product lines into its portfolio, focuses on architectural applications where finish consistency and specification support matter.
Regional Specialists and Application-Focused Positioning
Not all competitive advantage is built on global scale. Some manufacturers compete by anchoring their position in specific regions or application verticals. An Indian producer supplies boards for ceilings, walls, and partitions with an emphasis on asbestos-free offerings, aligning product positioning with health, safety, and local building requirements. A U.S.-based company distributes and manufactures high-density compressed panels and siding for North American markets, leveraging proximity to specification channels and regional procurement expectations. A Thailand-based global supplier addresses wall, ceiling, and flooring applications, using a broad application footprint to move across multiple construction use cases.
These regional or application-focused players often succeed by reducing distance to the specifier, tailoring product support to local codes and preferences, and maintaining a clear value story around compliance, indoor safety, or application versatility. Their challenge is to scale that positioning without diluting specialization. Where they can combine local relevance with consistent quality and credible certification, they can establish durable niches even in a concentrated market.
Strategic Moves Shaping the Landscape
Recent developments highlight two recurring strategic themes: performance-led specification support and supply assurance through localized production. At a major design event, a manufacturer showcased domestically produced resilient cladding solutions with hurricane and fire resistance, reinforcing both product capability and local manufacturing credibility. In parallel, a large capacity expansion announcement signaled that one of the market’s leading players expects continued demand and is willing to commit significant capital to support growth. These moves suggest a landscape in which competitive advantage is increasingly tied to visible performance claims, code readiness, and the ability to deliver reliably where projects are awarded.
The market structure appears likely to remain concentrated, but with room for targeted differentiation. Consolidation pressure may continue where scale and compliance portfolios confer strong advantages. At the same time, fragmentation can persist in specialized applications or regions where local certification, application knowledge, and responsive service create meaningful separation. New entrants are unlikely to win on commodity terms. More plausible paths include focused offerings around specific density categories, specialty surface finishes, region-specific compliance, or sustainable fiber integration, provided these are backed by credible testing and market-specific documentation.
Forward Outlook: Trends and Commercial Implications
Trend One: Performance Certification Becomes a Commercial Accelerator
Over the next three to five years, the ability to demonstrate code alignment, fire safety credentials, hurricane-zone suitability, and consistent UV or weather performance will increasingly act as a commercial accelerant rather than a defensive requirement. Specifiers and project teams are likely to favor products that reduce risk in the approval process and simplify the justification for premium materials. This favors manufacturers that can package test results, certification status, and application guidance into clear specification tools. The commercial opportunity is in reducing friction: the easier it is to validate performance and eligibility, the faster a product can become a default choice in relevant projects.
Commercial implication: Companies should invest in product documentation, specifier-facing evidence, and market-specific approval visibility. Where certification opens doors to high-risk or public-sector projects, it should be treated as a growth enabler and communicated with precision.
Trend Two: Capacity, Location, and Supply Assurance Will Separate Leaders
Demand growth combined with procurement expectations around domestic production and reliable delivery is likely to make manufacturing footprint more strategically important. Capacity expansion where demand is durable, supported by credible local sourcing or certification, can strengthen a manufacturer’s ability to win time-sensitive projects and meet specification requirements that favor regional output. This trend may intensify as project pipelines recover and as buyers place greater weight on supply continuity and compliance credentials.
Commercial implication: Businesses should evaluate where capacity investments, input strategy, and regional production can unlock access to preferred procurement channels. In many cases, the value of capacity is not only volume; it is the ability to meet qualification rules and protect lead times in competitive bidding environments.
PW Consulting
Trend Three: Sustainability-Linked Material Shifts Will Reshape Cost and Positioning
The growing role of cellulose fiber in fiber cement board production signals a broader shift toward material choices that align with sustainability preferences and performance needs. With cellulose fiber identified as the fastest-growing raw material input in the category, manufacturers that can integrate it effectively while maintaining board quality and cost discipline may gain a narrative advantage. Sustainability in this context is not only environmental positioning; it can influence procurement decisions, brand perception, and specification preferences, especially when paired with credible claims and consistent product outcomes.
Commercial implication: Material transitions should be managed as product strategy, not just procurement optimization. Where cellulose fiber or other input shifts can be tied to verifiable sustainability benefits and maintained performance, they can support both commercial differentiation and long-term relevance. The risk lies in executing the switch without compromising quality, consistency, or cost competitiveness.
Risk Factors and Uncertainties
Despite constructive fundamentals, several uncertainties remain. Housing and construction cycles can create uneven demand, particularly if interest rates, labor availability, or project financing conditions tighten in key regions. Regulatory environments can also shift, altering which certifications matter most or changing procurement preferences in public projects. Raw material pricing and availability may affect margins, especially if input transitions are not managed carefully. Finally, competitive pressure from alternative materials will persist in segments where upfront cost or installation familiarity remains the dominant decision factor. Leaders will need to manage these risks by maintaining flexible capacity plans, robust compliance portfolios, and clear total-cost narratives.
Actionable Guidance for Decision-Makers
For Manufacturers
- Treat certification and specification support as revenue-enabling assets. Align product claims with regionally relevant codes, fire safety requirements, and resilience standards, and make documentation easy for specifiers to use.
- Evaluate capacity and sourcing strategy against market access, not just unit cost. Where domestic production, procurement eligibility, or localized service improves qualification odds, those factors should carry explicit strategic weight.
- Manage raw material transitions with product integrity in mind. If shifting toward cellulose fiber or other evolving inputs, ensure the change is supported by consistent quality controls and a defensible performance story.
For Investors
- Focus on companies with credible compliance portfolios, visible expansion commitments, and the ability to win in regulated or high-risk applications. In concentrated markets, these capabilities often translate into more durable revenue streams.
- Assess exposure to demand volatility across geographies and applications. Diversified application reach and multi-region manufacturing footprints can reduce dependence on any single project cycle.
- Watch for material strategy as a differentiator. Manufacturers that execute input transitions well may strengthen both cost structures and sustainability positioning, while poor execution can create quality or margin risk.
For Procurement and Specification Teams
- Prioritize products that reduce project risk through clear certification, consistent performance data, and reliable supply. In commission-sensitive or high-exposure environments, easier approval and stronger documentation can outweigh marginal cost differences.
- Evaluate total installed cost and lifecycle implications rather than initial price alone. Products that lower maintenance burden or improve durability may offer better long-term value, especially in demanding climates or code-heavy applications.
- Confirm sourcing eligibility and lead-time reliability early in the specification process. Projects with tight schedules or procurement requirements can be disproportionately affected by supply uncertainty.
Closing Perspective
The fiber cement board market is poised for steady expansion, but the shape of that expansion will be defined by more than volume growth. Competitive outcomes will increasingly depend on performance credibility, code alignment, manufacturing resilience, and the ability to translate technical advantage into specification ease. Businesses that treat compliance, capacity, and material strategy as integrated commercial levers are better positioned to capture durable share in a concentrated and specification-driven market. For decision-makers seeking deeper segmentation detail, cost-structure analysis, and tailored scenario planning across regions and applications, the full PW Consulting research report provides a more granular basis for strategy development and investment decisions.
For detailed analysis of this topic, please visit the official page: Fiber Cement Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
High-End Household P1.29 LED Display Market: Why 7.8% CAGR Signals a Strategic Reset
By pmarketresearch, 2026-09-21
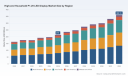
Strategic Trends and Commercial Opportunities in the High-End Household P1.29 LED Display Market
Market Overview: Trajectory and Scale
The high-end household P1.29 LED display sector has entered a phase of sustained expansion, driven by a convergence of premium content consumption, architectural integration, and technological maturation. Between 2020 and 2025, revenue climbed from 163.15 million USD to an estimated 215.0 million USD, reflecting a compound annual growth rate of 7.8 percent over the broader 2020 to 2032 horizon. This trajectory points toward a market surpassing 360 million USD by the end of the decade, as fine-pitch LED panels transition from commercial and institutional deployments into luxury residential and high-performance entertainment environments.
The P1.29 pixel pitch specification occupies a strategic middle ground in the fine-pitch spectrum. It delivers resolution and contrast levels that rival traditional premium display architectures while preserving the modularity, brightness headroom, and longevity associated with LED technology. Growth has been particularly pronounced in the 55 to 65 inch and above 65 inch segments, where consumers and enterprise buyers alike are prioritizing immersive viewing surfaces over compact consumer electronics form factors. Flat panels continue to anchor the display type mix, but curved and transparent variants are gaining traction in premium interiors where design integration and spatial awareness matter as much as picture quality. On the technology front, OLED remains a benchmark for contrast and response, yet quantum dot enhancement, mini LED backlighting architectures, and emerging micro LED approaches are reshaping expectations around color accuracy, HDR performance, and energy efficiency.
Market concentration reflects a mature but still evolving competitive arena. The top three players account for roughly 45 percent of revenue, while the top five reach approximately 60 percent. This distribution suggests a landscape where established display manufacturers and specialized fine-pitch LED specialists coexist, but it also indicates room for asymmetric moves in product ecosystems, channel partnerships, and regional differentiation.
For decision makers, the headline takeaway is that premium home LED is no longer a niche experiment. It is a growing, multi-segment category where value creation depends on aligning pixel architecture, processing capability, ecosystem integration, and cost discipline. The companies that win will be those that treat P1.29 displays not merely as screens, but as integrated components of residential entertainment, ambient media, and premium interior experiences.
Critical Challenges and Inflection Points
Despite favorable momentum, the market faces several structural tensions that will define competitive outcomes over the next few years. The first is component and supply chain timing. High-brightness SMD LEDs used in P1.29 panels rely on precision manufacturing and specialized material inputs. Premium components can experience lead times extending to 12 to 18 weeks, creating planning friction for product launches, channel replenishment, and large residential projects. In an environment where pricing visibility and delivery reliability increasingly influence buyer selection, these timing constraints can erode margin flexibility and constrain responsiveness to demand shifts.
The second challenge revolves around input cost volatility and labor intensity. Advanced surface-mount technology assembly for P1.29 modules commands hourly labor rates significantly above baseline in precision electronics facilities, reflecting the skill requirements and quality controls needed for fine-pitch production. At the same time, critical mineral sourcing for gallium and indium in RGB LED chips has shown quarterly cost fluctuations of up to 15 percent. This combination of specialized labor pricing and raw material volatility creates a cost structure that is difficult to compress purely through scale. Manufacturers must therefore manage cost through design efficiency, yield improvement, supplier diversification, and selective technology substitution rather than relying on commodity-style procurement advantages.
A third inflection point is regulatory and standards-driven safety compliance. LED displays exceeding 1000 nits brightness must meet IEC 62471 photobiological safety requirements for residential installation. As high-brightness P1.29 panels move from controlled commercial settings into living spaces, compliance becomes a gating factor for product acceptance, installer confidence, and liability management. This is not a barrier that eliminates opportunity; rather, it shifts value toward firms that can embed safety, thermal management, and installation guidance into their product and service narratives from the outset.
A fourth pressure point is geopolitical and tariff exposure. Import costs for Chinese-origin fine-pitch LED modules and panels can be impacted by US tariffs ranging from 10 to 25 percent. For P1.29 household displays, where margin structures are already shaped by premium specifications and complex manufacturing, tariff exposure can meaningfully alter landed cost, pricing strategy, and the relative competitiveness of regional sourcing models. Companies that treat trade policy as a static assumption rather than a planning variable risk underpricing, margin compression, or disrupted channel economics.
Together, these challenges point to a central reality: the P1.29 household display market rewards operational resilience and ecosystem maturity at least as much as product specifications. The inflection point is not whether fine-pitch LED belongs in premium homes, but which firms can produce, deliver, and support it reliably under cost and compliance pressure.
Key Demand Drivers
Technology innovation and integration depth are among the strongest demand catalysts. Recent cooperative moves between major consumer display organizations and professional processing specialists illustrate the shift toward integrated home display ecosystems. For example, a 2025 partnership between Samsung Electronics and Barco focused on co-developing high-end LED home display ecosystems, combining Samsung's consumer microLED direction with Barco's processing capabilities for luxury residential applications. This signals a broader industry realization that pixel pitch alone does not win premium households; processing, calibration, content compatibility, and installation reliability are equally decisive. Product-level responses reinforce the same theme. In mid-2025, LG Electronics introduced a 29-inch MicroLED-based home display designed for premium home theater setups, emphasizing advanced sub-pixel drive and enhanced HDR performance. Even at smaller screen sizes, manufacturers are pursuing high-end differentiation through drive engineering and color performance, not just panel size or resolution alone.
Competitor consolidation around driver and interface technology is also reshaping the innovation frontier. Sharp's 2024 acquisition of a microLED driver technology firm was aimed at accelerating compact, high-brightness LED panels for luxury residential displays and improving color accuracy at small pixel pitches. Driver architecture has become a strategic asset because it influences brightness uniformity, thermal behavior, signal integrity, and the ability to scale fine-pitch designs without sacrificing yield. As leading firms absorb or partner for these capabilities, the differentiation gap between pure panel assembly and full-system competence widens.
Small Pitch LED Display Market
Policy and regulatory conditions are shaping adoption patterns in ways that go beyond compliance. Safety standards for high-brightness displays and trade policy on imported modules are creating uneven cost and risk environments across regions. In practice, this encourages regional sourcing strategies, localized assembly where feasible, and product designs that can be certified for multiple regulatory contexts. It also increases the importance of documentation, installer training, and after-sale support, especially for premium residential projects where buyers and integrators expect end-to-end assurance rather than component-level performance claims.
On the demand side, consumer and enterprise behavior is shifting toward experiential and multi-use display environments. Home theater is a core application profile, reflecting the desire for cinematic image quality within private spaces. Gaming is another significant driver, as enthusiasts seek high refresh behavior, low latency, and large immersive surfaces that complement high-performance systems. Corporate presentations and digital signage also contribute to demand, though their role in the household category is more about crossover value: the same fine-pitch technologies used in professional interiors are increasingly influencing premium home expectations for color consistency, brightness stability, and modularity. What ties these applications together is that they reward accuracy, uniformity, and ecosystem readiness more than sheer size increments. Buyers are increasingly comparing fine-pitch LED against alternative premium display technologies on total experience, not just spec sheets.
Supply chain and cost structure changes are a fourth driver, but they operate differently from traditional volume-led cost reduction. P1.29 production depends on precision assembly, tight quality tolerances, and specialized component availability. As a result, competitive advantage is increasingly derived from yield optimization, process consistency, component selection, and supplier relationships that reduce exposure to long lead times and cost swings. Firms that can stabilize throughput while maintaining high-brightness performance and color consistency will be better positioned to offer predictable pricing and dependable delivery, both of which matter for premium residential projects and repeat enterprise deployments.
The strategic implication is that demand is being pulled not only by larger screens, but by better-integrated ones. buyers want displays that fit into residential design, comply with safety expectations, perform consistently under HDR and gaming workloads, and arrive with reliable support. That combination elevates the importance of product architecture, processing partnerships, manufacturing discipline, and regional cost management.
Competitive Landscape and Leading Strategies
The competitive field includes organizations with very different strategic centers of gravity. Samsung Display and LG Display operate from major South Korean electronics ecosystems and emphasize premium high-resolution LED panels and advanced OLED and LED technologies for high-end household video displays. Their advantage is often rooted in scale, system integration, and the ability to connect display hardware with broader consumer electronics and content ecosystems. Panasonic Corporation contributes a distinct angle through professional and household LED display solutions, including all-in-one systems that reduce integration complexity for end users and installers. Sharp Corporation brings attention to microLED driver technology and compact high-brightness LED panels for luxury residential applications, with a focus on precision and color behavior at small pixel pitches. Barco, based in Belgium, stands out for its emphasis on X1.2 series LED video walls with 1.29 mm pixel pitch for high-performance indoor installations, positioning around processing, installation reliability, and professional-grade performance characteristics.
A second cluster includes specialized fine-pitch LED manufacturers based in Shenzhen, Beijing, and other technology hubs. AOTO Electronics focuses on premium fine-pitch COB LED displays for high-end residential and cinema applications. Liantronics emphasizes fine-pitch and high-resolution LED screens for premium indoor household use. Absen targets small-pitch LED displays, including P1.29 mm series options for high-end residential installations. Leyard concentrates on fine-pitch LED video walls and residential display solutions. Unilumin focuses on professional LED displays with small-pitch options for household high-end applications. AVMS, in Germany, contributes high-resolution 1.29 mm GOB LED modules and indoor display systems for premium household installations. These firms often compete on modularity, pitch precision, customization, regional serviceability, and the ability to tailor products to specific interior and installation requirements.
The differentiating question is not simply who makes the smallest pitch or the brightest panel. It is who can manage the full stack most effectively. Leading strategies tend to fall into several patterns. One is ecosystem integration: combining panel hardware with processing, calibration, and installation support so that the display arrives as a usable premium solution rather than a component. Another is technology specialization: building advantage around driver architecture, GOB or COB module design, sub-pixel drive, or compact high-brightness implementations that improve color accuracy and uniformity at fine pitches. A third is regional and channel positioning: aligning manufacturing footprint, certification readiness, and distribution relationships to reduce tariff exposure, shorten delivery paths, and strengthen installer trust. A fourth is application targeting: designing product lines for specific use cases such as home theater, luxury interiors, or high-performance indoor installations where brightness, HDR behavior, and viewing distance requirements differ.
The market landscape is evolving through both consolidation and differentiation. Recent partnerships and acquisitions indicate that firms are seeking capabilities that extend beyond panel fabrication. The trend toward co-developed ecosystems, driver technology absorption, and specialized module design suggests that vertical depth is becoming a competitive necessity in the premium segment. At the same time, the presence of multiple specialists indicates that differentiation by application, region, and installation model remains viable. New entrants can still compete if they bring a credible combination of fine-pitch precision, ecosystem readiness, and dependable delivery, but head-to-head competition on price alone is increasingly difficult given labor intensity, component lead times, and compliance costs.
For buyers and investors, the practical conclusion is that market leadership is increasingly defined by reliability and integration rather than headline specifications. A strong P1.29 strategy now involves a clear answer to how the product will be manufactured consistently, certified for residential use, supported through installation, and positioned against tariff and sourcing risks.
Future Outlook: Three Strategic Trends
One major trend over the next three to five years is the deepening of integrated home display ecosystems. As premium residential deployments grow, the value of standalone panels will increasingly be judged against full solution quality: processing, calibration, compatibility, installer support, and long-term serviceability. This favors organizations that can coordinate hardware, software-adjacent processing, and installation workflows into a coherent offering. The opportunity lies in owning a more complete experience pathway, especially in high-value residential projects where buyers and integrators prioritize dependable outcomes over isolated performance claims. The risk is that integration expands scope and cost, requiring disciplined execution and strong partnership models where internal capability is incomplete.
A second trend is continued coexistence and selective convergence between fine-pitch LED and alternative premium display technologies. OLED, quantum dot, mini LED, and micro LED approaches will continue to compete for attention in the premium household category, each with strengths in contrast, color volume, brightness headroom, or form factor. Rather than a single winner, the market is likely to segment by use case and buyer priorities. Some environments will favor LED for brightness robustness and modular scalability, while others will lean toward competing technologies for specific visual characteristics. The commercial opportunity here is in positioning P1.29 products with a clear, defensible advantage for particular applications and design requirements rather than attempting to win every premium use case with a single architecture. The uncertainty is that technological progress in competing categories could shift purchase criteria faster than product cycles can adapt, especially if HDR, color accuracy, and energy performance continue to improve across technologies.
A third trend is the growing importance of regional cost and compliance strategy. Tariff exposure, raw material volatility, labor intensity, and safety standards will continue to shape where and how P1.29 products are sourced, assembled, certified, and delivered. Companies that design regional flexibility into their supply and distribution models are more likely to maintain pricing stability and market access across jurisdictions. The opportunity is to build repeatable compliance and sourcing frameworks that reduce surprise costs and accelerate project execution. The risk is that trade and input cost conditions may shift in ways that disrupt assumptions built into pricing, margin planning, and regional roadmaps, especially for firms with concentrated sourcing exposure.
LED Display Market
These trends point to a market where durable advantage will come from consistency, integration, and adaptive sourcing rather than from short-lived specification leadership alone.
Actionable Guidance for Decision Makers
For manufacturers, the strategic priority is to strengthen the full product and delivery chain behind the P1.29 specification. That means investing in yield, process consistency, driver and module design, safety and compliance readiness, and supply relationships that reduce exposure to long lead times and cost volatility. Product differentiation should be tied to application outcomes, whether that is superior HDR behavior for home theater, reliable brightness uniformity for luxury interiors, or modular installation advantages for premium indoor projects. Firms that can demonstrate dependable production performance and installation confidence will be better positioned to defend pricing and win premium projects even when competition intensifies.
For investors, the emphasis should be on capability depth rather than headline unit growth alone. Organizations with strong integration strategies, credible compliance management, resilient sourcing, and clear differentiation in targeted applications are more likely to sustain margins and market access. It is equally important to assess exposure to tariff-gated cost structures and raw material volatility, since these factors can influence not only profitability but also the competitiveness of specific geographies and channel models. The most attractive opportunities are likely to be found where technology positioning, service reliability, and regional strategy reinforce one another.
For procurement and channel decision makers, the priority is to evaluate P1.29 offerings on total project value rather than panel-level specifications alone. This includes assessing certification and safety readiness for residential use, installation support, component availability, delivery reliability, and the expected lifecycle of processing and driver performance. Preference should tilt toward suppliers that can reduce integration risk and provide predictable outcomes, particularly in high-value residential projects where installation quality and long-term performance are as important as initial image quality. Clear visibility into sourcing, compliance, and support expectations will help reduce downstream disruption.
PW Consulting
The premium household P1.29 LED display market is moving from early adoption to structured competition, and the pace of change in integration, cost exposure, and application targeting makes detailed intelligence increasingly valuable. For decision makers who need granular segment data, regional cost modeling, competitive benchmarking, and scenario analysis across the 2026 to 2032 horizon, the full PW Consulting research report provides deeper segmentation detail, company-level context, and tailored strategic recommendations to support board-level planning and investment decisions.
For detailed analysis of this topic, please visit the official page: High-end Household P1.29 LED Display Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Articulated Robot Market: Why Asia Pacific, Handling, and 15.58% CAGR Fueled $59.5B Growth Beyond 2032
By pmarketresearch, 2026-09-21
Navigating the Articulated Robot Market: Strategic Trends and Commercial Opportunities (2026–2032)
1. Market Overview and Core Challenges
The articulated robot market has entered a period of accelerated expansion, driven by a convergence of technological maturity, shifting industrial priorities, and broad-based automation demand. From a base valuation of approximately 9.86 billion in 2020, the market has consistently expanded year over year, reaching an estimated 17.88 billion in 2024 and climbing to 21.59 billion in 2025. This trajectory reflects sustained capital allocation toward robotic automation across manufacturing, logistics, and emerging industrial applications. The forward curve projects continued momentum, with revenues expected to breach 25.64 billion in 2026, approach 32.76 billion by 2028, and surpass 59.47 billion by 2032. Underlying this growth is a compound annual growth rate of roughly 15.58 percent through the forecast period, signaling that articulated robotics are transitioning from specialized industrial tools to mainstream operational infrastructure.
Such rapid expansion, however, does not occur in a vacuum. The market is navigating several structural friction points that will shape competitive positioning and investment returns over the next several years.
Geopolitical and trade volatility has emerged as a recurring disruptor. Supply chain realignments, tariff uncertainties, and cross-border component restrictions have introduced variability into procurement cycles and pricing models. These dynamics affect not only end-user deployment timelines but also manufacturers' ability to scale production consistently across regions. Companies that rely on concentrated sourcing or single-region assembly footprints are facing heightened exposure, while those with diversified manufacturing networks are better positioned to absorb shocks.
Safety and interoperability standardization is undergoing simultaneous revision. Updated collaborative robot safety frameworks have introduced stricter speed thresholds for accessible moving components, altering deployment parameters in mixed human-robot workcells. At the same time, broader robotics standards bodies continue refining performance and safety guidelines for articulated industrial systems. While these updates strengthen operational safety and long-term reliability, they also create near-term compliance complexity. Manufacturers and system integrators must invest in updated validation processes, revise risk assessments, and adjust programming practices to remain aligned with evolving requirements.
Payload-versus-flexibility trade-offs continue to influence adoption patterns. Articulated robots are increasingly expected to handle diverse tasks without sacrificing reach, precision, or cycle time. As applications expand across material handling, welding, assembly, and processing, buyers are weighing whether to standardize on fewer high-capability models or maintain broader model portfolios tailored to specific workflows. This tension is reshaping product roadmaps and encouraging manufacturers to design platforms that offer modular end-effector compatibility, programmable grasp strategies, and easier redeployment across lines.
2. Key Drivers Shaping Market Trajectory
Technological Innovation and Capability Expansion
Advances in control architecture, sensor integration, and software-defined motion planning are expanding what articulated robots can accomplish within a single cell. Modern systems increasingly combine higher repeatability with adaptive path correction, enabling more consistent performance in environments where part variation or fixture tolerances previously required manual intervention. Heavy-payload platforms are also benefiting from structural optimization and improved actuator design, allowing manufacturers to handle larger workpieces without proportionally increasing footprint or energy consumption. These improvements reduce the total cost of ownership for high-throughput operations and broaden the range of applications where articulated arms can replace dedicated single-purpose machinery.
A notable example of capability-led expansion is the recent refinement of heavy-payload articulated series, which now offer substantially higher wrist-down capacity and extended reach variants. Such updates directly address sectors like automotive final assembly, heavy fabrication, and large-component material handling, where payload margins and orientation flexibility previously constrained automation coverage. Simultaneously, collaborative articulated platforms are gaining traction in small-to-medium batch environments, where safe proximity operation and quick reprogramming deliver value in setups that cannot justify traditional caged automation. Product introductions targeting small-to-medium manufacturing in high-growth regions further illustrate how capability refinement is unlocking new deployment clusters.
Policy Environment and Standardization Shifts
Regulatory and standards activity is shaping both procurement decisions and engineering practices. New collaborative safety specifications have established reduced speed limits for accessible moving parts, prompting system designers to reconsider layout geometry, safeguarding strategies, and cycle-time expectations in shared workspaces. Alongside these developments, ongoing revisions to industrial robot safety and performance standards are pushing manufacturers toward more transparent validation documentation and more consistent interoperability expectations.
For enterprises, these shifts carry dual implications. On one hand, tighter standardization reduces risk and improves long-term operational consistency, particularly in facilities where regulatory oversight or labor safety requirements are stringent. On the other hand, compliance preparation requires upfront engineering and validation effort. Organizations that integrate safety-by-design thinking early in the selection and integration phase can mitigate retrofit costs later, while those that treat compliance as an afterthought may face deployment delays or rework when standards are formally adopted into procurement specifications.
Demand-Side Behavior and Deployment Patterns
End-user behavior is increasingly favoring flexible automation over fixed, single-purpose lines. Manufacturers facing variable order volumes, shorter product lifecycles, and labor availability constraints are seeking robotic solutions that can be redeployed or reprogrammed without extensive line reconstruction. This preference is particularly pronounced in sectors where batch sizes are shrinking and changeover frequency is rising. Articulated robots positioned as adaptable workcell components—rather than rigidly dedicated machines—are aligning with this demand profile.
Regional deployment concentration is also influencing demand momentum. Recent global installation data indicates that Asia continues to account for a substantial share of new robot deployments, reflecting both large-scale manufacturing capacity and rapid automation adoption across multiple industrial segments. This concentration reinforces supplier focus on region-specific requirements, including payload profiles, duty cycles, and integration support models. At the same time, sustained installation volumes worldwide demonstrate that articulated robotics are no longer confined to a narrow set of high-volume industries; they are increasingly embedded across diversified manufacturing, assembly, and processing environments.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by component availability, regional manufacturing footprints, and the growing influence of software on hardware value. While actuator, gear, and structural component costs remain relevant, the competitive advantage is increasingly determined by integration readiness, programming ease, and post-deployment support. Systems that reduce commissioning time, simplify operator training, and enable quicker changeovers can offset higher upfront hardware costs through faster ramp-up and lower disruption during transitions.
Trade disruptions and component sourcing variability have also heightened interest in supply chain resilience. Buyers and manufacturers alike are placing greater weight on multi-region production capability, documented quality controls, and predictable lead times. As a result, suppliers that can demonstrate consistent delivery performance and localized support are gaining preference in procurement evaluations, even when alternatives appear cheaper on a unit-cost basis. This shift is gradually elevating the importance of service networks, spare-part availability, and technical response times as decisive commercial factors.
3. Competitive Landscape and Leading Strategies
The articulated robot market remains moderately concentrated, with the top three vendors holding a combined share above half of total revenue and the top five extending past sixty percent. This concentration reflects the technical barriers associated with high-reliability industrial robotics, established integration ecosystems, and long customer relationships in sectors where downtime costs and safety requirements make vendor switching a measured decision. Yet within this structure, differentiation is increasingly driven by application specialization, software-enabled value, and regional execution rather than headline scale alone.
Established industrial leadership continues to rest on broad application coverage, heavy-duty reliability, and deep integration experience. Leading suppliers maintain strong positions across welding, material handling, assembly, and precision machining by offering mature six-axis platforms, extensive field validation, and well-developed service networks. Their advantage lies in the ability to support demanding duty cycles, maintain consistent performance across large installed bases, and provide engineering support for complex multi-robot or line-integrated deployments.
Differentiation through payload and software is becoming more pronounced. Heavy-payload specialists are pushing capability boundaries with higher wrist-down variants and advanced digital tooling, targeting applications where large workpieces and coordinated motion require both structural strength and sophisticated control. At the same time, manufacturers are layering predictive maintenance, motion optimization, and remote diagnostics into their platforms, transforming standalone hardware into continuously monitored operational assets. This software-oriented shift is particularly relevant for operators seeking to standardize across multiple cells while retaining visibility into performance trends and maintenance needs.
Collaborative and flexible-production playbooks represent a distinct strategic lane. Collaborative articulated platforms are positioned around safe proximity operation, simplified redeployment, and accessibility for smaller batch production. Their commercial appeal rests on lowering barriers to automation in environments where traditional caged systems are impractical or where production variability discourages large fixed investments. By emphasizing quick programming, safe interaction, and adaptable use cases, these platforms extend articulated robotics into workcells that previously relied on manual operation or limited semi-automated tooling.
Regional execution and targeted product updates are shaping near-term momentum. Suppliers are refining model lineups for specific market needs, introducing variants that balance payload, reach, and general-purpose manufacturing flexibility. Targeted launches and catalog updates in high-growth regions reflect an emphasis on matching product specifications to local duty cycles, integration practices, and application mixes. Rather than relying solely on global platform uniformity, leading companies are increasingly calibrating their portfolios to regional demand rhythms while preserving core technological consistency.
The landscape is evolving along multiple axes. Consolidation pressure persists where scale benefits procurement, distribution, and service coverage. At the same time, segmentation is intensifying as manufacturers distinguish themselves through payload class, collaborative capability, software integration, and application-focused support. New entrants and niche specialists are carving roles in particular payload ranges, collaborative safety configurations, or industry-specific tooling ecosystems. For buyers, this means vendor selection is less about identifying a single dominant name and more about aligning platform strengths with the operational profile of the intended deployment.
4. Forward Outlook: Trends and Commercial Implications (2026–2032)
Trend 1: Broader Application Diffusion Beyond Traditional Heavy Industry
Articulated robots are steadily moving beyond concentrated use in a few high-volume sectors. Their adoption is expanding into diversified assembly, processing, and handling environments where flexibility, repeatability, and redeployment capability matter more than extreme specialization. As programming environments become more accessible and end-effector options broaden, the friction associated with introducing articulated arms into new workflows is declining. Commercial opportunity lies in workcell designs that prioritize modularity, quick changeover, and cross-application reuse rather than single-purpose optimization. Operators that structure automation around reusable robotic cores can reduce the cost of adapting to new products or revised processes.
A related risk is overgeneralization. Not every application benefits from a standard articulated platform, and improper selection can erode the efficiency gains that justify automation in the first place. Success will depend on matching payload class, reach, cycle-time expectations, and safety configuration to the specific task profile, rather than assuming broader adoption automatically translates into uniform returns.
Trend 2: Software, Data, and Service as Differentiators
As hardware performance converges across capable suppliers, the competitive edge is migrating toward software tooling, data utilization, and service responsiveness. Platforms that offer clearer programming workflows, coordinated multi-axis optimization, and remote monitoring can shorten commissioning and improve ongoing uptime. For operators, this shift creates value in reduced changeover disruption, earlier detection of performance drift, and more predictable maintenance scheduling. For suppliers, it opens recurring value streams through diagnostics, updates, and application support that extend beyond the initial sale.
Robotics Market
Commercial implications are significant for buyers evaluating total cost of ownership. A system with slightly higher upfront cost may deliver stronger returns if it reduces engineering hours, accelerates line ramp-up, or lowers unscheduled downtime. The risk lies in underestimating integration effort or assuming software capabilities without verifying them against real deployment conditions. Validation should extend beyond spec sheets to include commissioning timelines, operator training requirements, and support-response expectations.
PW Consulting Automotive & Machinery Research Center
Trend 3: Regional Demand Rhythms and Supply Chain Resilience
Demand growth will continue to be shaped by regional manufacturing intensity, automation maturity, and supply chain configuration. Areas with dense production ecosystems and rapid automation adoption will remain major deployment centers, while other regions will expand at different paces depending on labor dynamics, capital availability, and sector mix. Suppliers with resilient manufacturing footprints, predictable lead times, and localized support are likely to capture preference in environments where deployment continuity matters as much as unit performance.
The commercial opportunity here is twofold. Manufacturers that can match product availability to regional demand cycles while maintaining consistent quality will strengthen procurement credibility. Buyers that diversify supplier options, verify regional service coverage, and plan for component or lead-time variability will reduce exposure to deployment interruptions. The principal uncertainty is the duration and intensity of trade and sourcing disruptions, which can alter pricing, timing, and regional availability without warning. Planning around flexibility—both in supplier selection and in deployment architecture—offers a practical buffer.
5. Strategic Actions for Decision Makers
The next phase of market growth will reward organizations that treat articulated robotics as a strategic operational capability rather than a point procurement decision. Action priorities differ by role, but all benefit from clearer evaluation criteria and earlier integration of safety, flexibility, and support considerations.
- For manufacturers and operations leaders: Prioritize workcell designs that balance payload needs with redeployment flexibility. Evaluate platforms based on total deployment cost, including commissioning time, operator training, changeover complexity, and service responsiveness, rather than unit price alone. Build selection criteria around the specific duty cycle, safety configuration, and application mix of each site, and validate software and integration claims through pilot conditions before scaling.
- For investors and corporate development teams: Focus on suppliers demonstrating durable differentiation through software-enabled value, service coverage, and resilient manufacturing execution. Assess whether product roadmaps align with broadening application diffusion and whether the company can sustain regional delivery credibility amid sourcing variability. Consider the extent to which recurring support and digital services can stabilize revenue quality as hardware competition intensifies.
- For procurement and automation buyers: Treat safety and interoperability updates as design inputs rather than late-stage compliance checks. Ensure that collaborative speed thresholds, safeguarding layouts, and validation requirements are incorporated early in concept planning. Where possible, structure multi-vendor evaluations to compare not only technical specifications but also integration support, spare-part availability, and regional service coverage, since these factors increasingly shape long-term operating performance.
The articulated robot market is expanding at a pace that rewards early clarity and disciplined evaluation. Demand is spreading across more applications, safety and standards expectations are tightening, and competitive advantage is shifting toward flexibility, software, and execution reliability. Organizations that align their automation strategy with these dynamics will be better positioned to capture productivity gains without inheriting avoidable integration or compliance risk.
Worldwide Small Articulated Loader Market
For decision makers seeking deeper segmentation detail, workload-specific deployment patterns, regional demand nuances, and vendor-specific capability comparisons, comprehensive research covering the full forecast horizon is available through PW Consulting's complete market report. The full study provides extended breakdowns and customized analysis to support more precise planning across manufacturing, investment, and procurement use cases.
For detailed analysis of this topic, please visit the official page: Articulated Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com