

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Healthcare RCM Outsourcing Market: Why 11.4% CAGR and $78B Scale Signal Strategic Shifts

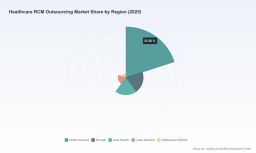
Healthcare RCM Outsourcing Market: Strategic Trends and Commercial Opportunities 2026–2032
The global healthcare revenue cycle management (RCM) outsourcing market has reached a critical inflection point. Valued at approximately $36.7 billion in 2025, the market is projected to advance to $78.1 billion by 2032, reflecting a compound annual growth rate of 11.4 percent over the forecast period. This trajectory marks a significant acceleration from the historical expansion observed between 2020 and 2025, when the market grew from $21.4 billion to its current scale. The pace of change is no longer driven solely by gradual administrative outsourcing; it is being reshaped by structural cost pressures, regulatory complexity, and the rapid infusion of artificial intelligence into revenue cycle operations. For executives, investors, and healthcare operators, the question has shifted from whether to outsource RCM functions to how to architect partnerships that deliver measurable financial resilience and operational agility.
Understanding the current market landscape requires acknowledging both the scale of opportunity and the friction points that define today's operating environment. Providers across hospitals, clinics, and ambulatory surgery centers are navigating rising denial rates, persistent labor constraints, and evolving reimbursement frameworks. At the same time, payers and regulators are pushing for greater transparency, faster prior authorization decisions, and standardized interoperability. These forces are compressing margins and lengthening the path to clean claims, which in turn is driving a broader reevaluation of how revenue cycle work is staffed, automated, and managed. The market is large enough to absorb diverse service models, yet fragmented enough that strategic positioning matters more than ever. Organizations that treat outsourcing as a purely transactional cost-cutting exercise risk missing the deeper operational transformation that forward-looking partnerships now enable.
Three structural challenges define the current market and signal where strategic attention should be directed. First, denial volumes and rework costs continue to rise, undermining cash flow predictability for many provider organizations. Even as technology adoption increases, the complexity of payer rules, medical necessity reviews, and coding specificity means that manual intervention remains a significant cost driver. Second, labor availability and cost dynamics are reshaping the economics of in-house revenue cycle teams. Recruitment delays, wage inflation, and turnover create execution risk for providers trying to maintain full internal control over billing, coding, and patient access functions. Third, regulatory momentum around interoperability and prior authorization is changing the compliance bar. Providers must adapt to new data exchange expectations and administrative simplification mandates, which introduces both opportunity and implementation risk depending on the maturity of their existing systems and processes.
These challenges are not isolated; they interact. Higher denial rates increase the workload required to sustain revenue integrity. Staffing shortages make it harder to absorb that workload without bottlenecking cash flow. Regulatory changes add new procedural requirements at a moment when teams are already stretched. The practical implication is that the market is rewarding providers who can combine scale, technology, and specialized expertise rather than those who simply seek the lowest unit cost for administrative services. That shift is visible in the types of partnerships being announced and the capabilities providers are prioritizing.
Healthcare Regulatory Affairs Outsourcing Market
Key Drivers Behind Market Acceleration
Technology Innovation and the Rise of Agentic Automation
The most consequential driver in the RCM outsourcing market is the transition from basic automation to agentic, context-aware systems that can support denial prevention, prior authorization, coding, and accounts receivable optimization within a managed services environment. This is not merely a software upgrade cycle. It reflects a structural change in what outsourcing can deliver. Providers increasingly expect partners to bring not only labor but also intelligent workflows that reduce manual rework, shorten cycle times, and improve first-pass acceptance rates.
Recent industry activity underscores this shift. R1 RCM expanded its innovation focus through its R37 lab by partnering with Palantir Technologies to operationalize AI data innovation and agentic applications for revenue cycle transformation. In parallel, R1 RCM announced an agreement to acquire Phare Health, an AI platform focused on automating inpatient coding and pre-bill clinical documentation improvement, with the Phare Health team joining the R37 innovation lab. These moves illustrate how leading outsourcing providers are embedding technology development directly into their service models rather than treating automation as a bolt-on feature.
Ensemble Health Partners has taken a similar direction by launching an agentic AI platform developed in partnership with Cohere for RCM-native language model capabilities, supporting autonomous coding and frictionless revenue cycle operations. Waystar has advanced its cloud-based platform with Google Cloud to accelerate autonomous revenue cycle capabilities, including denial prevention and recovery. These developments matter because they show a market moving toward platforms that can handle complex judgment-based tasks with less human intervention, while still fitting within managed services contracts. The commercial value is clear: when AI-driven workflows reduce denial leakage and rework, the economics of outsourcing become more attractive relative to the cost of maintaining fragmented internal operations.
Regulatory and Reimbursement Pressure as a Demand Catalyst
Policy and reimbursement dynamics are reinforcing demand for outsourced RCM support. Regulatory attention on interoperability and prior authorization has raised the compliance and administrative burden for providers, particularly those managing Medicare Advantage and managed care relationships. R1 RCM, for example, has submitted comments to the Centers for Medicare & Medicaid Services on proposed rules related to advancing interoperability and improving prior authorization processes. These regulatory conversations are not abstract; they influence how quickly claims move, how much documentation is required, and how much administrative effort is needed to secure timely payment.
On the reimbursement side, uncertainty around payment rules and evolving prior authorization expectations has increased the operational complexity of revenue cycle management. Providers must be able to track changing requirements, adapt workflows, and minimize avoidable denials without expanding internal headcount indefinitely. For many organizations, that combination is a practical argument for outsourcing models that can spread regulatory adaptation costs across a broader client base and apply specialized expertise to payer-specific rules. The market response has been consistent: a meaningful share of providers are actively exploring outsourcing options for RCM tasks, including remittance advice standards and other administrative functions, while others have already moved portions of their revenue cycle work externally.
Cost Structure Pressures and Staffing Realities
Cost structure and labor dynamics remain central to the outsourcing thesis. More than 60 percent of providers are considering outsourcing RCM to address staffing shortages, inflation, and rising denials, according to recent sector analysis. That figure reflects a practical response to a difficult operating environment rather than a philosophical preference for outsourcing. When labor markets are tight and wage pressure is persistent, the fully loaded cost of an internal revenue cycle team rises faster than many providers can offset through productivity gains alone.
PW Consulting Health Care Research Center
Outsourcing offers a different cost profile. It can convert fixed labor expense into variable or service-based pricing, align capacity with volume fluctuations, and provide access to specialized skills that are expensive to recruit and retain in-house. More importantly, outsourcing partners with strong technology backbones can improve throughput and reduce error rates in ways that are difficult to replicate with staff alone. The most attractive engagements today are those that combine cost discipline with measurable performance outcomes, such as lower days in accounts receivable, improved clean claim rates, and reduced denial write-offs.
Provider Demand for End-to-End Managed Services
Demand-side behavior is shifting toward broader, more integrated outsourcing relationships. Rather than outsourcing isolated functions, providers are increasingly looking for end-to-end managed services that span patient access, patient encounter processing, and patient billing within a unified operating model. This preference is driven by the desire to reduce handoff friction, standardize data flow, and improve accountability across the revenue cycle. When responsibilities are split across multiple vendors or internal departments, coordination costs and blind spots can erode the benefits of any single technology or process improvement.
This trend is reinforced by the growing complexity of patient financial interactions. As patients take on more cost-sharing responsibility and access models expand across virtual care, outpatient settings, and ambulatory surgery centers, providers need revenue cycle processes that can handle varied billing scenarios without sacrificing patient experience. Managed services models that integrate access, encounter, and billing functions can help organizations maintain consistency while scaling across multiple facilities or care settings. The result is a market that increasingly values integration, accountability, and performance visibility as much as raw processing capacity.
Competitive Landscape and Leading Strategies
The RCM outsourcing market is characterized by a mix of specialized managed services providers, technology-forward platforms, and large integrated players with payer connectivity and analytics capabilities. Market concentration remains moderate, with the top three firms accounting for roughly 29.5 percent of market revenue and the top five collectively representing about 36.2 percent. That structure leaves substantial room for differentiated positioning, regional strength, and vertical specialization, while also rewarding providers that can combine scale with credible technology and service integration.
R1 RCM has built a distinctive position around full-service managed revenue cycle outsourcing supported by AI-driven automation. Its R37 lab and Phare platform point toward inpatient coding and denial management as areas where technology can be tightly integrated into outsourcing delivery. The recent acquisition of Phare Health and the partnership with Palantir Technologies suggest a strategy focused on building proprietary innovation capacity while expanding agentic capabilities. This approach positions R1 RCM as a provider that wants to control more of the technology roadmap underlying its services, rather than relying entirely on third-party tools.
Conifer Health Solutions has emphasized multi-year enterprise revenue cycle outsourcing partnerships that deliver tech-enabled patient access, denial management, and accounts receivable optimization for hospitals and health systems. Its recent multi-year enterprise partnership with Healthcare Systems of America for multi-facility services reflects a strategy aimed at scaling long-term relationships across complex provider networks. The commercial logic is straightforward: enterprise engagements create deeper integration, more stable revenue streams, and opportunities to apply standardized processes across multiple facilities.
Ensemble Health Partners has focused on end-to-end managed services outsourcing with an agentic AI platform developed in partnership with Cohere. Its RCM-native language model emphasis and autonomous coding ambitions place it in a group of providers seeking to differentiate through automation that is purpose-built for revenue cycle work. This is a meaningful strategic signal because it suggests a shift from generic AI adoption to domain-specific models that can better handle coding logic, documentation review, and denial-related decision-making.
Waystar continues to advance its cloud-based software platform for end-to-end RCM outsourcing and managed services, with AltitudeAI agentic automation targeting denials, prior authorization, and recoupment. Its partnership with Google Cloud highlights a technology-centric pathway to autonomous revenue cycle capabilities. Waystar's positioning is relevant for providers looking for a platform-based model that can be paired with managed services, particularly when cloud scalability and AI-driven denial prevention are priorities.
GeBBS Healthcare Solutions offers AI-enabled revenue cycle outsourcing and managed services across billing, coding, patient access, and financial operations. Its breadth across core revenue cycle functions makes it a generalist-oriented player that competes on integration and service coverage. Optum, including its Change Healthcare assets, brings integrated revenue cycle management outsourcing and BPO solutions with payer connectivity, analytics, and technology. Its scale and cross-market presence give it a different kind of advantage: the ability to align provider-facing outsourcing with broader payer and health system relationships.
Other notable participants include TruBridge, which focuses on end-to-end revenue cycle management outsourcing and managed services with technology and staffing for community hospitals, rural facilities, and federally qualified health centers; Athenahealth, with an integrated EHR and revenue cycle management platform supporting physician practices and health systems; Nthrive, with managed revenue cycle services emphasizing outpatient and provider operations; The SSI Group, which provides revenue cycle outsourcing and managed services for hospitals and health systems; and MedAssets, part of Vizient, which delivers integrated revenue cycle management outsourcing and solutions through health system partnerships.
Healthcare BPO Market
The strategic common thread across these players is a move toward deeper service integration and stronger technology differentiation. Some providers are competing on scale, enterprise relationships, and payer connectivity. Others are competing on niche focus, such as rural and community hospital needs, outpatient operations, or inpatient coding and documentation. A third group is competing on AI-native workflows and agentic automation. This diversification is healthy for the market because it gives providers multiple entry points depending on their size, complexity, and technology maturity. It also suggests that the next phase of competition will be less about who offers outsourcing and more about who can demonstrate superior outcomes through a credible mix of staffing, automation, analytics, and integration.
Market evolution is likely to continue along two parallel paths. On one hand, consolidation may increase as larger players acquire niche capabilities, especially in AI, coding automation, and denial management. On the other hand, differentiation will persist because provider needs vary widely across academic medical centers, community hospitals, ambulatory surgery centers, and physician practices. New entrants with strong AI platforms or specialized managed services models can still carve out positions if they can prove measurable improvements in revenue integrity and operational efficiency. The most resilient providers will be those that can adapt their service architecture to different provider segments without losing focus on core performance metrics.
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to shape the market's next chapter. The first is the mainstreaming of agentic AI within managed revenue cycle services. As RCM-native models and automation workflows mature, providers will increasingly expect partners to prevent denials before submission, accelerate prior authorization decisions, and reduce rework in coding and billing. The commercial opportunity here lies in services that can tie automation directly to financial outcomes, not just process speed. Providers that can demonstrate lower denial rates, faster reimbursement, and reduced manual touchpoints will have stronger positioning in competitive evaluations.
The second trend is the continued shift toward integrated, end-to-end outsourcing models that span patient access, encounter, and billing functions. Fragmented service arrangements will face growing pressure as providers seek to reduce coordination complexity and improve data continuity. This creates opportunities for partners that can operate across the full revenue cycle while maintaining segment-specific expertise. It also creates opportunities for technology platforms that can unify data, reporting, and workflow across outsourced and internally managed functions where hybrid models remain necessary.
The third trend is the growing influence of regulatory and reimbursement reform on outsourcing demand. As prior authorization processes, interoperability expectations, and remittance standards evolve, providers will need partners that can adapt quickly and help manage compliance risk. The commercial opportunity is not simply in handling more transactions, but in helping providers navigate administrative change with less disruption to cash flow and patient experience. Organizations that can combine regulatory awareness with operational execution will be better placed to win long-term engagements.
These trends carry opportunity, but they also introduce risk. AI-driven automation can improve efficiency, yet it also raises questions about model accuracy, governance, and change management. If automation is deployed without strong oversight, providers may face new categories of coding or denial-related errors that offset expected gains. Regulatory changes can also shift the value of certain services over time, especially if prior authorization burdens are reduced or if payment models change in ways that alter revenue cycle complexity. Finally, the market's growth trajectory depends on providers' willingness and ability to restructure internal operations. Outsourcing adoption may be strong in principle, but execution risk remains where leadership, data readiness, and integration capacity are limited.
Strategic Considerations for Decision-Makers
For healthcare providers evaluating RCM outsourcing, the most important discipline is to define success in operational and financial terms before selecting a partner. engagements should be assessed against clear targets such as denial reduction, days in accounts receivable, clean claim performance, and patient access efficiency, rather than treated as generic cost-reduction projects. Providers should also determine which functions truly benefit from outsourcing versus which require retained internal control for clinical, strategic, or compliance reasons. A hybrid model can work well when the boundary between outsourced and internal responsibilities is deliberately designed and supported by shared data and reporting standards.
For investors and strategic observers, the market's growth trajectory is appealing, but the differentiation story is increasingly found in technology integration, enterprise relationship quality, and segment specialization. The most durable opportunities are likely to belong to providers that can demonstrate repeatable outcomes across multiple client environments and that can adapt their models as AI, regulation, and reimbursement structures evolve. Monitoring partnership announcements, platform launches, and acquisition activity can provide early signals about where capability is concentrating and where competitive advantage is being built.
For technology and service vendors participating in the broader revenue cycle ecosystem, the opportunity lies in aligning products and services with the way providers now evaluate outsourcing: as a combined package of staffing, automation, analytics, and accountability. Solutions that reduce handoff friction, improve denial visibility, and support payer-specific workflows are more likely to fit into enterprise engagements than point tools that address only one step in the cycle. In practice, vendors that can speak to both operational efficiency and revenue integrity will have an easier path into provider decision-making discussions.
The broader takeaway is that healthcare RCM outsourcing is no longer a back-office cost discussion. It is becoming a strategic lever for revenue predictability, administrative resilience, and technology-driven operational performance. Providers that treat it accordingly will be better positioned to manage denials, staffing constraints, and regulatory change without sacrificing financial control. Those that continue to view outsourcing narrowly may leave measurable value on the table as the market shifts toward more intelligent, integrated, and outcome-focused service models.
For decision-makers seeking a deeper breakdown of segment-level dynamics, regional nuances, and company-specific positioning, the full research report provides a more detailed look at the market structure, growth path, and strategic implications across the forecast period.
For detailed analysis of this topic, please visit the official page: Healthcare RCM Outsourcing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com