

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Hydraulic Accumulator Market: Why 5.6% CAGR and Asia Pacific's 97M Rise Through 2032

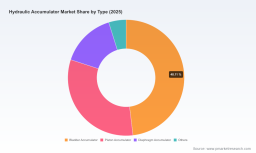
Hydraulic Accumulator Market: Strategic Trends and Commercial Opportunities Through 2032
The hydraulic accumulator market has entered a phase of measured, value-driven expansion, with the global market reaching an estimated 179.0 million USD in 2025 and projected to advance to 262.0 million USD by 2032, reflecting a compound annual growth rate of 5.6 percent. This trajectory, spanning historical growth from 130.0 million USD in 2020 through the post-pandemic recovery period, signals a market that has matured beyond cyclical swings and is now responding to structural shifts in industrial automation, equipment electrification, and fluid power system optimization. The headline numbers tell a story of steady compound growth, but the real strategic value lies in understanding where that growth is concentrated, which forces are reshaping competitive dynamics, and how operators can position themselves ahead of the next inflection point.
For executives and investors, the market presents a paradox: growth is broad-based yet uneven, volume is expanding but margin pressure is intensifying in segments exposed to raw material volatility, and regulatory frameworks are tightening even as commercial adoption accelerates in adjacent mobility and industrial applications. This article maps the current landscape, isolates the drivers reshaping demand and supply, examines how leading manufacturers are differentiating, and outlines the trends that will define competitive positioning over the next three to five years.
Market Snapshot and Structural Challenges
The market's evolution from 2020 to 2025 illustrates a compound trajectory shaped by both recovery and structural demand. After starting at 130.0 million USD in 2020, the market climbed through successive years, reaching 179.0 million USD in 2025. The forecast window through 2032 suggests continued expansion toward 262.0 million USD, with the pace of growth reflecting a blend of incremental adoption in established equipment categories and emerging pull from applications that leverage hydraulic energy storage for efficiency, shock absorption, and power smoothing.
Concentration and Competitive Fragmentation
Market structure remains moderately concentrated, with the top three players accounting for roughly 41.0 percent of revenue and the top five capturing approximately 45.0 percent. This concentration level indicates that while leading manufacturers hold meaningful share, the market retains room for regional specialists, application-focused suppliers, and new entrants targeting niche performance requirements. The fragmented long tail matters strategically because it means pricing power is not uniformly distributed, and competitive advantage increasingly depends on application expertise, certification portfolios, and service economics rather than scale alone.
Key Challenges and Inflection Points
- Raw material and component cost volatility: High-grade steel alloys and specialty elastomers used in accumulator shells and sealing systems have experienced price swings of 15 to 25 percent within a single year, directly influencing total cost of ownership and squeezing margins for manufacturers that cannot pass through input cost fluctuations or hedge procurement exposure.
- Regulatory compliance as a barrier and differentiator: Standards such as EN 14359 for gas-loaded accumulators, DIN EN ISO 4413 for hydraulic fluid power systems, and the Pressure Equipment Directive 2014/68/EU continue to govern design, safety, and pressure relief requirements. Compliance is no longer a checkbox; it is a competitive filter that raises the bar for new entrants and rewards incumbents with established certification infrastructure and testing capabilities.
- Shifting demand mix and application migration: Traditional reliance on construction and mobile hydraulics is being complemented by growth in machine tools, agriculture equipment, and adjacent automotive-related applications, creating a more complex demand profile that rewards manufacturers capable of serving multiple end-use segments with tailored architectures and sealing solutions.
Core Demand Drivers Reshaping the Market
The market's trajectory is not being pulled by a single force; it is being reoriented by a combination of technology, regulation, demand-side behavior, and cost structure dynamics. Each driver has distinctive implications for product roadmaps, go-to-market strategy, and investment timing.
PW Consulting Automotive & Machinery Research Center
Technology Innovation and System-Level Efficiency
Technological progress in hydraulic accumulators is increasingly focused on system-level benefits rather than component isolation. Innovations in bladder, piston, and diaphragm architectures are enabling better charge retention, faster response, and longer service life under demanding pressure cycles. Manufacturers are integrating advanced sealing materials, improved nitrogen pre-charge controls, and more robust shell designs to extend operational endurance and reduce maintenance frequency. These advances matter because they shift the value proposition from pure component replacement toward lifecycle efficiency, where lower downtime and extended service intervals can justify premium positioning.
Suppliers with in-house material capabilities and global certification portfolios are particularly well placed to accelerate these improvements, since material selection and sealing performance directly influence reliability under high-cycle conditions. The practical implication for buyers is that specification decisions increasingly hinge on documented endurance and compliance readiness rather than unit price alone.
Policy and Regulatory Environment
Regulatory frameworks are tightening in ways that both constrain and enable commercial activity. The sixteenth revision of DOT-SP 9998, granted in November 2025, authorized seamless steel hydraulic accumulators containing compressed nitrogen for commercial transportation. This development opens a pathway for accumulator use in transport-related hydraulic systems and signals a broader willingness to align safety frameworks with evolving application needs. At the same time, European standards such as EN 14359 and the Pressure Equipment Directive continue to require pressure relief devices and rigorous design controls, reinforcing a compliance-first market culture.
For manufacturers, the regulatory trend is twofold: it raises the cost of market entry for those without established testing and certification capabilities, and it creates a defensible moat for companies that can demonstrate conformance across multiple jurisdictions. For commercial transporters and equipment integrators, clearer authorization pathways reduce uncertainty and can accelerate adoption in fleets and mobile systems where hydraulic energy buffering offers measurable operational benefits.
Industrial Hydraulic Shock Absorber Market
Demand-Side Behavior and Equipment Modernization
End-use demand is being reshaped by equipment modernization cycles and the push for more efficient fluid power systems. Construction equipment remains a substantial application anchor, while machine tools and agriculture equipment contribute meaningful volume as manufacturers seek shock absorption, pressure compensation, and energy recovery features that improve machine stability and reduce wear. A smaller but strategically important share comes from automotive-adjacent applications, where hydraulic accumulators support systems that benefit from compact energy storage and rapid response characteristics.
The demand pattern suggests that buyers are increasingly evaluating accumulators as part of integrated system performance rather than as standalone spares. This behavior favors suppliers that can provide application engineering support, configuration guidance, and aftermarket service access, because total system reliability and uptime are becoming central procurement criteria.
Supply Chain and Cost Structure Dynamics
Cost structures remain under pressure from input volatility and the operational demands of serving a fragmented global customer base. High-grade steel alloys and specialty elastomers are subject to annual price swings that can materially affect landed cost and margin planning. At the same time, supply chain resilience is becoming a procurement concern, particularly for buyers who depend on timely delivery of certified components for maintenance, retrofit, and new equipment builds.
Manufacturers that combine strategic sourcing, certified component traceability, and regional service coverage are better positioned to stabilize delivery performance and reduce exposure to commodity volatility. For buyers, this means supplier selection should weigh not only price but also sourcing transparency, certification documentation, and the ability to support unplanned maintenance without extended lead times.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of global manufacturers, application specialists, and certification and testing providers that together shape both product availability and market credibility. Companies such as HYDAC International GmbH, Parker Hannifin Corporation, Danfoss Power Solutions, Bosch Rexroth AG, Accumulators, Inc., Freudenberg Sealing Technologies, STAUFF AG, NOK Corporation, Eaton Corporation, SFP Hydraulics, Inc., Roth Hydraulics GmbH, Airline Hydraulics, Teutonic Engineering, and SGS Group illustrate the diversity of positions in the market, from full-spectrum accumulator production to sealing technology expertise and independent testing and certification services.
Differentiation and Strategic Positioning
Leading manufacturers are differentiating along several practical dimensions rather than competing on specification sheets alone.
- Product breadth across accumulator types: Several incumbents offer bladder, piston, and diaphragm variants across industrial and mobile hydraulics, enabling them to serve a wider range of system sizes and application requirements without forcing customers to manage multiple specialized suppliers.
- Material and sealing expertise: Suppliers with in-house materials capabilities and global certifications can move faster on reliability improvements and compliance documentation, which is especially valuable in markets where pressure vessels and safety standards are closely scrutinized.
- Service and repair ecosystems: Manufacturers that provide repair kits, replacement components, and field support create recurring engagement with end users, turning a transactional component purchase into a long-term service relationship.
- Certification and testing credibility: Independent testing and certification providers play an important role in validating pressure vessel integrity and safety compliance. Their involvement raises market trust and can become a differentiator for manufacturers that consistently meet recognized standards.
- Regional presence and application focus: Companies with strong positions in specific geographies or end-use segments can tailor product configurations, documentation, and support to local requirements, which is valuable in markets where standards interpretation and service expectations vary.
Market Structure Evolution
The market is evolving through a combination of consolidation among larger players, continued specialization by regional and application-focused suppliers, and selective entry by firms targeting performance-driven niches. The moderate concentration levels suggest that scale matters, but it does not dominate the market to the point where smaller players are excluded. Instead, the competitive frontier is shifting toward companies that can combine credible certification, reliable material supply, application-specific engineering, and responsive service.
Gas & Liquid Separation Accumulator Market
This dynamic creates opportunity for suppliers that can demonstrate measurable reliability advantages and for buyers that can reduce lifecycle risk by partnering with manufacturers whose compliance posture and service networks match their operating environment. It also means that mergers, acquisitions, and partnership activity may increase as larger players seek to strengthen material capabilities, geographic coverage, or certification portfolios.
Future Trends and Commercial Opportunities
Looking across the 2026 to 2032 forecast window, three interconnected trends are likely to shape where value is created and where risk concentrates.
Trend One: Lifecycle Value Replaces Unit Price as the Central Buying Criterion
As equipment owners face pressure to reduce downtime and extend service intervals, accumulator purchases will be evaluated increasingly through total cost of ownership rather than initial price. This trend favors products with documented durability, stable pre-charge performance, and strong aftermarket support. The commercial opportunity lies in packaging reliability data, service access, and compliance documentation into a cohesive value proposition that reduces operating risk for end users.
The associated risk is that manufacturers without robust service infrastructure or material traceability may find it harder to compete in segments where uptime and compliance assurance matter most.
Trend Two: Regulatory Alignment Expands Use Cases in Commercial Transportation and Adjacent Mobility
The authorization of seamless steel hydraulic accumulators containing compressed nitrogen for commercial transportation marks a meaningful signal that regulatory frameworks can adapt to support new applications when safety criteria are clearly met. If this pattern continues, it could broaden the addressable market in transport-related hydraulic systems and encourage integrators to consider hydraulic energy buffering in fleet and mobile equipment designs.
The opportunity is to prepare product portfolios, documentation, and testing evidence for transport-oriented requirements before demand materializes at scale. The uncertainty is that regulatory progress can be uneven across jurisdictions, and standards such as EN 14359 and the Pressure Equipment Directive will continue to define the safety baseline, which means compliance readiness must be sustained rather than treated as a one-time achievement.
Trend Three: Material Volatility and Sourcing Strategy Become Competitive Differentiators
With high-grade steel alloys and specialty elastomers subject to significant annual price swings, companies that manage procurement strategically, maintain certified traceability, and communicate cost-transparently will be better positioned to protect margins and customer trust. The commercial opportunity is to treat sourcing resilience as a selling point, particularly for buyers who are sensitive to lead times, certification integrity, and unpredictable maintenance costs.
The risk is that unmanaged input cost volatility can erode competitiveness in price-sensitive segments and complicate long-term quoting and service pricing. Manufacturers that cannot stabilize their cost base may be forced into reactive pricing moves that weaken customer relationships.
Strategic Actions for Decision Makers
The market is creating clear points of leverage for different stakeholder groups, but capturing them requires timely, segment-specific intelligence rather than broad market assumptions.
For Manufacturers and Suppliers
- Prioritize lifecycle value messaging: Build product narratives around durability, service interval extension, and compliance documentation, supported by application-specific evidence where possible. This aligns with the shift toward total cost of ownership and helps defend positioning against commodity-driven price competition.
- Strengthen material and certification readiness: Invest in sourcing stability, traceability, and certification coverage to reduce exposure to input volatility and to meet the expectations of buyers operating under pressure equipment and fluid power standards. This is especially relevant for firms targeting transport-related and safety-intensive applications.
- Expand service and repair engagement: Where feasible, deepen aftermarket support through repair kits, replacement components, and technical assistance. Recurrent service relationships can improve customer retention and provide a buffer against transactional price pressure.
For Investors and Strategic Partners
- Focus on differentiation that compounds: Assess companies based on in-house material capability, certification breadth, service coverage, and application expertise rather than scale alone. These attributes are more likely to sustain margin and share over the forecast period than volume growth in isolation.
- Monitor regulatory-enabled expansion carefully: Track developments such as transport authorization pathways and evolving safety standards, since these can open new use cases but also raise the compliance bar. Investments should account for both the upside of expanded application scope and the cost of maintaining conformance.
- Watch consolidation signals: Moderate concentration and a long tail of specialists suggest that selective M&A or partnership activity could reshape regional coverage, material access, and certification capabilities. Strategic positioning should consider how such moves might alter competitive dynamics in target segments.
For Procurement and Equipment Integrators
- Evaluate suppliers on total operating risk: Compare accumulator options not only by unit cost but by documented reliability, certification status, service availability, and sourcing transparency. Suppliers that can reduce maintenance uncertainty and speed unplanned Repairs may deliver lower lifecycle cost even if initial pricing is higher.
- Align specifications with application reality: Match accumulator type and configuration to the actual pressure cycles, environmental conditions, and maintenance expectations of the equipment. Over-specifying or under-specifying can both create hidden cost, so application engineering support should be part of the selection process.
- Use compliance documentation as a selection filter: Verify that suppliers meet relevant standards and can provide the testing and certification evidence needed for your operating jurisdictions. This reduces integration risk and supports smoother approval processes in regulated environments.
Getting Ahead with Segment-Level Intelligence
The strategic signals in this market are clear at the macro level, but the practical decisions that determine competitive outcomes are made in the details: which applications are expanding fastest, how regional demand is shifting, where margin is being protected or eroded, and which compliance or sourcing assumptions will hold over the next planning cycle. Broad market figures establish direction, but actionable positioning depends on segment-level data, customer behavior trends, and a realistic view of where competitive advantage can be sustained.
PW Consulting's complete research report provides deeper segmentation data, company-level profiling, and tailored recommendations designed to support procurement, investment, and product strategy decisions. For teams that need to move from market awareness to executed planning, the full study offers the granularity required to translate these trends into specific next steps.
For detailed analysis of this topic, please visit the official page: Hydraulic Accumulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com