

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Insights: Sesame Oil Market to Hit USD 7,235M by 2032 at 5.9% CAGR
By pmarketresearch, 2026-07-30
Sesame Oil Market — Strategic Imperatives for 2026
A PW Consulting Industry Brief
Executive snapshot
The sesame oil market has entered a structurally different phase. After expanding from roughly USD 2.9 billion in 2020 to an estimated USD 4.9 billion in 2025 (base year), the sector is projected to continue its upward trajectory through our forecast window (2026–2032) at a compound annual growth rate of 5.9%, reaching approximately USD 7.235 billion by 2032. The market exhibits a high degree of concentration at the top: the three largest players account for well over half of global revenues, and the five largest exceed three quarters of the market, creating a competitive environment where scale, secure raw-material access, and route-to-market sophistication matter more than ever.
Sesame Oil Market
This brief previews the strategic value of PW Consulting’s full Sesame Oil Market report for executive teams making decisions in 2026. It highlights the macro trajectory, the commercial and operational levers that will determine winners and losers, and the practical workstreams the full report equips clients to execute. To preserve the commercial sensitivity of our primary research and to guide prospective buyers toward the full deliverable, this summary intentionally omits detailed regional, type and application splits; those granular tables and downloadable models are available in the full report.
Sesame Oil Market
Why this matters for 2026 decision-making
- Timing of capacity investments. With a mid-single-digit CAGR and clear evidence of recent capacity commitments across the value chain, 2026 is a decision year for processing and packaging investments. Capital deployment now determines who captures premium product growth over the next six years.
- Supply security & margin preservation. Sesame seed supply remains geographically concentrated and agronomically sensitive. Firms that secure seed supply—through contract farming, strategic sourcing partnerships, or upstream integration—will protect margins as demand for traceable, certified lines increases.
- Premiumization & channel segmentation. Health-oriented and premium channels (organic, cold-pressed, certified non-GMO) are expanding faster than commodity food channels. Winning in premium requires investments in product innovation, certification, and targeted marketing rather than simply scaling base oils.
- Regulatory & labeling risk. Recent regulatory signals emphasize allergen declaration for sesame and tighter traceability expectations; compliance and proactive communication will be a competitive differentiator and a mitigant to recall risk.
Key market dynamics and operational levers
The market’s near-term trajectory is driven by a mix of demand-side premiumization and supply-side constraints. The following dynamics should be at the top of every 2026 operational agenda:
Sesame Oil Market
- Premium and functional demand. Consumers continue to trade up for cold-pressed, organically certified, and provenance-labelled oils. Retail buyers are expanding shelf space for premium SKUs and are willing to pay a routing premium if provenance and health claims are verifiable.
- Supply-side realities. Seed-to-oil conversion rates remain a key cost and capacity driver; mechanical pressing yields typically fall in a narrow band depending on variety and processing conditions. Where seed production is limited geographically, downstream processors must plan for seasonal volatility and local harvest cycles.
- Traceability and certification. Certification (USDA Organic, Non-GMO verification) and digital traceability are no longer optional for premium channels. Early pilots indicate that blockchain-enabled provenance can shorten buying cycles with large retailers and provide price resilience.
- Regulatory compliance. Updated allergen labeling requirements and heightened scrutiny on origin claims require updated packaging, ingredient declarations, and periodic supplier audits—factors that impact time-to-market and SKU economics.
Competitive landscape — what incumbents are doing
Market concentration at the top has shaped a landscape where incumbents pursue a mix of capacity, product differentiation, and supply-chain control. Two illustrative profiles:
- Sesaco Corporation (Paris, Texas, USA) — A vertically integrated operator focused on breeding shatter-resistant sesame varieties and operating primary processing facilities in the U.S. Their strategy centers on supply security and integrated value capture: upstream variety development, seed processing, and branded oil distribution. For competitors, Sesaco’s model raises the bar on traceability and domestic supply resilience.
- Kadoya Sesame Mills Incorporated (Tonosho, Japan) — A premium-positioned producer best known for cold-pressed and toasted sesame oils with an emphasis on traditional methods and certified lines. Recent strategic moves include facility renewal efforts to bolster premium output and product launches with localized flavor profiles. Kadoya’s playbook underscores the value of heritage branding paired with targeted product innovation for international retail channels.
Other notable moves shaping the competitive set: multi-hundred-million-dollar capacity investments by broader condiment groups to secure bottling and blending scale, and early-adopter supply-chain pilots using blockchain and farm certification to meet EU compliance and retailer traceability requirements. These initiatives illustrate two parallel responses to growth: scale-up of commodity supply and premium differentiation through provenance.
What the PW Consulting report delivers (practical, execution-focused)
The full report is structured for action. It includes:
- Market sizing and forecast models (2020–2032) with downloadable Excel modules that allow clients to run custom scenarios aligned to their target regions and applications.
- Supply-chain heatmaps showing seed origin, processing nodes, critical logistics chokepoints, and seasonal risk windows.
- Price and margin curves by product tier (commodity to premium), with sensitivity analyses linking seed inflation, yield variance, and freight shocks to EBITDA impact.
- Commercial playbooks for three archetypal buyers: branded manufacturers, ingredient buyers for foodservice, and private-label co-packers. Each playbook contains go-to-market checklists, pricing negotiation levers, and retailer engagement templates.
- Regulatory and certification matrix: implications of allergen labeling, organic and non-GMO verification, and mandatory origin declarations for target markets.
- M&A and partnership shortlist: candidate profiles, rationale, and integration risk scoring for acquirers seeking scale or premium capability.
- Operational improvement checklists: processing yield optimization, packaging redesigns to reduce TCO, and pilots for digital traceability implementation.
Note: the full report contains the detailed regional, type and application splits referenced above; those granular tables and the underlying primary-data appendices are intentionally omitted from this brief to protect client value and to invite direct engagement.
How to act in 2026 — recommended sequencing
We structure our recommended approach into four actionable horizons to convert the report’s findings into measurable outcomes:
- Immediate (0–3 months). Rapidly audit seed-supply contracts for volume, quality and traceability clauses; prioritize SKU rationalization to shift shelf space toward higher-margin premium SKUs; run a 90-day pilot on provenance labelling with a major retail partner.
- Near term (3–12 months). Execute a sourcing strategy that blends contracted acreage, strategic supplier partnerships, and short-term spot coverage to stabilize raw-material cost volatility; implement certification roadmaps for organic and non-GMO verification where channel economics support premiums.
- Medium term (12–24 months). Make go/no-go decisions on capacity investments based on scenario outputs from our forecast models; pursue co-manufacturing or minority stakes in processing facilities if rapid capacity expansion is required; scale traceability pilots to production volumes that satisfy large retail buyers.
- Long term (24–36 months). Lock in strategic partnerships or M&A to secure upstream seed supply or downstream branded distribution in priority markets; embed an advanced pricing architecture that captures premium differentiation while protecting base-business margins.
Risks, mitigants and unanswered questions
Key risks include agronomic shocks to seed supply, sharp freight and packaging cost escalation, regulatory shifts on labeling, and reputational exposure from provenance disputes. Mitigation levers assessed in the full report include diversified sourcing, inventory and hedging strategies, packaging redesign for cost and sustainability, and pre-competitive industry coalitions for verification standards.
Conclusion — why you should prioritize this work in 2026
The sesame oil market’s combination of steady growth, premium segment expansion, and concentrated supplier power creates a narrow window in 2026 for strategic moves that lock in advantage for the next business cycle. Whether the objective is to scale commodity throughput, capture premium margins, or acquire strategic assets, the decisions you make this year will materially influence market share and profitability through 2032.
PW Consulting’s full Sesame Oil Market report supplies the granular segmentation, scenario models, and playbooks necessary to translate high-level insight into executable programs. For clients preparing investment memos, negotiating supplier agreements, or designing product launches in 2026, the report is designed as an operational toolkit rather than a descriptive summary.
Next step
- Contact PW Consulting to request the full report package, which includes the Excel forecast model, segmentation tables, primary research appendices, and tailored advisory engagements to turn insights into decisive action.
For detailed analysis of this topic, please visit the official page: Sesame Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrode Paste Market — USD 1,080M by 2032, 2.7% CAGR (2026–2032)
By pmarketresearch, 2026-07-30
Electrode Paste Market 2026: Strategic Imperatives for Leaders — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a forward-looking synthesis of our Electrode Paste Market study designed to equip executives, product leaders, and M&A teams with the decision framework they need for 2026. This preview outlines the strategic value of the full report, summarizes high‑confidence market dynamics, and highlights actionable pathways companies can pursue — while reserving the granular segment matrices and proprietary model outputs for the full report access.
Electrode Paste Market
Why this study matters for 2026 decisions
The electrode paste market has transitioned from a niche clinical consumable to a supplier‑managed, regulation-intensive segment of neurodiagnostic and electrocardiographic healthcare workflows. Our model—which uses 2025 as the base year and projects through 2032—shows the market reaching USD 895.0 Million in 2025 and following a measured trajectory at a 2.7% compound annual growth rate (CAGR) to around USD 1,080 Million by 2032. That trajectory masks important operational inflection points: supply‑side specialization, evolving clinical best practices for long‑duration monitoring, and payer/regulatory clarity that together will shape winners and laggards through the middle of the next decade.
Electrode Paste Market
For executives deciding on capex, R&D prioritization, channel strategy, or M&A in 2026, the study provides three things that matter most: a validated top‑down market model, a risk‑adjusted scenario set for demand drivers, and a playbook linking regulatory obligations to go‑to‑market actions.
Electrode Paste Market
What the full report delivers (practical, transaction‑ready outputs)
- Market model and forecast (2026–2032) with sensitivity testing across pricing, procedure volumes, and raw‑material cost shocks.
- Segment mapping by region, product type, and clinical application with decision rules for product prioritization (note: detailed segment tables and vendor share matrices are available in the full report).
- Regulatory and reimbursement matrix tying product claims, 510(k) pathway considerations, and common CPT/DRG interactions to commercial levers.
- Supplier and raw‑material risk dashboards, including backward compatibility testing requirements and quality certifications that drive procurement preferences in hospitals and labs.
- Competitive intelligence dossiers and playbooks for the top commercial and technology players — designed to inform negotiations, partnership diligence, or acquisition screening.
- Actionable go‑to‑market plans covering distributor selection, clinical evidence generation, and lifecycle management to maximize uptake in neurodiagnostic and ECG workflows.
Market dynamics and regulatory context
Two regulatory realities shape near‑term strategic choices. First, electrode pastes and related gels fall under FDA’s Class II device controls and, in practice, are frequently managed through the 510(k) pathway with product code designations that require biocompatibility, impedance, and adhesion equivalence testing. Second, ISO 13485 remains a de facto minimum standard for manufacturing quality — purchasers increasingly make ISO certification a contractual prerequisite. These compliance constraints raise the bar for new entrants and create a moat for incumbents that have invested in validated manufacturing and clinical comparators.
The market also sits within established reimbursement pathways for EEG/ECG procedures: electrode pastes used in diagnostic neurophysiology benefit from procedure-level coverage under standard CPT ranges, which in turn influences hospitals’ willingness to adopt premium formulations that demonstrably reduce skin irritation or improve signal fidelity during extended monitoring. That linkage between clinical benefit and reimbursement creates a premium lane for differentiated products that can be proven in head‑to‑head operational studies.
Competitive landscape — focused profiles
- Parker Laboratories, Inc. — Headquartered in Fairfield, New Jersey, Parker commercializes Spectra 360, a salt‑free, chloride‑free, bacteriostatic conductive gel formulated for prolonged electromedical skin contact. That formulation addresses a clear clinical pain point—minimizing skin irritation during extended EEG/ECG monitoring—and supports claims that matter in procurement evaluations. Parker’s product documentation and regulatory positioning reflect an emphasis on quality and clinical suitability for neurodiagnostic workflows.
- Weaver and Company — Based in Aurora, Colorado, Weaver’s Ten20 conductive paste is a long‑standing option for securing non‑gelled cup electrodes and is widely distributed through national medical supply channels. The product’s regulatory clearances and distribution partnerships position Weaver as a reliable logistics and channel partner for clinical units that prioritize supply continuity and established clinical performance.
Both companies operate in a regulatory environment where 510(k) clearances and ISO 13485 manufacturing controls are material commercial assets — and where distribution partnerships with major suppliers materially influence adoption curves in hospital systems. The market concentration metrics indicate the top three suppliers account for a meaningful majority of market share, creating both barriers to entry and opportunities for targeted consolidation.
Where strategic value accumulates — three high‑impact plays for 2026
- Product differentiation through clinical evidence: Incremental performance advantages—reduced skin irritation, lower impedance variability during long‑duration monitoring, or enhanced bacteriostatic properties—translate to procurement preference when supported by operational trials. Prioritize limited‑scope clinical studies tied to clear hospital KPIs (reduced site revisits, fewer re‑applications, shorter prep time).
- Channel and procurement optimization: Distributors and group purchasing organizations dictate access to large neurodiagnostic centers. Negotiate distribution clauses that lock in supply continuity and tiered pricing tied to volume thresholds; consider consignment or vendor‑managed inventory pilots to reduce hospital stockouts and accelerate adoption.
- M&A and partnership discipline: Given the market’s moderate concentration and predictable growth, bolt‑on acquisitions that add distinct formulations, validated manufacturing capacity, or regional distribution can generate immediate scale benefits. Use the report’s M&A heatmap to prioritize targets that close capability gaps rather than simply expand product lines.
Supply chain and raw‑material considerations
Raw‑material choices are not commoditized in this market. Formulation choices that avoid salts and chlorides can materially reduce dermatological adverse events in long‑duration use cases—an attribute buyers will pay to avoid downstream clinical incidents. At the same time, reliance on single‑source raw materials or specialized bacteriostatic agents introduces vulnerability. The full report maps supplier concentration for key inputs and provides contingency strategies for contract manufacturers and finished goods producers.
Commercial and pricing tactics
Price alone is an insufficient leverage point when procurement teams balance total cost of care, clinical outcomes, and inventory risk. Instead, successful vendors blend: (a) evidence‑based premium positioning for differentiated formulations, (b) competitive tender strategies for commoditized product lines, and (c) service offerings (training, inventory management) that shift purchasing decisions from line‑item to pathway procurement. The report supplies tender templates and EBITDA-impact models for common contract scenarios.
Risk framework for investors and corporate strategists
- Regulatory risk: Clearance timelines and claims validation can delay market entry; prioritize products with clear equivalence paths or invest in the clinical programs that substantiate novel claims.
- Operational risk: Manufacturing quality (ISO 13485) and supply continuity are primary commercial gating factors for hospital contracts.
- Reimbursement and clinical adoption risk: While procedure reimbursement is established, conversion to a premium product depends on demonstrable operational savings or clinical benefit.
How PW Consulting’s report removes guesswork
Our full study integrates a validated market model (base year 2025, historical 2020–2025, forecast 2026–2032) with granular scenario testing, regulatory checklists, a proprietary vendor scorecard, and an M&A heatmap intended for near‑term deal execution. For leadership teams, that means moving from anecdotal decision‑making to evidence‑based strategies: you will know where to commit R&D dollars, how to structure distribution agreements, which assets to target for acquisition, and what clinical evidence is required to win in large hospital systems.
Next steps — what to request from the full report
- Access the full dataset and interactive forecast model to run your own scenario (pricing, procedure growth, raw material shocks).
- Download vendor scorecards and regulatory dossiers for target due‑diligence workflows.
- Obtain the commercial playbooks and tender templates to accelerate 90‑day sales cycles in hospital chains and diagnostic labs.
PW Consulting’s Electrode Paste Market report is structured to support high‑stakes decisions in 2026: product portfolio prioritization, distribution contracting, and M&A screening. This preview outlines the strategic contours; the full report contains the segment‑level matrices, supplier share details, and proprietary financial models that underpin these recommendations. For executives intent on winning the next wave of clinical adoption, the difference between an informed strategy and a reactive posture will be access to that underlying intelligence.
To obtain the complete report and the accompanying data model, please visit the PW Consulting research portal. The full report contains the detailed segmentation, vendor share matrices, and downloadable forecasting workbooks needed to execute confidently in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Electrode Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Carbon-Carbon Composites to hit USD 334.67M by 2032 (6.55% CAGR)
By pmarketresearch, 2026-07-30
Carbon-Carbon Composites 2026 Strategic Preview: Why This Market Report Matters to Executive Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our new Carbon-Carbon Composite Material Market study — a practical, decision-oriented resource tailored for boardrooms, corporate development teams, and industrial strategists preparing for 2026. This preview synthesizes the macro trajectory, structural dynamics, and competitive moves that should shape any capital, sourcing or commercial decision in the coming 18–36 months. Detailed, segment-level intelligence is intentionally reserved for the full report; the purpose here is to show analytical depth while preserving the tactical granularity that drives commercial advantage.
Carbon-Carbon Composite Material Market
Market trajectory — a compact, actionable view
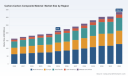
The carbon-carbon composite market has moved from niche specialty material into a scaling commercial sector with clear demand drivers and rising strategic importance. Our baseline sizing shows the market increasing from approximately USD 163.2 million in 2020 to USD 215.0 million by the 2025 base year — reflecting both steady end-market adoption and price dynamics. Looking forward, the market is forecast to grow at a compound annual growth rate (CAGR) of 6.55% through our 2026–2032 forecast window, reaching roughly USD 334.7 million by 2032.
Carbon-Carbon Composite Material Market
Two practical takeaways for 2026 planning: first, the growth profile is sufficiently robust to justify targeted capacity investments and R&D commitments for those seeking to capture premium end-markets (aerospace thermal protection, high-temperature industrial components, and advanced braking systems). Second, growth is uneven by capability and application; value will accrue to firms that combine material science leadership with qualified supply relationships into aerospace and defense OEMs.
Carbon-Carbon Composite Material Market
Structural dynamics that will determine winners and losers
- Supplier concentration and precursor risk: The upstream supply of carbon fiber precursors is highly concentrated. This creates a pinch-point for carbon-carbon producers and elevates the value of secured, diversified precursor arrangements — especially during periods of demand acceleration or policy-driven trade shifts.
- Production economics: Global production tonnage and pricing trends matter as much as revenue growth. In 2024, global production reached the tens of thousands of tonnes, with an average selling price in the low thousands of USD per tonne; nuances of capacity utilization and product mix will drive margin differentials more than headline revenue in 2026.
- Policy and tariff sensitivity: Recent tariff framework changes and evolving trade policy have already increased export costs and highlighted the need for redundant manufacturing footprints close to key end-markets. Firms with global footprint flexibility and near-market production will gain a competitive edge in contract awards.
- Environmental and feedstock regulation: Environmental restrictions impacting PAN-based precursor production are not peripheral — they affect upstream costs, capital intensity, and permit timing. Leaders will be those who incorporate precursor security and regulatory scenario planning into capital allocation decisions.
- Market concentration at producer level: The industry displays a high degree of seller concentration — the top suppliers capture the majority of the market — which favors incumbents on long-term contracts but opens windows for regional challengers who can guarantee supply continuity or superior cost.
Why this report is operationally valuable for 2026 decisions
Board-level questions in 2026 will be less about “is this market growing?” and more about “how do we allocate scarce capital and managerial attention to maximize rate-of-return while de-risking supply?” Our report is structured to answer those questions with tools and templates you can operationalize immediately:
- Actionable market sizing and three-tier scenario modeling (conservative, base, upside) calibrated to tariff, precursor availability, and aerospace demand shocks.
- Manufacturing cost curves and margin sensitivity analyses (unit economics by process route), enabling rapid ROI checks on capacity projects and retrofits.
- Supply-chain resilience playbook: supplier scorecards, dual-sourcing templates, and contracting strategies to lock precursor supply without overpaying for optionality.
- Commercial playbooks for OEM partnerships — with negotiation levers and risk allocation language for long-term off-take agreements.
- M&A screening and integration checklist targeted at bolt-on targets, vertical-integration candidates (precurors, densification specialists), and regional capacity entrants.
- Regulatory and ESG impact matrix addressing PAN precursor regulation, tariff scenarios and permitting timelines for new facilities.
- Proprietary company dossiers, supplier maps and a competitive heat map to prioritize commercial outreach and partnership testing.
Competitive landscape — what incumbents are doing and why it matters
The current competitive set includes global materials champions, specialty carbon firms, and a growing cohort of regional producers. Several recent industry moves crystallize the strategic playbook:
- Capacity expansion aligns with aerospace and advanced mobility demand: Major producers and OEM partners have announced or initiated capacity increases aimed at the high-margin aerospace and premium automotive segments. These moves indicate companies are betting on sustained demand for thermal protection and braking systems that favor carbon-carbon composites.
- Strategic vertical plays and product launches: Firms are both extending upstream (precursor and precursor technology) and enhancing product portfolios (next-gen prepregs, densified C/C). Sustainability- and performance-branded launches signal that differentiation will increasingly rest on proprietary processing and lifecycle advantages.
- Portfolio reshaping through asset transactions: Divestments and acquisitions in the space suggest players are optimizing for focus on core technologies — enabling faster commercialization cycles for niche thermal protection systems while creating acquisition targets for scaling manufacturers.
For executive teams, the competitive implications are clear: scale matters for meeting OEM qualification timelines, but specialty IP and supply security are equally critical. A binary strategy — either scale at all costs or remain a niche player — is risky. The optimal position for 2026 is hybrid: selective capacity growth combined with strategic partnerships or minority stakes in precursor and processing technology providers.
Emerging strategic options to consider for 2026
- Near-market capacity investments: Prioritize small- to mid-scale production nodes in geographies exposed to tariff volatility to shorten lead times and reduce logistics risk.
- Precursor hedging and JV models: Move beyond spot contracts. Consider joint ventures or long-term offtakes with leading precursor producers to secure volumes and stabilize input costs.
- Product differentiation via densification and surface engineering: Invest in processing capabilities that improve durability under extreme thermal cycling — a value driver for aerospace thermal protection and braking systems.
- Selective M&A and strategic minority stakes: Use capital to access IP and supplier continuity (e.g., densification specialists, precursor recyclers) rather than pursuing broad horizontal consolidation.
- Regulatory and ESG roadmap: Build an upstream emissions and feedstock compliance plan; this reduces permitting risk and can be a commercial differentiator for OEM partners focused on ESG.
Case in point: signals from recent industry developments
- Large-scale capacity expansions at leading chemical and composites firms underscore a near-term supply response to aerospace and space program demand.
- OEM-led facility investments and contract shifts reflect a desire to secure qualified domestic supply chains for critical thermal protection and braking systems.
- Product launches with sustainability branding indicate that customers are beginning to value lifecycle attributes — a trend that will shape procurement specifications over the next three years.
What the full PW Consulting report delivers (reserved tactical detail)
The full report translates the strategic implications above into executable initiatives. It contains segment-level market shares, regional demand curves, application-specific adoption timelines, supplier pricing matrices, and a prioritized deal pipeline for M&A and JV targets. We also include a ready-to-use board briefing deck and an executive decision matrix that maps capital allocation choices to expected IRR ranges under alternative policy and demand scenarios.
For executives evaluating capex, M&A, or supply-chain diversification in 2026, this is not an academic exercise — it is the operational intelligence that reduces execution risk and concentrates investment where the highest, fastest returns are available. To preserve competitive advantage, we reserve the full, segment-level data and model access for report subscribers.
Next steps for corporate leaders
- Begin or update a two-way stress test of your supply chain under tariff and precursor-constrained scenarios. Use the results to define minimum viable local capacity needs.
- Identify one or two precursor counterparties for deeper commercial engagement (JV or long-term offtake) and perform fast-track diligence using the supplier scorecards in our toolkit.
- Prioritize investment in processing capabilities that convert carbon-carbon advantages (thermal, high-temp structural) into certified products for aerospace and premium automotive OEMs.
- Request the full PW Consulting report to access the segment-level modeling, company dossiers, and the transactional playbook required to operationalize these steps.
In 2026, decisions about where to invest, whom to partner with, and how to manage precursor risk will determine which companies capture disproportionate value as the carbon-carbon market scales. PW Consulting’s report transforms those strategic choices from high-level debate into executable programs — but the granular data that unlocks specific commercial moves is reserved for the full study. Contact PW Consulting to obtain access and convert this strategic preview into a robust 2026 action plan.
For detailed analysis of this topic, please visit the official page: Carbon-Carbon Composite Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Industrial CT Market to Hit USD 775 Million by 2032 at 7.5% CAGR - PW Consulting
By pmarketresearch, 2026-07-30
Industrial Computed Tomography Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As industrial supply chains and quality regimes demand ever-greater insight into internal geometries, the Industrial Computed Tomography (CT) market has moved from an R&D niche to a production-critical capability. PW Consulting’s latest study (base year 2025) finds a robust, sustained expansion trajectory for the sector — underpinned by a 7.5% compound annual growth rate (CAGR) through the forecast window (2026–2032). The market has grown from roughly USD 380 Million in 2020 to approximately USD 485 Million in 2025, and our modelling points to continued momentum toward an estimated USD 775 Million by 2032 (all values USD Million).
Industrial Computed Tomography Market
This briefing distills the research’s strategic utility for corporate leaders planning capital allocation, product roadmaps, M&A activity, and operational deployment in 2026 — while deliberately omitting the granular segmentation tables contained in the full report to preserve its lead-generation purpose.
Industrial Computed Tomography Market
Why this matters in 2026: three strategic inflection points
-
From inspection to assurance: Industrial CT is shifting from episodic laboratory use to embedded quality infrastructure. As manufacturers face regulatory and contractual pressures for “zero-defect” outcomes — notably in aerospace and automotive — CT is becoming an integral inspection stage rather than an occasional diagnostic tool.
Industrial Computed Tomography Market -
Software and AI are the multiplier: hardware improvements remain important, but value capture increasingly flows to software — reconstruction algorithms, AI-driven defect classification, and metrology suites that convert scans into actionable control limits.
-
New production paradigms increase internal-complexity testing needs: the rise of additive manufacturing (AM) and complex multi-material assemblies creates inspection demand that only volumetric imaging can satisfy reliably and at scale.
Market trajectory: context and implications
Our historical series (2020–2025) shows steady expansion, with a notable acceleration into 2024–2025 as OEMs and contract manufacturers formalized CT workflows. Projected growth under a 7.5% CAGR leads to meaningful market enlargement across 2026–2032. For 2026 specifically, buyers should assume continued price-performance improvements in both detectors and reconstruction software, with service models (on-site, captive lab, and remote-as-a-service) maturing rapidly.
From a competitive structure perspective, concentration is moderate: the top three vendors account for roughly one-third of the market and the top five approach the low-forties (CR3 ≈ 35%; CR5 ≈ 42%). This combination of significant incumbents and a broad long tail creates both acquisition opportunities and price competition for differentiated, software-led offerings.
What the full report contains (practical, actionable deliverables)
- Market sizing and topline forecasts (2020–2032) with scenario sensitivity for hardware price deflation and AI-software uptake.
- Go-to-market playbooks for vendor types: OEM hardware manufacturers, software analytics firms, and inspection-as-a-service providers — including suggested sales motions, channel mixes, and sample ROI models for common buyer personas.
- Technology deep dives: comparative analysis of detector technologies, X‑ray sources, reconstruction pipelines, and metrology integrations — with implications for throughput, accuracy, and cost-per-part.
- Regulatory and standards assessment: implications of EN ISO 15708-3:2025 and related guidance for operationalization, qualification, and auditability of CT-derived results.
- Capability gap analysis for major OEMs and prospects: operational readiness checklists and prioritized investments to move from pilot projects to production-level inspection.
- Strategic M&A and partnership mapping: high-opportunity targets by capability (AI analytics, specialty CT hardware, volumetric metrology) and a valuation sensitivity framework keyed to recurring revenue adoption.
- Executive decision support tools: CapEx phasing templates, a 24-month implementation playbook for internal CT labs, and procurement scorecards for vendor selection.
Note: the report intentionally withholds granular segmentation tables in this public summary. Subscribers and licensed clients receive detailed region-, type-, and application-level breakdowns, including modeled adoption curves and pricing elasticity matrices.
Competitive landscape: profiles and strategic postures
The market features a mix of long-standing industrial metrology firms, specialized radiography OEMs, and agile entrants focusing on affordability and AI. Below we highlight the strategic positioning of prominent players covered in the study and what each move implies for 2026 decision-makers.
-
Waygate Technologies (Houston, TX) — Strengths: legacy footprint in industrial radiography, broad service capabilities, and Phoenix-series systems tuned for non-destructive metrology and in-line process control. Strategic posture: leveraging service contracts and integrated systems to defend installed-base revenue. Implication: suppliers and buyers should expect bundled hardware-plus-services offers that prioritize uptime and traceable inspection chains.
-
Nikon Metrology (Milton Keynes, UK) — Strengths: wide product range spanning large-envelope CT to microfocus systems and a reputation in precision metrology. Recent move: June 2025 VOXLS 20 C 225 product launch, emphasizing a metrology-grade platform optimized for electronics, AM, aerospace and medical inspection. Implication: product launches like this compress the timeline for qualification in regulated industries and raise the bar on metrology accuracy expectations.
-
ZEISS (Oberkochen, Germany) — Strengths: premium metrology systems and strong software (INSPECT) integration for dimensional control and defect detection. Recent presence at EASTEC 2025 shows continued investment in trade-level visibility. Implication: ZEISS will remain a go-to choice where precision and software ecosystem depth trump unit price.
-
Werth Messtechnik (Wetzlar, Germany) — Strengths: hybrid CT-plus-coordinate-measuring-machine integrations for manufacturers that require direct metrology workflows. Implication: attractive for manufacturers seeking to collapse inspection steps and reduce measurement uncertainty transfer between systems.
-
North Star Imaging (Rogers, MN) — Strengths: focused systems portfolio for 2D/3D radiography with strong NDT pedigree. Implication: appeals to test labs and industrial NDT buyers valuing fast throughput and rugged field-capable systems.
-
Lumafield (United States) — Strengths: disruptive product architecture (affordable Neptune CT) and an AI-first analytics suite (Voyager) targeting office- and lab-based high-resolution inspection. Implication: such entrants accelerate democratization of CT and force incumbents to respond on software, pricing, and ease-of-use.
Dynamics, standards and regulatory lens
EN ISO 15708-3:2025 establishes clearer expectations for operation, image interpretation, defect detection, and result reliability in industrial CT. For procurement and compliance officers, this standard will shortly become a de facto checklist item for supplier qualification in regulated sectors. Simultaneously, macro drivers — widespread adoption of CT for flaw detection, the inspection demands of additive manufacturing, and regulatory pressure for zero-defect production — are creating predictable pockets of demand.
From a risk perspective, two dynamics deserve attention in 2026:
- Operationalizing standard-compliant workflows will require investments in operator training, validated software toolchains, and audit-grade documentation — not just hardware.
- As software becomes the differentiator, IP and data-security questions rise: scanned volumetric datasets are sensitive, often containing proprietary geometry; secure data pipelines and SaaS governance will be procurement decision criteria.
Strategic recommendations for 2026
-
Prioritize software-enabled differentiation: If you are a vendor, invest at least proportionally more in AI-enabled analysis, cloud-enabled workflow orchestration, and tight metrology integrations than in incremental hardware refinements.
-
Adopt a staged CapEx approach: Buyers should pilot CT in critical product lines (flight-critical, safety, or high-cost rework) before scaling. Use modular acquisition and shared-lab models to lower time-to-value.
-
Prepare for standards-led procurement: Update supplier RFPs and qualification checklists to reflect EN ISO 15708-3:2025 requirements, including traceability, operator competency, and software validation evidence.
-
Consider M&A selectively: For incumbents seeking rapid expansion into software or service models, bolt-on acquisitions of AI analytics specialists or regional service labs offer faster capability delivery than in-house development.
-
Lock down data governance and SaaS security: For providers of cloud-based reconstruction and analytics, SOC-type certifications and contractual protections around scan data will be decisive competitive differentiators.
How PW Consulting helps
Our full Industrial CT market research provides the actionable elements procurement teams, R&D leaders, and corporate development functions need to make defensible 2026 decisions: validated financial models, procurement scorecards, go-to-market playbooks, and a prioritized list of tactical investments to accelerate production readiness. This public briefing demonstrates the logic and strategic direction; the licensed report contains the granular segmentation, regional adoption curves, and per-application demand matrices that underpin executable plans.
Call to action
Leaders preparing 2026 budgets should treat this market as a near-term capability lever rather than a distant technology bet. Contact PW Consulting to access the full report, receive a tailored executive briefing, or engage our readiness workshop to translate the findings into a 12–24 month implementation roadmap aligned to your product lines and regulatory footprint.
For detailed analysis of this topic, please visit the official page: Industrial Computed Tomography Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microgrid Market to Reach USD 83,000 Million by 2032 at 17.5% CAGR
By pmarketresearch, 2026-07-30
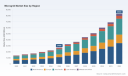
Microgrid Market — 2026 Strategic Preview
As global energy systems pivot toward resilience, decarbonization and distributed intelligence, microgrids are moving from niche pilot projects to strategic infrastructure assets. PW Consulting’s Microgrid Market study (base year 2025; figures in USD Million) quantifies that transition and translates it into practical guidance for executives planning capital allocation, procurement and partnership strategies in 2026. The market trajectory is unambiguous: from roughly USD 14.0 billion in 2020 to USD 27.0 billion in 2025, and accelerating into the forecast horizon — the market is projected to surpass USD 32.8 billion in 2026 and to approach USD 83.0 billion by 2032, reflecting a compound annual growth rate of 17.5% for the forecast period.
Microgrid Market
Why this report matters for 2026 decision-makers
- Timing: The near-term inflection in 2026 creates a narrow window where technology choices, sourcing commitments and enabling contracts lock in returns over multi-decade project lives.
- Risk-to-reward calibration: Rapid growth increases both upside and operational complexity — executives must reconcile capex timing with evolving regulation and supply-chain constraints.
- Competitive positioning: A moderate level of market concentration (CR3 ≈ 35.2%; CR5 ≈ 45.1%) means incumbent scale matters, but there is ample opportunity for specialist players and new entrants with focused value propositions.
- Policy arbitrage: Incentive programs, interconnection frameworks and domestic-content rules will materially change project economics and supplier selection in 2026. Being early to adapt policy-compliance strategies is a competitive advantage.
Key dynamics shaping 2026 strategy
- Decarbonization meets resilience. Customers increasingly demand systems that combine renewable generation, storage and islanding capability — microgrids are being specified for energy security and emissions reduction simultaneously.
- Storage economics and installed cost pressure. Installed costs for commercial lithium-ion battery systems remain variable — industry benchmarks in 2025 range roughly $280–$580 per kWh depending on scope and complexity — keeping technology choice and procurement cadence central to project returns.
- Regulatory inflection points. National and state frameworks are pushing for standardized DER interconnection and enhanced demand-side management. Notably, U.S. Department of Energy grid code initiatives target 2026 implementation milestones that affect interconnection and operational dispatch.
- Local content and procurement friction. The Build America, Buy America regime introduces domestic-sourcing preferences for BESS and associated components, with limited non-availability waivers observed in 2026 — a decisive factor for suppliers and buyers concerned with contract compliance.
- Targeted public funding and incentive programs. Examples from 2024–2026 illustrate targeted funding streams and utility incentive envelopes that materially de-risk certain geographies and project archetypes. These programs are catalytic for developers who align go-to-market plans with program timelines.
- Technology layering and modularity. Solutions that combine modular hardware, standardized controls and cloud-native energy management are gaining preference among large C&I buyers and utilities for faster deployment and predictable O&M economics.
What PW Consulting’s report delivers (practical, actionable content)
The research is designed to be directly operationalizable by corporate strategy, BD, procurement and engineering teams. Highlights of the dataset and toolkit include:
Microgrid Market
- Robust market sizing and scenario models (historical 2020–2025; forecast 2026–2032) with configurable assumptions for technology cost curves, financing terms and policy levers.
- Bottom-up total cost of ownership templates and levelized energy/capacity models tailored to common microgrid architectures (grid-connected, off-grid, hybrid) — ready to be populated with tender-level quotes.
- Regulatory and incentive mapping that links program eligibility, procurement timelines and domestic-content obligations to project-level economic sensitivity analyses.
- Vendor benchmarking and capability matrices that score players on hardware, software, system integration, finance and lifecycle services — enabling rapid shortlisting for RFPs.
- Project-level pipeline intelligence and anonymized case studies that demonstrate procurement structures, commercial terms and risk allocation patterns actually used in the market.
- Playbooks for procurement, partnering and M&A — including integration checklists for digital platforms and commissioning/O&M handover templates to minimize lifecycle risk.
Competitive landscape: capabilities, moves and implications
The microgrid ecosystem is heterogeneous: large global OEMs, specialist storage vendors, systems integrators and software providers each own distinct value pools. Our assessment synthesizes capability sets and recent market moves to surface strategic implications for potential partners, suppliers and acquirers.
Microgrid Market
- Platform integrators and utilities-facing players (e.g., Schneider Electric, Siemens, ABB, Hitachi Energy). These firms compete on full-stack offerings — hardware, energy management platforms and services — and are positioned to win large commercial, industrial and utility-scale engagements where single-source accountability matters.
- Power electronics and modular system providers (e.g., Eaton, GE, S&C Electric). Their focus on modular, containerized architectures and rapid-deploy solutions appeals to industrial operators and utilities seeking standardized build-and-repeat models.
- Energy storage specialists (e.g., Tesla, Eos Energy, Bloom Energy). Vendors focused on battery chemistries or long-duration storage occupy the technology frontier. Strategic orders and repeat wins in 2025–2026 indicate a race to secure deployments that validate LDES and alternative chemistries at scale.
- Hybrid power and generator incumbents (e.g., Caterpillar). Legacy engine manufacturers are repositioning toward hybrid solutions combining gensets with renewables, often leveraging partnerships to enter data-center and industrial microgrid segments.
- Software and control specialists (e.g., Power Analytics, Honeywell). These companies capture disproportionate lifecycle value via controls, optimization and virtual power plant enablement; their software becomes a high-margin wedge in long-term contracts.
- Project developers and energy services firms (e.g., Ameresco, FlexGen). These players bridge finance, project development and O&M, offering packaged delivery models attractive to customers seeking single-contractor accountability.
Recent market evidence underscores these dynamics: zinc-based storage orders supporting commercial microgrids, large battery systems transacted to improve grid delivery, major partnerships for data-center independent energy solutions, and state-backed microgrid hub initiatives for disaster resilience. These transactions and programs are not isolated events — they illustrate how policy, procurement and technology advances are synchronizing to accelerate commercial adoption.
Strategic implications and recommendations for 2026
- Prioritize compliance with domestic-content rules early in supplier selection. Build America, Buy America constraints are a sourcing and schedule risk — resolve supplier qualification and waiver strategies before finalizing EPC contracts.
- Lock flexible procurement windows to capture falling storage installed costs without conceding excessive cost escalation risk on long-lead items.
- Lean into modular architectures and software-first controls to shorten deployment timelines and preserve upgrade pathways for evolving storage chemistries or grid services monetization.
- Use targeted public programs and utility incentives to derisk first-of-kind projects — aligning project schedules to program timelines can materially improve returns.
- Evaluate partnership models (licensing, white-label, JV) rather than purely organic build-outs — strategic alliances with technology owners or local integrators can accelerate market entry and provide local-compliance coverage.
- Design procurement contracts to shift performance risk appropriately: tie major payments to successful commissioning and verified islanding/black-start capabilities rather than equipment delivery alone.
- Consider M&A or minority investments in specialist storage or software providers to secure access to differentiated technologies and avoid supplier bottlenecks.
How PW Consulting supports your 2026 playbook
Our Microgrid Market report is engineered to be a decision-grade tool. It combines rigorous market sizing, transparent modeling assumptions, a curated project/transaction database, vendor scorecards and procurement playbooks. The full study includes the granular segment and regional splits, detailed company profiles, and downloadable financial models that executives and commercial teams can adapt to their specific investment cases.
For teams that need executable next steps in 2026 — from vendor shortlisting and contract terms to scenario-weighted capital planning and regulatory compliance checklists — PW Consulting offers bespoke advisory packages that operationalize the research into board-level decisions and tender-ready documents.
Microgrids are now a core element of strategic energy portfolios. The market momentum is clear and measurable; the choices companies make in 2026 about technology, partners and procurement models will define competitive positions for the next decade. Access the full report and models to move from high-level conviction to executable advantage.
For detailed analysis of this topic, please visit the official page: Microgrid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hardware Encryption Devices Market Poised for 9.6% CAGR Through 2032
By pmarketresearch, 2026-07-30
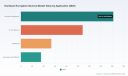
Hardware Encryption Devices Market: Strategic Briefing for 2026 Decision‑Makers
Executive preview — why this briefing matters to your 2026 agenda
As organisations accelerate digital transformation and regulatory scrutiny tightens, hardware encryption devices — from compact portable HSMs to enterprise-class modules — have moved from niche security tooling to core infrastructure. This PW Consulting briefing synthesises proprietary modelling and vendor intelligence to show where value will accrue through 2026 and beyond, and to frame the boardroom trade‑offs executives must resolve this year.
Hardware Encryption Devices Market
We adopt a “trailer” approach: this article presents high‑conviction, data‑driven insights and practical implications while intentionally withholding the granular, segment‑level tables and procurement tools that are available in the full report. Consider this an executive map: enough detail to shape policy and sourcing strategy; the full dataset and vendor scorecards are provided in the complete publication.
Hardware Encryption Devices Market
Market snapshot: trajectory, scale and concentration
PW Consulting’s baseline is 2025. Between 2020 and 2025 the market nearly doubled in scale, reflecting accelerated adoption across cloud, payments and regulated verticals. Our bottom‑up model establishes 2025 as the base year and projects the market forward through 2032 under multiple scenarios.
Hardware Encryption Devices Market
- The market exhibits structural momentum: our central forecast implies a mid‑single digit to low‑double digit compound expansion in the 2026–2032 window, driven by compliance refresh cycles, cloud migration of cryptographic workloads, and early enterprise investment in post‑quantum readiness.
- Under the central scenario the market grows at a compound annual rate of approximately 9.6% through the forecast window, more than offsetting near‑term supply adjustments and providing durable tailwinds for vendors that align product roadmaps with regulatory and cloud operator needs.
- Concentration is material: the top three vendors account for roughly two‑thirds of market revenue, and the top five represent over eighty percent. This structure creates clear leader advantages on scale, validation effort and ecosystem integration, while leaving pockets of opportunity for specialised challengers.
Industry dynamics shaping 2026 buying decisions
Four converging forces will dominate procurement and architecture decisions in 2026:
- Regulatory tightening. U.S. federal standards now require higher FIPS validation baselines for cryptographic modules, and industry‑specific standards (notably payments) have updated device requirements. These deadlines force a short, predictable vendor rationalisation and create a bifurcation between validated incumbents and those still on the compliance ladder.
- Standards and certification activity. New versions of payment‑centric HSM requirements and Common Criteria certifications in key jurisdictions have altered the compliance map. Organisations with cross‑border operations must overlay multiple certification requirements into a single procurement specification.
- Post‑quantum transition. Vendors are shipping post‑quantum algorithm support in firmware and appliance form factors; but readiness is uneven. The practical impact for 2026 is not immediate replacement but staged capability adoption tied to key lifecycle events (certificate renewals, PKI migration windows, cloud contract renewals).
- Infrastructure acceleration. Policy and permitting actions that speed data‑centre and edge deployments reduce lead times for appliance deployment and increase the value of scalable, multi‑tenant HSM platforms that can be deployed in hybrid environments.
Competitive landscape: who matters and why
The market is led by a group of established security vendors and a handful of specialised challengers. Our competitor analysis focuses on product differentiation, certification posture, cloud interoperability and commercial models.
- Thales Group (France) — Thales’ Luna series spans network, PCIe, USB and cloud‑native HSMs. Their roadmap emphasises validated modules, comprehensive key lifecycle tooling and an early, standardised approach to post‑quantum algorithms. Thales continues to prioritise enterprise and regulated use cases.
- Entrust Corporation (United States) — Entrust’s nShield family targets enterprise deployments with appliance and cloud options. Their focus on certified toolkits, developer SDKs and managed cryptographic services keeps them competitive in large corporate and government deals.
- Utimaco GmbH (Germany) — Utimaco positions its u.trust and CryptoServer lines as high‑assurance, multi‑tenant platforms with a strong emphasis on physical tamper resistance and compliance. Their recent product introductions and validation achievements make them a go‑to for the most demanding regulatory environments.
- Yubico (United States) — Yubico’s compact HSM offerings are designed for developer and edge scenarios where form factor and simplicity matter. They are an option where integration speed and portability trump scale.
- Futurex (United States) — Futurex provides enterprise HSMs and centralized key management with focus on payment and POS ecosystems and on integration with legacy estates.
- IBM Corporation (United States) — IBM brings quantum‑safe HSM solutions that blend classical cryptographic support with early post‑quantum algorithms, aimed at customers pursuing an explicit quantum migration roadmap.
- Atos SE (France) — Atos delivers secure HSM solutions focused on data protection and high assurance mission profiles, often bundled with broader data security services.
- Securosys SA (Switzerland) — Securosys offers Primus HSMs and cloud HSM services with attention to post‑quantum readiness and developer ergonomics for cloud operators and MSPs.
Recent vendor developments reinforce the competitive shape: multi‑tenant high‑assurance product launches, firmware releases standardising post‑quantum implementations, and ongoing updates to payment HSM requirements. Together these moves compress the window for evaluation and procurement in 2026.
What our full report contains — practical tools for 2026 execution
The full PW Consulting Hardware Encryption Devices Market study is built for practitioners and includes the following operational deliverables (summarised):
- Proprietary market model with historical reconciliation (2020–2025) and scenario forecasts to 2032, including sensitivity runs tied to regulatory and cloud adoption levers.
- Vendor scorecards assessing certifications, performance profiles, management ecosystems, cloud marketplace footprints and support models — designed to accelerate vendor short‑listing.
- Procurement playbooks and an RFP template keyed to multi‑jurisdiction compliance, performance SLAs and lifecycle migration clauses.
- Deployment blueprints for common migration paths (on‑prem to cloud HSM, appliance upgrade cycles, hybrid cryptographic fabrics), with sample timelines and cost buckets for CapEx/Opex trade‑offs.
- TCO and risk matrices that map certification gaps to remediation costs and implementation time — enabling procurement teams to stress‑test vendor proposals against compliance deadlines.
- Scenario planning and M&A briefing notes identifying consolidation vectors and potential targets for strategic buyers or partnerships.
We intentionally do not disclose granular segment splits or unit prices here: those model rows and downloadable templates are part of the complete report package designed to support procurement and security teams through RFP and integration phases.
Strategic implications for 2026 decision cycles
Based on our analysis, boards and CISOs should prioritise four near‑term decisions this year:
- Certification first: embed certification timelines (FIPS, PCI, Common Criteria) in all procurement and renewal decisions. For many buyers, a validated baseline by the end of 2026 materially reduces compliance risk and total cost of ownership over a three‑ to five‑year window.
- Adopt a hybrid posture: a mixed on‑prem and cloud HSM architecture balances regulatory constraints with operational agility. Shortlist vendors that provide validated cloud HSM offerings plus consistent tooling for key lifecycle management.
- Plan for quantum migration now, execute later: inventory cryptographic dependencies, prioritise critical assets for early post‑quantum protection, and align certificate renewal windows to minimise re‑encryption events.
- Vendor and ecosystem strategy: weigh the benefits of consolidation against the lock‑in risks of single‑vendor stacks. Given the market concentration dynamics, strategic partnerships or multi‑vendor strategies can preserve negotiating leverage while ensuring redundancy for high‑value keys.
Actionable next steps for 90‑day and 12‑month horizons
- 90 days: complete a validated inventory of HSM dependencies and certificate lifecycles; issue an RFP using our template to close gaps with at least two validated vendors.
- 6–12 months: finalise procurement with contractual certification commitments and migration milestones aligned to regulatory deadlines; pilot post‑quantum integrations in non‑production PKI streams.
- 12 months+: transition to an operational model that integrates HSM metrics into security KPIs and procurement scorecards, and evaluate consolidation or strategic partnership opportunities identified by the scenario analysis.
Conclusion — what to expect in 2026 and where PW Consulting adds value
Hardware encryption devices will remain a critical control point for enterprise security, regulated data protection and payments infrastructure through 2026 and beyond. The market’s projected trajectory and the evolving compliance landscape create windows of opportunity for disciplined buyers and well‑prepared vendors. PW Consulting’s full report provides the calibrated datasets, vendor evaluations and procurement tooling needed to turn that window into sustained advantage.
To access the complete market model, vendor scorecards, practical playbooks and downloadable RFP templates, please consult PW Consulting’s Hardware Encryption Devices Market report. The full package contains the granular segmentation analyses and supporting spreadsheets that operational teams require to execute with confidence.
For detailed analysis of this topic, please visit the official page: Hardware Encryption Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Environmental Test Chambers to hit USD 1,333.56M by 2032 at 3.8% CAGR
By pmarketresearch, 2026-07-30
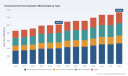
Environmental Test Chambers Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused strategic preview of our full Environmental Test Chambers Market study. This briefing synthesizes the market’s recent trajectory, emergent regulatory and technology drivers, competitive positioning, and the practical playbooks executives will need to act decisively in 2026. Consider this a high-fidelity trailer: we expose the contours, the levers, and the inflection points — while reserving the granular segmentation maps and proprietary scenario outputs for the full report.
Environmental Test Chambers Market
Why this market matters for 2026
Environmental test chambers are no longer niche capital equipment. They sit at the intersection of regulatory compliance, product reliability, and sustainability commitments across automotive, aerospace, electronics, medical/pharma, and industrial sectors. Between 2020 and 2025 the market expanded steadily, and by the 2025 base year it surpassed the billion-dollar threshold in USD (revenue unit: Million). From that position, our forecast for 2026–2032 projects a compound annual growth rate (CAGR) of 3.8%, implying a meaningful expansion by the end of the forecast window.
Environmental Test Chambers Market
For corporate leaders planning CapEx, R&D roadmaps, or M&A in 2026, this growth trajectory signals two things simultaneously: (1) continued demand stability driven by compliance and quality assurance requirements; and (2) pockets of accelerated opportunity tied to electrification, data-center thermal stress testing, and sustainability-driven product redesign. Capturing those pockets requires calibrated strategy rather than blunt investment.
Environmental Test Chambers Market
Market dynamics shaping strategic choices
- Regulatory tightening and test procedural updates: Recent standards updates (including revised dry-heat procedures and added mechanical hammer tests under the environmental testing standards framework) raise the technical floor for compliance. Buyers must anticipate evolving test protocols when specifying equipment — otherwise they risk premature obsolescence of chamber fleets and downstream revalidation costs.
- Energy, refrigerant and sustainability pressure: Suppliers and end-users are shifting toward low-GWP refrigerants such as CO2 (R744) and rethinking thermal system architectures. This transition affects procurement total cost of ownership (TCO), maintenance skill sets, and supply-chain sourcing strategies for compressors and heat exchangers.
- Application-driven complexity: Demand profiles are increasingly heterogeneous. Battery safety, HALT/HASS, server-heat-load simulations, and walk-in qualification environments each require differentiated performance, instrumentation, and services. This fragmentation rewards vendors that combine product modularity with field service depth.
- Consolidation and concentration: The market shows a moderate concentration profile among leading vendors, indicating that while top-tier suppliers capture significant share, specialized and regional players still control meaningful niches. That balance creates options for OEMs to form strategic supplier partnerships or pursue tuck-in acquisitions to rapidly build capabilities.
Competitive landscape — who matters and why
Our market coverage includes global platform leaders and focused specialists. Each incumbent brings a distinct strategic posture that will influence partnership, procurement, and M&A choices in 2026:
- Weiss Technik (Germany) — Broadest portfolio across compact reach-in to full walk-in and drive-in models, including integrated multi-phenomenon capabilities (thermal, humidity, altitude, vibration, shock). Strategic implication: ideal primary-supplier candidate for large program integrators seeking single-vendor validation environments.
- ESPEC Corporation (Japan) — Deep specialization in environmental simulation, HALT/HASS platforms, and now higher-capacity walk-in systems targeting server heat loads. Strategic implication: strong partner for data-center thermal management labs and high-heat-density OEMs.
- Thermotron Industries (United States) — Established U.S. footprint with a full range of temperature, humidity, altitude and vibration chambers. Strategic implication: preferred supplier for North American manufacturers prioritizing local support and regulatory alignment.
- KOMEG Technology (China) — Competency in both standard and custom climatic and battery-safety chambers, plus early adoption of CO2 refrigerant options. Strategic implication: competitive source for cost-sensitive programs and rapid customization cycles, particularly where sustainability refrigerant transition is a procurement objective.
- BINDER GmbH (Germany) — Focus on dynamic climate chambers and simulation models used for materials and function testing. Strategic implication: strong in laboratory-grade precision applications where repeatability is a premium.
- Cincinnati Sub-Zero Products (U.S.) — Offers broad portfolio of standard and custom-designed chambers and emphasizes industrial-grade reliability. Strategic implication: attractive for long-life capital programs with high uptime requirements.
- Angelantoni Test Technologies (Italy) — Strong aerospace and automotive application pedigree. Strategic implication: partner of choice for programs with tight qualification regimes and aerospace-derived test protocols.
- Memmert GmbH + Co. KG (Germany) — Known for IEC-compliant climate chambers with a reputation for precision in temperature and humidity control. Strategic implication: suited to lab and compliance environments where standards traceability is critical.
These vendor profiles are mapped in the full report against capability matrices (product breadth, customization speed, service network, refrigerant options, compliance readiness) to support supplier selection and sourcing optimization. We intentionally withhold the detailed vendor scoring matrices here to preserve the incentive to access the full analysis.
Recent developments to watch
- ESPEC’s late-2025 launch of high heat-load walk-in chambers for server simulation underscores a rising opportunity tied to data-center and telecom thermal testing.
- Weiss Technik’s Endurance Series rollout (2024) and several new product introductions across other vendors reflect an emphasis on higher-throughput, energy-efficient chambers.
- Regional investments in lab capacity — exemplified by new environmental test facilities in India — show how local testing-as-a-service ecosystems can accelerate qualification timelines for regional OEMs and reduce logistical friction.
- Claims of enhanced measurement accuracy and wide-climate compatibility from niche vendors point to increasing competition on test precision and instrumentation rather than pure temperature/humidity range alone.
What PW Consulting’s full report delivers (practical tools for 2026)
Our full Environmental Test Chambers Market report is organized to convert insight into action. Highlights include:
- Proprietary market sizing and demand scenarios (2020–2032), with sensitivity analysis for regulation and refrigerant transition assumptions.
- Competitive benchmarking and vendor selection frameworks tailored to buyer archetypes (e.g., high-throughput OEM, lab network operator, regulated pharma developer).
- CapEx vs. TCO calculators that incorporate energy, refrigerant lifecycle costs, and projected compliance upgrade timelines for 2026–2030.
- Service and aftermarket strategy playbooks — including field service network design, predictive maintenance KPIs, and spare-parts inventory models.
- M&A screening templates and 100+ target profiles for bolt-ons that accelerate capability (e.g., HALT/HASS, battery safety instrumentation, CO2 systems).
- Procurement-ready RFP templates and technical specification checklists aligned to the latest test standards and refrigerant options.
- Case studies that show path-to-value for players who pursued platform consolidation, lab-as-a-service expansion, or localized manufacturing in 2024–2025.
These deliverables are built for rapid uptake: executive summaries for board-level decisions, implementation roadmaps for operations teams, and technical annexes for engineering procurement.
Strategic recommendations for 2026 planning cycles
- Reassess capital replacement timelines to reflect updated standards and refrigerant transitions. Reprofiling depreciation schedules and retrofit windows can unlock short-term budget relief while avoiding mid-term compliance risk.
- Prioritize modularity and serviceability in procurement specifications. Vendors that offer instrument-level interchangeability and clear retrofit paths reduce lifecycle disruption and TCO.
- Invest selectively in lab-as-a-service or regional partnerships where market access and test-throughput bottlenecks exist. Outsourcing to accredited facilities can be cheaper and faster than in-house scale-up when qualification speed is strategic.
- For strategic buyers, consider tuck-in acquisitions focused on HALT/HASS, battery-safety specialization, or refrigerant transition expertise to gain capability quickly without retooling legacy platforms.
- Embed energy and refrigerant metrics into supplier scorecards. Performance on low-GWP refrigerants, energy efficiency, and compliance documentation increasingly factor into procurement decisions and ESG reporting.
Concluding note — the window for decisive action
The environmental test chamber market presents a mix of steady baseline demand and high-value pockets arising from technological and regulatory shifts. With a base-year market north of the billion-dollar mark and a multi-year CAGR in the mid-single digits, 2026 is a window for strategic repositioning — not merely incremental procurement. PW Consulting’s full report equips leadership teams with the tactical instruments to choose the right suppliers, structure service ecosystems, and target investments that will deliver measurable ROI through 2032.
To access the detailed segmentation, vendor scorecards, and scenario-model outputs that underpin these insights, please consult the full Environmental Test Chambers Market report on our publications page. The granular intelligence in that document is intentionally gated to ensure decision advantage for subscribers and clients ready to move in 2026.
For detailed analysis of this topic, please visit the official page: Environmental Test Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
SME Insurance Market Poised for 6.52% CAGR Through 2032 — PW Consulting Insights
By pmarketresearch, 2026-07-30
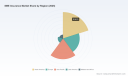
SME Insurance Market 2026 — Strategic Preview for Executive Decision-Making
As PW Consulting’s flagship market intelligence for the SME Insurance Market, this brief previews the strategic value contained in our full 2026 study. Built on a 2025 base year with a historical lens from 2020–2025 and forward-looking forecasts through 2032, the market is projected to continue expanding at a compound annual growth rate of 6.52%. After rising from under USD 90 billion in 2020 to roughly USD 113 billion in 2025, our 2026 estimate moves the industry past USD 120 billion and the forecast reaches the high‑hundreds of billions by 2032. These topline dynamics are a starting point, not an endpoint: the practical utility for 2026 strategy lies in the interplay of growth vectors, regulatory inflection points, evolving distribution economics and competitive positioning — all explored at operational depth in the full report.
SME Insurance Market
Why this study matters for 2026 strategic choices
- Timing matters: 2026 is a crossroads for SME insurers and their partners. The market’s steady mid‑single digit CAGR masks rapid change beneath the surface — digital distribution, cyber risk accumulation, and new regulatory transparency requirements are reconfiguring product design and go‑to‑market models.
- Decision leverage: Insurers, brokers, insurtechs and private investors need forwardable insight that converts into specific 12‑ to 36‑month actions: where to invest in underwriting capability, which partnerships to prioritize, how to adapt pricing and capital models for emerging liabilities, and where consolidation will materially change competitive dynamics.
- Operational focus: Beyond high‑level forecasts, this study emphasizes executable items — segment‑level profit pools, distribution economics by channel, and modelled scenarios demonstrating how regulatory changes and claims inflation translate into premium and loss‑ratio outcomes for SMEs.
Macro trajectory and what it implies
From a macro standpoint, the SME insurance market’s recovery and growth since 2020 reflect both cyclical and structural forces. The aggregate market expanded from approximately USD 89.5 billion in 2020 to USD 113.2 billion in 2025; our projection places the market north of USD 170 billion by 2032 under the central 6.52% CAGR case. That trajectory signals a market large enough to sustain differentiated players while still leaving room for rapid share shifts through digital innovation, product bundling, and specialization.
SME Insurance Market
Interpretation for 2026 strategy:
SME Insurance Market
- Scale remains a competitive advantage but not an absolute barrier. Firms with focused propositions and superior distribution can carve out high‑margin niches even in a consolidating market.
- Investment timing is critical. With a steady growth baseline, 2026 should be used to deploy capability upgrades (data, automation, cyber underwriting) that pay back over the next three years as new exposures and regulations crystallize.
- Scenario planning beats point forecasts. Hedge strategies and capital allocation should be stress‑tested against plausible regulatory changes and cascade risks (e.g., large cyber events affecting SME supply chains).
Competitive landscape — capability contrasts and strategic implications
The competitive topography is a mix of large multiline carriers, global brokers, and fast‑moving digital platforms. Market concentration metrics show a moderate level of leader advantage: the top three entities account for just over 31% of the market, while the top five approach nearly 48%. This fragmentation-plus-concentration pattern produces distinct opportunities across scale, specialization and distribution innovation.
- Chubb Limited (Zürich) — Known for a full suite of SME products, Chubb combines underwriting depth with risk engineering and a strong wholesale and retail distribution footprint. Its value proposition emphasizes breadth of cover, tailored solutions for small‑to‑mid enterprises and workplace risk services. Strategic takeaway: carriers that can couple technical underwriting with service‑led differentiation will sustain higher retention and margin in the next two years.
- Marsh & McLennan Companies, Inc. (New York) — As a global broker and advisory, Marsh leverages consultative relationships with independent and fast‑growing SMEs. Their scale in advisory, claims advocacy and portfolio analytics positions them to monetize risk management services alongside placement. Strategic takeaway: brokers that embed data analytics and advisory into standard SME offerings will capture higher wallet share and improve loss outcomes for partners.
- Simply Business (Boston) — A digitally native platform focused on small business distribution, Simply Business has accelerated its product innovation and ecosystem plays. Recent moves in 2026 — a ChatGPT‑integrated insurance app and a renewed SMB grant initiative — underscore a shift toward embedded, conversational commerce and community engagement. The company’s insurtech award in April 2026 confirms market recognition of its model. Strategic takeaway: digital platforms that couple conversational UX, streamlined purchase flows and partnerships with carriers will shift marginal distribution economics in their favor.
Regulatory and policy dynamics that will shape 2026 decisions
Regulatory change is a live input into strategic planning for the SME insurance market. Three developments deserve executive attention:
- Labor and benefits reporting dynamics — Recent government reporting underscores the scale and opacity of employer‑sponsored plans. This reinforces the need for insurers and brokers to build transparency tools and compliance workflows into SME benefit offerings.
- Transparency in Coverage (Dec 2025 federal rule changes) — Rules affecting disclosures for group health plans coming into effect in 2027 will alter quoting, renewals and customer communications for advisors and insurers serving SMEs. Firms must update systems to surface the mandated data points and to reframe value propositions around compliance‑enabled transparency.
- Proposed Medicare/Medicaid cost‑sharing disclosures (CMS‑9882‑P) — New disclosure obligations for 2027 plan years heighten the operational burden for insurers and employers. There is a short runway to ensure systems, contracts, and client communications reflect these requirements without disrupting renewals in 2027–2028.
Practically, this means 2026 should be the year for capability investment in compliance automation and data pipelines that convert regulatory reporting into client value propositions, not just a back‑office cost center.
What the full PW Consulting study delivers (practical content highlights)
- Market sizing and forecasts by year (2020–2032) with scenario variance and sensitivity to loss trends and economic cycles.
- Granular segmentation across regions, product types and end‑use applications — presented as profit‑pool maps and actionable go‑to‑market playbooks. (Note: detailed segment tables are intentionally withheld in this preview.)
- Competitive scorecards with capability matrices — distribution reach, digital maturity, product breadth, and claims servicing benchmarks for key incumbents and challengers.
- Regulatory impact models — quantifying the operational cost and premium implications of imminent disclosure and reporting rules, plus remediation roadmaps.
- Underwriting and pricing levers — data‑led approaches to refine risk selection for cyber exposures, professional liability, and combined product bundles tailored to SMEs.
- Actionable M&A and partnership pipeline — prioritized targets, valuation ranges and integration checklists for carriers and platforms looking to scale fast.
- Tools and annexes — downloadable models, assumption workbooks and a methodology appendix to enable in‑house stress testing.
How executives should use this intelligence in 2026
- Carriers: Prioritize capability investments that improve loss recognition and enable dynamic pricing — cyber and professional liability underwriting engines should be operational within 12–18 months to protect margin.
- Brokers and MGAs: Convert advisory relationships into subscription revenue by packaging compliance assistance and employee‑benefit transparency tools tied to the new disclosure rules.
- Insurtechs and platforms: Accelerate UX investments that lower time‑to‑bind and embed conversational AI where it measurably increases conversion — the Simply Business app launch in May 2026 is an industry signal that buyers expect conversational purchasing journeys.
- Private investors: Use the mid‑market concentration pattern to target rollups of regional specialists or digital distributors that can be scaled through standardization of underwriting and distribution tech stacks.
- SME decision‑makers: Demand transparency and bundled risk management services; firms that reduce administrative friction around benefits and regulatory reporting will win SME loyalty.
Final note — what this preview hides (and why)
This article is a strategic preview designed to communicate the depth and practical orientation of the PW Consulting SME Insurance Market study while preserving the report’s proprietary granularity. The full report contains the detailed regional and product splits, competitor market shares by segment, price‑and‑loss benchmarks, and the downloadable financial models that will enable concrete action. Those detailed tables and modelled outputs are intentionally omitted from this summary to encourage direct access to the report itself, where PW Consulting provides the complete intelligence package.
For teams making 2026 decisions — whether reallocating underwriting capital, executing bolt‑on M&A, or building out digital distribution — the full report delivers the market‑calibrated insights and executable roadmaps necessary to move from strategy to operational change. Visit our full SME Insurance Market research page to unlock the complete data annex, competitor scorecards and the scenario modelling workbook that will turn this strategic preview into a 2026 action plan.
For detailed analysis of this topic, please visit the official page: SME Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com