

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Environmental Test Chambers to hit USD 1,333.56M by 2032 at 3.8% CAGR

Environmental Test Chambers Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a focused strategic preview of our full Environmental Test Chambers Market study. This briefing synthesizes the market’s recent trajectory, emergent regulatory and technology drivers, competitive positioning, and the practical playbooks executives will need to act decisively in 2026. Consider this a high-fidelity trailer: we expose the contours, the levers, and the inflection points — while reserving the granular segmentation maps and proprietary scenario outputs for the full report.
Environmental Test Chambers Market
Why this market matters for 2026
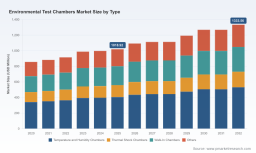
Environmental test chambers are no longer niche capital equipment. They sit at the intersection of regulatory compliance, product reliability, and sustainability commitments across automotive, aerospace, electronics, medical/pharma, and industrial sectors. Between 2020 and 2025 the market expanded steadily, and by the 2025 base year it surpassed the billion-dollar threshold in USD (revenue unit: Million). From that position, our forecast for 2026–2032 projects a compound annual growth rate (CAGR) of 3.8%, implying a meaningful expansion by the end of the forecast window.
Environmental Test Chambers Market
For corporate leaders planning CapEx, R&D roadmaps, or M&A in 2026, this growth trajectory signals two things simultaneously: (1) continued demand stability driven by compliance and quality assurance requirements; and (2) pockets of accelerated opportunity tied to electrification, data-center thermal stress testing, and sustainability-driven product redesign. Capturing those pockets requires calibrated strategy rather than blunt investment.
Environmental Test Chambers Market
Market dynamics shaping strategic choices
- Regulatory tightening and test procedural updates: Recent standards updates (including revised dry-heat procedures and added mechanical hammer tests under the environmental testing standards framework) raise the technical floor for compliance. Buyers must anticipate evolving test protocols when specifying equipment — otherwise they risk premature obsolescence of chamber fleets and downstream revalidation costs.
- Energy, refrigerant and sustainability pressure: Suppliers and end-users are shifting toward low-GWP refrigerants such as CO2 (R744) and rethinking thermal system architectures. This transition affects procurement total cost of ownership (TCO), maintenance skill sets, and supply-chain sourcing strategies for compressors and heat exchangers.
- Application-driven complexity: Demand profiles are increasingly heterogeneous. Battery safety, HALT/HASS, server-heat-load simulations, and walk-in qualification environments each require differentiated performance, instrumentation, and services. This fragmentation rewards vendors that combine product modularity with field service depth.
- Consolidation and concentration: The market shows a moderate concentration profile among leading vendors, indicating that while top-tier suppliers capture significant share, specialized and regional players still control meaningful niches. That balance creates options for OEMs to form strategic supplier partnerships or pursue tuck-in acquisitions to rapidly build capabilities.
Competitive landscape — who matters and why
Our market coverage includes global platform leaders and focused specialists. Each incumbent brings a distinct strategic posture that will influence partnership, procurement, and M&A choices in 2026:
- Weiss Technik (Germany) — Broadest portfolio across compact reach-in to full walk-in and drive-in models, including integrated multi-phenomenon capabilities (thermal, humidity, altitude, vibration, shock). Strategic implication: ideal primary-supplier candidate for large program integrators seeking single-vendor validation environments.
- ESPEC Corporation (Japan) — Deep specialization in environmental simulation, HALT/HASS platforms, and now higher-capacity walk-in systems targeting server heat loads. Strategic implication: strong partner for data-center thermal management labs and high-heat-density OEMs.
- Thermotron Industries (United States) — Established U.S. footprint with a full range of temperature, humidity, altitude and vibration chambers. Strategic implication: preferred supplier for North American manufacturers prioritizing local support and regulatory alignment.
- KOMEG Technology (China) — Competency in both standard and custom climatic and battery-safety chambers, plus early adoption of CO2 refrigerant options. Strategic implication: competitive source for cost-sensitive programs and rapid customization cycles, particularly where sustainability refrigerant transition is a procurement objective.
- BINDER GmbH (Germany) — Focus on dynamic climate chambers and simulation models used for materials and function testing. Strategic implication: strong in laboratory-grade precision applications where repeatability is a premium.
- Cincinnati Sub-Zero Products (U.S.) — Offers broad portfolio of standard and custom-designed chambers and emphasizes industrial-grade reliability. Strategic implication: attractive for long-life capital programs with high uptime requirements.
- Angelantoni Test Technologies (Italy) — Strong aerospace and automotive application pedigree. Strategic implication: partner of choice for programs with tight qualification regimes and aerospace-derived test protocols.
- Memmert GmbH + Co. KG (Germany) — Known for IEC-compliant climate chambers with a reputation for precision in temperature and humidity control. Strategic implication: suited to lab and compliance environments where standards traceability is critical.
These vendor profiles are mapped in the full report against capability matrices (product breadth, customization speed, service network, refrigerant options, compliance readiness) to support supplier selection and sourcing optimization. We intentionally withhold the detailed vendor scoring matrices here to preserve the incentive to access the full analysis.
Recent developments to watch
- ESPEC’s late-2025 launch of high heat-load walk-in chambers for server simulation underscores a rising opportunity tied to data-center and telecom thermal testing.
- Weiss Technik’s Endurance Series rollout (2024) and several new product introductions across other vendors reflect an emphasis on higher-throughput, energy-efficient chambers.
- Regional investments in lab capacity — exemplified by new environmental test facilities in India — show how local testing-as-a-service ecosystems can accelerate qualification timelines for regional OEMs and reduce logistical friction.
- Claims of enhanced measurement accuracy and wide-climate compatibility from niche vendors point to increasing competition on test precision and instrumentation rather than pure temperature/humidity range alone.
What PW Consulting’s full report delivers (practical tools for 2026)
Our full Environmental Test Chambers Market report is organized to convert insight into action. Highlights include:
- Proprietary market sizing and demand scenarios (2020–2032), with sensitivity analysis for regulation and refrigerant transition assumptions.
- Competitive benchmarking and vendor selection frameworks tailored to buyer archetypes (e.g., high-throughput OEM, lab network operator, regulated pharma developer).
- CapEx vs. TCO calculators that incorporate energy, refrigerant lifecycle costs, and projected compliance upgrade timelines for 2026–2030.
- Service and aftermarket strategy playbooks — including field service network design, predictive maintenance KPIs, and spare-parts inventory models.
- M&A screening templates and 100+ target profiles for bolt-ons that accelerate capability (e.g., HALT/HASS, battery safety instrumentation, CO2 systems).
- Procurement-ready RFP templates and technical specification checklists aligned to the latest test standards and refrigerant options.
- Case studies that show path-to-value for players who pursued platform consolidation, lab-as-a-service expansion, or localized manufacturing in 2024–2025.
These deliverables are built for rapid uptake: executive summaries for board-level decisions, implementation roadmaps for operations teams, and technical annexes for engineering procurement.
Strategic recommendations for 2026 planning cycles
- Reassess capital replacement timelines to reflect updated standards and refrigerant transitions. Reprofiling depreciation schedules and retrofit windows can unlock short-term budget relief while avoiding mid-term compliance risk.
- Prioritize modularity and serviceability in procurement specifications. Vendors that offer instrument-level interchangeability and clear retrofit paths reduce lifecycle disruption and TCO.
- Invest selectively in lab-as-a-service or regional partnerships where market access and test-throughput bottlenecks exist. Outsourcing to accredited facilities can be cheaper and faster than in-house scale-up when qualification speed is strategic.
- For strategic buyers, consider tuck-in acquisitions focused on HALT/HASS, battery-safety specialization, or refrigerant transition expertise to gain capability quickly without retooling legacy platforms.
- Embed energy and refrigerant metrics into supplier scorecards. Performance on low-GWP refrigerants, energy efficiency, and compliance documentation increasingly factor into procurement decisions and ESG reporting.
Concluding note — the window for decisive action
The environmental test chamber market presents a mix of steady baseline demand and high-value pockets arising from technological and regulatory shifts. With a base-year market north of the billion-dollar mark and a multi-year CAGR in the mid-single digits, 2026 is a window for strategic repositioning — not merely incremental procurement. PW Consulting’s full report equips leadership teams with the tactical instruments to choose the right suppliers, structure service ecosystems, and target investments that will deliver measurable ROI through 2032.
To access the detailed segmentation, vendor scorecards, and scenario-model outputs that underpin these insights, please consult the full Environmental Test Chambers Market report on our publications page. The granular intelligence in that document is intentionally gated to ensure decision advantage for subscribers and clients ready to move in 2026.
For detailed analysis of this topic, please visit the official page: Environmental Test Chambers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com