

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Industrial CT Market to Hit USD 775 Million by 2032 at 7.5% CAGR - PW Consulting

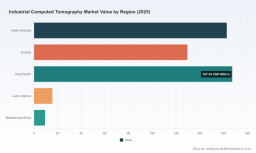
Industrial Computed Tomography Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As industrial supply chains and quality regimes demand ever-greater insight into internal geometries, the Industrial Computed Tomography (CT) market has moved from an R&D niche to a production-critical capability. PW Consulting’s latest study (base year 2025) finds a robust, sustained expansion trajectory for the sector — underpinned by a 7.5% compound annual growth rate (CAGR) through the forecast window (2026–2032). The market has grown from roughly USD 380 Million in 2020 to approximately USD 485 Million in 2025, and our modelling points to continued momentum toward an estimated USD 775 Million by 2032 (all values USD Million).
Industrial Computed Tomography Market
This briefing distills the research’s strategic utility for corporate leaders planning capital allocation, product roadmaps, M&A activity, and operational deployment in 2026 — while deliberately omitting the granular segmentation tables contained in the full report to preserve its lead-generation purpose.
Industrial Computed Tomography Market
Why this matters in 2026: three strategic inflection points
-
From inspection to assurance: Industrial CT is shifting from episodic laboratory use to embedded quality infrastructure. As manufacturers face regulatory and contractual pressures for “zero-defect” outcomes — notably in aerospace and automotive — CT is becoming an integral inspection stage rather than an occasional diagnostic tool.
Industrial Computed Tomography Market -
Software and AI are the multiplier: hardware improvements remain important, but value capture increasingly flows to software — reconstruction algorithms, AI-driven defect classification, and metrology suites that convert scans into actionable control limits.
-
New production paradigms increase internal-complexity testing needs: the rise of additive manufacturing (AM) and complex multi-material assemblies creates inspection demand that only volumetric imaging can satisfy reliably and at scale.
Market trajectory: context and implications
Our historical series (2020–2025) shows steady expansion, with a notable acceleration into 2024–2025 as OEMs and contract manufacturers formalized CT workflows. Projected growth under a 7.5% CAGR leads to meaningful market enlargement across 2026–2032. For 2026 specifically, buyers should assume continued price-performance improvements in both detectors and reconstruction software, with service models (on-site, captive lab, and remote-as-a-service) maturing rapidly.
From a competitive structure perspective, concentration is moderate: the top three vendors account for roughly one-third of the market and the top five approach the low-forties (CR3 ≈ 35%; CR5 ≈ 42%). This combination of significant incumbents and a broad long tail creates both acquisition opportunities and price competition for differentiated, software-led offerings.
What the full report contains (practical, actionable deliverables)
- Market sizing and topline forecasts (2020–2032) with scenario sensitivity for hardware price deflation and AI-software uptake.
- Go-to-market playbooks for vendor types: OEM hardware manufacturers, software analytics firms, and inspection-as-a-service providers — including suggested sales motions, channel mixes, and sample ROI models for common buyer personas.
- Technology deep dives: comparative analysis of detector technologies, X‑ray sources, reconstruction pipelines, and metrology integrations — with implications for throughput, accuracy, and cost-per-part.
- Regulatory and standards assessment: implications of EN ISO 15708-3:2025 and related guidance for operationalization, qualification, and auditability of CT-derived results.
- Capability gap analysis for major OEMs and prospects: operational readiness checklists and prioritized investments to move from pilot projects to production-level inspection.
- Strategic M&A and partnership mapping: high-opportunity targets by capability (AI analytics, specialty CT hardware, volumetric metrology) and a valuation sensitivity framework keyed to recurring revenue adoption.
- Executive decision support tools: CapEx phasing templates, a 24-month implementation playbook for internal CT labs, and procurement scorecards for vendor selection.
Note: the report intentionally withholds granular segmentation tables in this public summary. Subscribers and licensed clients receive detailed region-, type-, and application-level breakdowns, including modeled adoption curves and pricing elasticity matrices.
Competitive landscape: profiles and strategic postures
The market features a mix of long-standing industrial metrology firms, specialized radiography OEMs, and agile entrants focusing on affordability and AI. Below we highlight the strategic positioning of prominent players covered in the study and what each move implies for 2026 decision-makers.
-
Waygate Technologies (Houston, TX) — Strengths: legacy footprint in industrial radiography, broad service capabilities, and Phoenix-series systems tuned for non-destructive metrology and in-line process control. Strategic posture: leveraging service contracts and integrated systems to defend installed-base revenue. Implication: suppliers and buyers should expect bundled hardware-plus-services offers that prioritize uptime and traceable inspection chains.
-
Nikon Metrology (Milton Keynes, UK) — Strengths: wide product range spanning large-envelope CT to microfocus systems and a reputation in precision metrology. Recent move: June 2025 VOXLS 20 C 225 product launch, emphasizing a metrology-grade platform optimized for electronics, AM, aerospace and medical inspection. Implication: product launches like this compress the timeline for qualification in regulated industries and raise the bar on metrology accuracy expectations.
-
ZEISS (Oberkochen, Germany) — Strengths: premium metrology systems and strong software (INSPECT) integration for dimensional control and defect detection. Recent presence at EASTEC 2025 shows continued investment in trade-level visibility. Implication: ZEISS will remain a go-to choice where precision and software ecosystem depth trump unit price.
-
Werth Messtechnik (Wetzlar, Germany) — Strengths: hybrid CT-plus-coordinate-measuring-machine integrations for manufacturers that require direct metrology workflows. Implication: attractive for manufacturers seeking to collapse inspection steps and reduce measurement uncertainty transfer between systems.
-
North Star Imaging (Rogers, MN) — Strengths: focused systems portfolio for 2D/3D radiography with strong NDT pedigree. Implication: appeals to test labs and industrial NDT buyers valuing fast throughput and rugged field-capable systems.
-
Lumafield (United States) — Strengths: disruptive product architecture (affordable Neptune CT) and an AI-first analytics suite (Voyager) targeting office- and lab-based high-resolution inspection. Implication: such entrants accelerate democratization of CT and force incumbents to respond on software, pricing, and ease-of-use.
Dynamics, standards and regulatory lens
EN ISO 15708-3:2025 establishes clearer expectations for operation, image interpretation, defect detection, and result reliability in industrial CT. For procurement and compliance officers, this standard will shortly become a de facto checklist item for supplier qualification in regulated sectors. Simultaneously, macro drivers — widespread adoption of CT for flaw detection, the inspection demands of additive manufacturing, and regulatory pressure for zero-defect production — are creating predictable pockets of demand.
From a risk perspective, two dynamics deserve attention in 2026:
- Operationalizing standard-compliant workflows will require investments in operator training, validated software toolchains, and audit-grade documentation — not just hardware.
- As software becomes the differentiator, IP and data-security questions rise: scanned volumetric datasets are sensitive, often containing proprietary geometry; secure data pipelines and SaaS governance will be procurement decision criteria.
Strategic recommendations for 2026
-
Prioritize software-enabled differentiation: If you are a vendor, invest at least proportionally more in AI-enabled analysis, cloud-enabled workflow orchestration, and tight metrology integrations than in incremental hardware refinements.
-
Adopt a staged CapEx approach: Buyers should pilot CT in critical product lines (flight-critical, safety, or high-cost rework) before scaling. Use modular acquisition and shared-lab models to lower time-to-value.
-
Prepare for standards-led procurement: Update supplier RFPs and qualification checklists to reflect EN ISO 15708-3:2025 requirements, including traceability, operator competency, and software validation evidence.
-
Consider M&A selectively: For incumbents seeking rapid expansion into software or service models, bolt-on acquisitions of AI analytics specialists or regional service labs offer faster capability delivery than in-house development.
-
Lock down data governance and SaaS security: For providers of cloud-based reconstruction and analytics, SOC-type certifications and contractual protections around scan data will be decisive competitive differentiators.
How PW Consulting helps
Our full Industrial CT market research provides the actionable elements procurement teams, R&D leaders, and corporate development functions need to make defensible 2026 decisions: validated financial models, procurement scorecards, go-to-market playbooks, and a prioritized list of tactical investments to accelerate production readiness. This public briefing demonstrates the logic and strategic direction; the licensed report contains the granular segmentation, regional adoption curves, and per-application demand matrices that underpin executable plans.
Call to action
Leaders preparing 2026 budgets should treat this market as a near-term capability lever rather than a distant technology bet. Contact PW Consulting to access the full report, receive a tailored executive briefing, or engage our readiness workshop to translate the findings into a 12–24 month implementation roadmap aligned to your product lines and regulatory footprint.
For detailed analysis of this topic, please visit the official page: Industrial Computed Tomography Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com