

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Microgrid Market to Reach USD 83,000 Million by 2032 at 17.5% CAGR

Microgrid Market — 2026 Strategic Preview
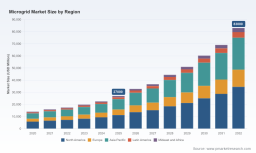
As global energy systems pivot toward resilience, decarbonization and distributed intelligence, microgrids are moving from niche pilot projects to strategic infrastructure assets. PW Consulting’s Microgrid Market study (base year 2025; figures in USD Million) quantifies that transition and translates it into practical guidance for executives planning capital allocation, procurement and partnership strategies in 2026. The market trajectory is unambiguous: from roughly USD 14.0 billion in 2020 to USD 27.0 billion in 2025, and accelerating into the forecast horizon — the market is projected to surpass USD 32.8 billion in 2026 and to approach USD 83.0 billion by 2032, reflecting a compound annual growth rate of 17.5% for the forecast period.
Microgrid Market
Why this report matters for 2026 decision-makers
- Timing: The near-term inflection in 2026 creates a narrow window where technology choices, sourcing commitments and enabling contracts lock in returns over multi-decade project lives.
- Risk-to-reward calibration: Rapid growth increases both upside and operational complexity — executives must reconcile capex timing with evolving regulation and supply-chain constraints.
- Competitive positioning: A moderate level of market concentration (CR3 ≈ 35.2%; CR5 ≈ 45.1%) means incumbent scale matters, but there is ample opportunity for specialist players and new entrants with focused value propositions.
- Policy arbitrage: Incentive programs, interconnection frameworks and domestic-content rules will materially change project economics and supplier selection in 2026. Being early to adapt policy-compliance strategies is a competitive advantage.
Key dynamics shaping 2026 strategy
- Decarbonization meets resilience. Customers increasingly demand systems that combine renewable generation, storage and islanding capability — microgrids are being specified for energy security and emissions reduction simultaneously.
- Storage economics and installed cost pressure. Installed costs for commercial lithium-ion battery systems remain variable — industry benchmarks in 2025 range roughly $280–$580 per kWh depending on scope and complexity — keeping technology choice and procurement cadence central to project returns.
- Regulatory inflection points. National and state frameworks are pushing for standardized DER interconnection and enhanced demand-side management. Notably, U.S. Department of Energy grid code initiatives target 2026 implementation milestones that affect interconnection and operational dispatch.
- Local content and procurement friction. The Build America, Buy America regime introduces domestic-sourcing preferences for BESS and associated components, with limited non-availability waivers observed in 2026 — a decisive factor for suppliers and buyers concerned with contract compliance.
- Targeted public funding and incentive programs. Examples from 2024–2026 illustrate targeted funding streams and utility incentive envelopes that materially de-risk certain geographies and project archetypes. These programs are catalytic for developers who align go-to-market plans with program timelines.
- Technology layering and modularity. Solutions that combine modular hardware, standardized controls and cloud-native energy management are gaining preference among large C&I buyers and utilities for faster deployment and predictable O&M economics.
What PW Consulting’s report delivers (practical, actionable content)
The research is designed to be directly operationalizable by corporate strategy, BD, procurement and engineering teams. Highlights of the dataset and toolkit include:
Microgrid Market
- Robust market sizing and scenario models (historical 2020–2025; forecast 2026–2032) with configurable assumptions for technology cost curves, financing terms and policy levers.
- Bottom-up total cost of ownership templates and levelized energy/capacity models tailored to common microgrid architectures (grid-connected, off-grid, hybrid) — ready to be populated with tender-level quotes.
- Regulatory and incentive mapping that links program eligibility, procurement timelines and domestic-content obligations to project-level economic sensitivity analyses.
- Vendor benchmarking and capability matrices that score players on hardware, software, system integration, finance and lifecycle services — enabling rapid shortlisting for RFPs.
- Project-level pipeline intelligence and anonymized case studies that demonstrate procurement structures, commercial terms and risk allocation patterns actually used in the market.
- Playbooks for procurement, partnering and M&A — including integration checklists for digital platforms and commissioning/O&M handover templates to minimize lifecycle risk.
Competitive landscape: capabilities, moves and implications
The microgrid ecosystem is heterogeneous: large global OEMs, specialist storage vendors, systems integrators and software providers each own distinct value pools. Our assessment synthesizes capability sets and recent market moves to surface strategic implications for potential partners, suppliers and acquirers.
Microgrid Market
- Platform integrators and utilities-facing players (e.g., Schneider Electric, Siemens, ABB, Hitachi Energy). These firms compete on full-stack offerings — hardware, energy management platforms and services — and are positioned to win large commercial, industrial and utility-scale engagements where single-source accountability matters.
- Power electronics and modular system providers (e.g., Eaton, GE, S&C Electric). Their focus on modular, containerized architectures and rapid-deploy solutions appeals to industrial operators and utilities seeking standardized build-and-repeat models.
- Energy storage specialists (e.g., Tesla, Eos Energy, Bloom Energy). Vendors focused on battery chemistries or long-duration storage occupy the technology frontier. Strategic orders and repeat wins in 2025–2026 indicate a race to secure deployments that validate LDES and alternative chemistries at scale.
- Hybrid power and generator incumbents (e.g., Caterpillar). Legacy engine manufacturers are repositioning toward hybrid solutions combining gensets with renewables, often leveraging partnerships to enter data-center and industrial microgrid segments.
- Software and control specialists (e.g., Power Analytics, Honeywell). These companies capture disproportionate lifecycle value via controls, optimization and virtual power plant enablement; their software becomes a high-margin wedge in long-term contracts.
- Project developers and energy services firms (e.g., Ameresco, FlexGen). These players bridge finance, project development and O&M, offering packaged delivery models attractive to customers seeking single-contractor accountability.
Recent market evidence underscores these dynamics: zinc-based storage orders supporting commercial microgrids, large battery systems transacted to improve grid delivery, major partnerships for data-center independent energy solutions, and state-backed microgrid hub initiatives for disaster resilience. These transactions and programs are not isolated events — they illustrate how policy, procurement and technology advances are synchronizing to accelerate commercial adoption.
Strategic implications and recommendations for 2026
- Prioritize compliance with domestic-content rules early in supplier selection. Build America, Buy America constraints are a sourcing and schedule risk — resolve supplier qualification and waiver strategies before finalizing EPC contracts.
- Lock flexible procurement windows to capture falling storage installed costs without conceding excessive cost escalation risk on long-lead items.
- Lean into modular architectures and software-first controls to shorten deployment timelines and preserve upgrade pathways for evolving storage chemistries or grid services monetization.
- Use targeted public programs and utility incentives to derisk first-of-kind projects — aligning project schedules to program timelines can materially improve returns.
- Evaluate partnership models (licensing, white-label, JV) rather than purely organic build-outs — strategic alliances with technology owners or local integrators can accelerate market entry and provide local-compliance coverage.
- Design procurement contracts to shift performance risk appropriately: tie major payments to successful commissioning and verified islanding/black-start capabilities rather than equipment delivery alone.
- Consider M&A or minority investments in specialist storage or software providers to secure access to differentiated technologies and avoid supplier bottlenecks.
How PW Consulting supports your 2026 playbook
Our Microgrid Market report is engineered to be a decision-grade tool. It combines rigorous market sizing, transparent modeling assumptions, a curated project/transaction database, vendor scorecards and procurement playbooks. The full study includes the granular segment and regional splits, detailed company profiles, and downloadable financial models that executives and commercial teams can adapt to their specific investment cases.
For teams that need executable next steps in 2026 — from vendor shortlisting and contract terms to scenario-weighted capital planning and regulatory compliance checklists — PW Consulting offers bespoke advisory packages that operationalize the research into board-level decisions and tender-ready documents.
Microgrids are now a core element of strategic energy portfolios. The market momentum is clear and measurable; the choices companies make in 2026 about technology, partners and procurement models will define competitive positions for the next decade. Access the full report and models to move from high-level conviction to executable advantage.
For detailed analysis of this topic, please visit the official page: Microgrid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com