

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Electrode Paste Market — USD 1,080M by 2032, 2.7% CAGR (2026–2032)

Electrode Paste Market 2026: Strategic Imperatives for Leaders — A PW Consulting Preview
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a forward-looking synthesis of our Electrode Paste Market study designed to equip executives, product leaders, and M&A teams with the decision framework they need for 2026. This preview outlines the strategic value of the full report, summarizes high‑confidence market dynamics, and highlights actionable pathways companies can pursue — while reserving the granular segment matrices and proprietary model outputs for the full report access.
Electrode Paste Market
Why this study matters for 2026 decisions
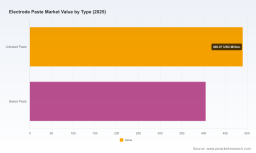
The electrode paste market has transitioned from a niche clinical consumable to a supplier‑managed, regulation-intensive segment of neurodiagnostic and electrocardiographic healthcare workflows. Our model—which uses 2025 as the base year and projects through 2032—shows the market reaching USD 895.0 Million in 2025 and following a measured trajectory at a 2.7% compound annual growth rate (CAGR) to around USD 1,080 Million by 2032. That trajectory masks important operational inflection points: supply‑side specialization, evolving clinical best practices for long‑duration monitoring, and payer/regulatory clarity that together will shape winners and laggards through the middle of the next decade.
Electrode Paste Market
For executives deciding on capex, R&D prioritization, channel strategy, or M&A in 2026, the study provides three things that matter most: a validated top‑down market model, a risk‑adjusted scenario set for demand drivers, and a playbook linking regulatory obligations to go‑to‑market actions.
Electrode Paste Market
What the full report delivers (practical, transaction‑ready outputs)
- Market model and forecast (2026–2032) with sensitivity testing across pricing, procedure volumes, and raw‑material cost shocks.
- Segment mapping by region, product type, and clinical application with decision rules for product prioritization (note: detailed segment tables and vendor share matrices are available in the full report).
- Regulatory and reimbursement matrix tying product claims, 510(k) pathway considerations, and common CPT/DRG interactions to commercial levers.
- Supplier and raw‑material risk dashboards, including backward compatibility testing requirements and quality certifications that drive procurement preferences in hospitals and labs.
- Competitive intelligence dossiers and playbooks for the top commercial and technology players — designed to inform negotiations, partnership diligence, or acquisition screening.
- Actionable go‑to‑market plans covering distributor selection, clinical evidence generation, and lifecycle management to maximize uptake in neurodiagnostic and ECG workflows.
Market dynamics and regulatory context
Two regulatory realities shape near‑term strategic choices. First, electrode pastes and related gels fall under FDA’s Class II device controls and, in practice, are frequently managed through the 510(k) pathway with product code designations that require biocompatibility, impedance, and adhesion equivalence testing. Second, ISO 13485 remains a de facto minimum standard for manufacturing quality — purchasers increasingly make ISO certification a contractual prerequisite. These compliance constraints raise the bar for new entrants and create a moat for incumbents that have invested in validated manufacturing and clinical comparators.
The market also sits within established reimbursement pathways for EEG/ECG procedures: electrode pastes used in diagnostic neurophysiology benefit from procedure-level coverage under standard CPT ranges, which in turn influences hospitals’ willingness to adopt premium formulations that demonstrably reduce skin irritation or improve signal fidelity during extended monitoring. That linkage between clinical benefit and reimbursement creates a premium lane for differentiated products that can be proven in head‑to‑head operational studies.
Competitive landscape — focused profiles
- Parker Laboratories, Inc. — Headquartered in Fairfield, New Jersey, Parker commercializes Spectra 360, a salt‑free, chloride‑free, bacteriostatic conductive gel formulated for prolonged electromedical skin contact. That formulation addresses a clear clinical pain point—minimizing skin irritation during extended EEG/ECG monitoring—and supports claims that matter in procurement evaluations. Parker’s product documentation and regulatory positioning reflect an emphasis on quality and clinical suitability for neurodiagnostic workflows.
- Weaver and Company — Based in Aurora, Colorado, Weaver’s Ten20 conductive paste is a long‑standing option for securing non‑gelled cup electrodes and is widely distributed through national medical supply channels. The product’s regulatory clearances and distribution partnerships position Weaver as a reliable logistics and channel partner for clinical units that prioritize supply continuity and established clinical performance.
Both companies operate in a regulatory environment where 510(k) clearances and ISO 13485 manufacturing controls are material commercial assets — and where distribution partnerships with major suppliers materially influence adoption curves in hospital systems. The market concentration metrics indicate the top three suppliers account for a meaningful majority of market share, creating both barriers to entry and opportunities for targeted consolidation.
Where strategic value accumulates — three high‑impact plays for 2026
- Product differentiation through clinical evidence: Incremental performance advantages—reduced skin irritation, lower impedance variability during long‑duration monitoring, or enhanced bacteriostatic properties—translate to procurement preference when supported by operational trials. Prioritize limited‑scope clinical studies tied to clear hospital KPIs (reduced site revisits, fewer re‑applications, shorter prep time).
- Channel and procurement optimization: Distributors and group purchasing organizations dictate access to large neurodiagnostic centers. Negotiate distribution clauses that lock in supply continuity and tiered pricing tied to volume thresholds; consider consignment or vendor‑managed inventory pilots to reduce hospital stockouts and accelerate adoption.
- M&A and partnership discipline: Given the market’s moderate concentration and predictable growth, bolt‑on acquisitions that add distinct formulations, validated manufacturing capacity, or regional distribution can generate immediate scale benefits. Use the report’s M&A heatmap to prioritize targets that close capability gaps rather than simply expand product lines.
Supply chain and raw‑material considerations
Raw‑material choices are not commoditized in this market. Formulation choices that avoid salts and chlorides can materially reduce dermatological adverse events in long‑duration use cases—an attribute buyers will pay to avoid downstream clinical incidents. At the same time, reliance on single‑source raw materials or specialized bacteriostatic agents introduces vulnerability. The full report maps supplier concentration for key inputs and provides contingency strategies for contract manufacturers and finished goods producers.
Commercial and pricing tactics
Price alone is an insufficient leverage point when procurement teams balance total cost of care, clinical outcomes, and inventory risk. Instead, successful vendors blend: (a) evidence‑based premium positioning for differentiated formulations, (b) competitive tender strategies for commoditized product lines, and (c) service offerings (training, inventory management) that shift purchasing decisions from line‑item to pathway procurement. The report supplies tender templates and EBITDA-impact models for common contract scenarios.
Risk framework for investors and corporate strategists
- Regulatory risk: Clearance timelines and claims validation can delay market entry; prioritize products with clear equivalence paths or invest in the clinical programs that substantiate novel claims.
- Operational risk: Manufacturing quality (ISO 13485) and supply continuity are primary commercial gating factors for hospital contracts.
- Reimbursement and clinical adoption risk: While procedure reimbursement is established, conversion to a premium product depends on demonstrable operational savings or clinical benefit.
How PW Consulting’s report removes guesswork
Our full study integrates a validated market model (base year 2025, historical 2020–2025, forecast 2026–2032) with granular scenario testing, regulatory checklists, a proprietary vendor scorecard, and an M&A heatmap intended for near‑term deal execution. For leadership teams, that means moving from anecdotal decision‑making to evidence‑based strategies: you will know where to commit R&D dollars, how to structure distribution agreements, which assets to target for acquisition, and what clinical evidence is required to win in large hospital systems.
Next steps — what to request from the full report
- Access the full dataset and interactive forecast model to run your own scenario (pricing, procedure growth, raw material shocks).
- Download vendor scorecards and regulatory dossiers for target due‑diligence workflows.
- Obtain the commercial playbooks and tender templates to accelerate 90‑day sales cycles in hospital chains and diagnostic labs.
PW Consulting’s Electrode Paste Market report is structured to support high‑stakes decisions in 2026: product portfolio prioritization, distribution contracting, and M&A screening. This preview outlines the strategic contours; the full report contains the segment‑level matrices, supplier share details, and proprietary financial models that underpin these recommendations. For executives intent on winning the next wave of clinical adoption, the difference between an informed strategy and a reactive posture will be access to that underlying intelligence.
To obtain the complete report and the accompanying data model, please visit the PW Consulting research portal. The full report contains the detailed segmentation, vendor share matrices, and downloadable forecasting workbooks needed to execute confidently in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Electrode Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com