

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Deicing Salt Market to Top USD 3,447 Million by 2032, Expanding at a 3.55% CAGR (Forecast 2026–2032)
By pmarketresearch, 2026-08-12
Worldwide Deicing Salt Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases a strategic briefing drawn from our forthcoming Worldwide Deicing Salt Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032). This briefing distills the high‑impact insights that will matter most to executives making procurement, capital allocation, regulatory compliance, and M&A decisions in 2026. The market is projected to expand at a steady compound annual growth rate (CAGR) of 3.55% across the 2026–2032 forecast window, extending a measured recovery and structural adjustment that began in the early 2020s. Our analysis synthesizes price, capacity, regulatory and environmental vectors into actionable scenarios — while reserving detailed segment-level tables and proprietary model outputs for the full report.
Worldwide Industrial Rugged Smartphone Market
Market snapshot: steady growth, concentrated incumbency, and operational headwinds
PW Consulting’s topline model estimates the global deicing salt market at approximately 2.7 billion USD (revenue unit: Million, base year 2025), up from roughly 2.27 billion USD in 2020. Under our central forecast, the market reaches roughly 3.45 billion USD by 2032. Growth at a 3.55% CAGR reflects a mix of volume recovery in transportation maintenance, incremental premiumization through treated and blended products, and regional policy-driven substitution toward lower-chloride alternatives in environmentally sensitive areas.
Worldwide Anisotropic Conductive Film (ACF) Tape Market
Market concentration remains moderate: the three largest producers account for a little over one‑fifth of global supply, while the top five account for just under one‑third. That structure leaves room for national champions, regional miners, and smaller specialty suppliers to exert outsized influence in local tender markets and niche product categories.
Worldwide Massage Therapy Software Market
Why this report matters for 2026 planning
- Procurement optimization: Procurement teams should anticipate persistently elevated input cost volatility (notably energy and packaging) even as volumes grow. Our demand/supply scenarios quantify how a 5–10% swing in mining energy costs or imported container tariffs propagates into landed costs — crucial for RFP timing and contract length decisions.
- Capex and capacity planning: Capital planners will find the report’s scenario-based mine and evaporation‑facility utilization curves essential for deciding whether to accelerate expansions, pursue brownfield upgrades, or defer investment until pricing stabilizes.
- Regulatory compliance and product strategy: With tightening chloride discharge limits in parts of Europe and growing preference in North America for corrosion‑mitigating blends, our strategic playbook maps R&D prioritization and go‑to‑market timing for low‑chloride and corrosion‑inhibited products.
- M&A and partnership targeting: The moderate concentration ratio indicates acquisition targets exist across the value chain. Our company-screening matrix combines financial health, reserve life, and local regulatory exposure to highlight deals that materially improve a buyer’s route to market or technical capability.
Key market dynamics shaping 2026 decisions
- Raw material and energy cost pressure: PW Consulting observed that underground rock salt mining faced higher operational input costs in 2024 — energy intensity translated into an 8–12% rise in unit mining costs in many operations. Evaporation facilities also remained sensitive to natural gas prices; North American evaporation margins were influenced by average natural gas prices near $3.50/MMBtu in late 2024. Procurement and hedging strategies must factor these drivers into both short and multi‑year contracts.
- Packaging and logistics: Trade policy and tariffs have a tangible bearing on delivered costs. For example, tariffs that increased the landed cost of steel containers last cycle raised packaging expense by several percentage points for import‑dependent suppliers. Organizations reliant on cross‑border packaged deliveries will need to review packaging strategies and nearshore manufacturing options.
- Environmental regulation and product substitution: Environmental directives that restrict chloride discharge in sensitive waterways are accelerating demand for lower‑chloride alternatives and magnesium‑based blends in certain jurisdictions. Concurrently, North American regulatory guidance favoring magnesium chloride blends to reduce infrastructure corrosion is shifting procurement specifications for highway and airport authorities.
- Product innovation and differentiators: Treated salts and corrosion‑inhibited formulations are transitioning from niche to mainstream for infrastructure‑sensitive customers. Value capture will lie in formulations that demonstrably reduce corrosive impact while preserving deicing performance, and in commercialization pathways that minimize price premium friction.
Competitive landscape — strategic implications from leading players
The market’s leading global and regional suppliers deploy differing strategies that provide a template for both incumbents and challengers:
- Cargill, Incorporated (Minneapolis, MN): As the world’s largest producer, Cargill leverages scale across mining and evaporation assets to serve road and airport channels. Recent capacity expansion announcements (e.g., Belle Plaine) underscore a volume play to crowd out higher‑cost competitors — a signal that price‑competitive supply will be a central strategy in North America in 2026.
- Morton Salt, Inc. (Chicago, IL): Morton’s integrated underground mines and focus on packaged and bulk highway supply point to a dual strategy of operational reliability and customer segmentation. Morton’s footprint makes it a barometer for packaged supply economics and commercial channel renewals.
- K+S Aktiengesellschaft (Germany): The firm’s European mining focus and renewed environmental certifications (updated ISO 14001) position it well for regulated markets where sustainability credentials influence tender outcomes. Expect continued investment in treated anti‑caking and low‑environmental‑impact product lines.
- Compass Minerals (Overland Park, KS): Compass’s product innovation (e.g., recent launch of a corrosion‑inhibited treated salt) shows the commercial upside of premium formulations. Their strategy highlights that product differentiation — not just low unit cost — can win share among infrastructure‑sensitive customers.
- CNSIC (Beijing): The state‑owned scale in solar‑evaporated salt gives CNSIC a competitive cost baseline for domestic markets and export corridors across Asia. Trade flows from large coastal evaporation facilities mean that global buyers must factor in Chinese capacity in sourcing scenarios.
- Ineos, Cheetham Salt, Sudsalz: These regional producers demonstrate the persistence of local champions in markets where logistics costs, licensing, and long‑standing relationships with highway agencies create durable moats. Their roles will remain prominent in anchor supply contracts and seasonal surge capability.
Operational playbook: six actions PW Consulting recommends for 2026
- Re‑baseline procurement contracts: Move from fixed‑price multi‑year contracts to hybrid arrangements that include indexed energy/packaging cost pass‑throughs and volume flex provisions tied to winter severity models.
- Prioritize product segmentation: In tender renewals, separate specifications by environmental sensitivity and infrastructure corrosion risk to allow procurement to choose performance tiers rather than a one‑size‑fits‑all standard.
- Invest selectively in treated blends: Given regulatory and buyer preference trends, allocate R&D or JV budgets to corrosion‑inhibited and low‑chloride blends where price elasticity is highest.
- Stress‑test supply chains: Conduct scenario analyses for energy price shocks, container tariff persistence, and mine downtime to inform inventory buffers and alternative sourcing corridors.
- Target M&A for capability, not just capacity: Look for targets that add treated product formulations, beachhead positions in regulated geographies, or logistical hubs that shorten lead times to high‑value customers.
- Embed sustainability into tender wins: Use environmental certifications, life‑cycle chloride discharge assessments, and transparent emissions reporting as differentiators in competitive bids.
Report deliverables — what’s in the full publication (high level)
The full PW Consulting Worldwide Deicing Salt Market report combines proprietary demand modelling, supply‑side capacity mapping, scenario analyses, and a decision‑oriented playbook. Highlights include:
- Topline and scenario forecasts (historical 2020–2025; base year 2025; forecast 2026–2032) with sensitivity testing for energy, packaging tariffs, and regulatory adoption curves.
- Supply‑chain risk heat maps and utilization scenarios for mines and evaporation facilities under alternative winter‑severity and gas‑price paths.
- Commercial strategy modules for product segmentation, pricing levers, and tender structuring — including sample contractual language and hedging templates.
- Competitive intelligence dossiers on global and regional players with deal‑rationale matrices for M&A and partnership pursuit.
- Regulatory impact assessment and environmental compliance roadmaps tailored to major jurisdictions.
To preserve the investigative value of our proprietary models, the report intentionally refrains from publishing live segment tables in summary releases. We provide headline market sizing, concentration metrics, and broad directional indicators here, but detailed regional, type, and application splits are available only in the full report and interactive databook.
Methodology and data integrity
PW Consulting’s forecast combines bottom‑up capacity and throughput modelling with demand drivers derived from transport activity, municipal procurement cycles, and industrial consumption trends. Historical reconciliation with publicly filed sales, mine output, and trade statistics anchors the model for 2020–2025, while forward scenarios incorporate observable inputs: energy price pathways, recent corporate capacity announcements, product innovation timelines, environmental regulation trajectories, and logistics cost shocks.
We corroborate our supply‑side assumptions with on‑the‑ground intelligence — including the 2024 expansions and product launches by market participants — and validate demand elasticities through municipality and maintenance contractor interviews across representative climates. The report flags data confidence levels by node so decision‑makers can weight model outputs appropriately in strategic planning.
Final word: how PW Consulting helps you act in 2026
As the deicing salt market transitions from post‑pandemic normalization into a period shaped by regulatory pressure and selective product premiumization, 2026 will be a year for disciplined strategy. PW Consulting’s report equips leaders with the scenario tools, supplier playbooks, and acquisition filters required to protect margins, secure supply, and win tenders where performance and environmental stewardship matter.
For procurement directors, CEOs and investors preparing capital and commercial decisions in 2026, the full report offers the granular segmentation, contractual templates, and interactive databook necessary to execute with confidence. Access to the complete intelligence and our bespoke advisory services is available via the PW Consulting report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Deicing Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Whetstones Market Tops USD 148.5 Million in 2025 — Poised for Continued Growth Through 2026–2032
By pmarketresearch, 2026-08-12
Whetstones Market 2026 Preview: Strategic Imperatives for Corporate Leaders
PW Consulting’s new Whetstones Market report — the Whetstones Market chapter of our Whetstones Market series — synthesizes five years of market behaviour (2020–2025) and offers a forward-looking, scenario-ready forecast through 2032. This briefing distils the clearest takeaways that will matter to procurement directors, product managers, manufacturing strategists, channel leaders and M&A teams making decisions in 2026. We show why the next 18 months are decisive, identify where margin and resilience can be won, and explain which signals you must track to keep strategy aligned to a market growing at mid-single digits.
Electrolytic capacitor paper Market
Market at a glance (what matters)
- The global whetstones market is a modest, mature hardware segment measured in USD (Million). After rising from the low triple digits into the mid‑hundreds during the 2020–2025 period, the market is forecast to grow throughout 2026–2032 at a compound annual growth rate of 4.25% under our base scenario.
- PW Consulting’s baseline model projects continued measured expansion through 2032, driven by a mix of consumer premiumization, steady professional demand, and selective industrial replacement cycles.
- This growth is sufficient to create new return-on-investment opportunities for product innovations and supply‑chain optimization — but not large enough to make undisciplined volume plays profitable without targeted differentiation.
Why this report is strategically material for 2026
- Translate macro momentum into boardroom decisions: our analysis connects headline growth to P&L-sensitive actions—product line rationalization, premiumization of core SKUs, and targeted capacity investments.
- De‑risk raw material exposure: the report maps supply risk for natural novaculite and the principal synthetic abrasives while prescribing hedging, vertical integration and sourcing contingencies.
- Inform M&A and partnership routes: we delineate acquisition targets by capability (quarry access, ceramic R&D, bonded abrasives manufacturing, DTC brands) and quantify where consolidation could meaningfully move the needle.
- Operationalize regulatory and marketing claims: guidance on Made in USA compliance and labeling prevents reputational and legal drag while unlocking premium pricing for legitimate claims.
What the full report delivers (practical, implementable content)
- Transparent methodology and forecast engine: demand drivers, elasticity assumptions, shipment-to-revenue mapping and sensitivity tables that let you stress-test scenarios specific to your cost structure.
- Go‑to‑market playbooks: SKU prioritization, premium framing, channel segmentation (retailers, online DTC, professional distributors), and conversion levers for chef/creator endorsement programs.
- Supply‑chain and raw‑material playbooks: supplier scorecards, supplier concentration risk matrices, inventory policies and near-term procurement play options to secure novaculite and key synthetic inputs such as aluminum oxide and silicon carbide.
- Competitive vendor scorecards and capability maps: qualitative and semi‑quantitative profiles of incumbent manufacturers and specialty producers, benchmarking on integration, innovation, geographic reach, and channel strength.
- M&A scenario templates and valuation pointers: tailored to smaller industrials and specialty consumer brands, including accretion/dilution models, five‑year synergy schedules and integration risk checklists.
- Commercial KPIs and data dashboard templates: recommended leading indicators (review sentiment scores, channel fill rates, professional endorsement velocity) and how to instrument them using third‑party data and internal telemetry.
Market dynamics and structural drivers
The whetstones market is simultaneously traditional and innovation‑rich. Longstanding demand from home cooks and woodworking professionals sits beside fast‑moving innovation in synthetic ceramic and bonded systems that promise speed and consistency. Several structural vectors matter to strategy:
Solid Tumors Target Proteins Market
- Material bifurcation: natural novaculite stones retain authentic value propositions — provenance, tactile heritage and a premium narrative — while synthetic options (aluminum oxide, silicon carbide, ceramic bonds) deliver predictable grit, faster cut rates and manufacturing scalability. Each pathway carries distinct cost, sourcing and marketing implications.
- Supply geography and reserves: proven quarry reserves for specific natural materials are concentrated and, in some cases, controlled by vertically integrated operators. That concentration shapes negotiating leverage and long‑term cost curves.
- Channel and influence effects: editorial testing and chef endorsements (recent product tests in mainstream food media have materially affected consumer consideration) accelerate premium product adoption and create short windows to capitalize on visibility.
- Regulatory and claims risk: rules governing “Made in USA” claims and similar provenance assertions are material to pricing and positioning; non‑compliant claims create financial and reputational risk that must be actively managed.
- Industry fragmentation: the competitive structure is not dominated by a single global integrator — several well‑positioned specialty firms, industrial brands and system providers compete across different customer segments, leaving opportunity for consolidation and capability acquisitions.
Competitive positioning — who matters and why
Our vendor analysis highlights a mix of vertically integrated heritage players, global industrial abrasives manufacturers, high‑performance Japanese specialists and systems providers focused on equipment and workflow integration. A selective summary of strategic positions:
Medical Gas Area Alarm Panel Market
- Dan’s Whetstone Company: quarry ownership and fully domestic manufacturing underpin a strong provenance story and supply control. This model supports premium positioning and margin resilience where authenticity matters.
- Norton Abrasives (Saint‑Gobain): strength in synthetic manufacturing, scale, and industrial channels; suited to customers prioritizing consistency and integration into tool‑level supply agreements.
- SHAPTON and Matsunaga (King brand): Japanese specialists that compete on high‑performance ceramic and waterstone technologies, reputation among professional knife users, and precision‑oriented product engineering.
- Work Sharp, Falcon, NORITAKE, and Gesswein: diverse plays ranging from sharpening systems and benchtop equipment to specialty stone supply for jewellery and toolmakers; they capture non‑commodity parts of the value chain.
Recent editorial and testing coverage in consumer media has elevated certain product lines, creating short windows of accelerated consumer demand. Separately, our competitive maps show that the top handful of firms collectively represent far from overwhelming market control — top players account for a minority share, leaving adjacent pockets open to nimble entrants and consolidation.
Strategic scenarios for 2026 (decision playbook)
Out of our scenario suite, three pragmatic strategies emerge for market participants depending on appetite and capability:
- Protect-and‑premium (for premium consumer brands and vertically integrated producers)
- Pursue provenance certification and storytelling, lock long‑dated supply from key quarries where possible, and invest in chef/creator partnerships to maintain premium ASPs.
- Prioritize quality control systems and customer education programs to reduce returns and increase lifetime value.
- Scale-and‑systematize (for industrial suppliers and large abrasives manufacturers)
- Standardize synthetic product lines, optimize bonded processes and pursue channel partnerships with tool OEMs to embed stones into consumable supply streams.
- Drive cost out via process automation in ceramic and resin bonding operations while selectively acquiring niche brands for channel access.
- Experiment-and‑specialize (for challengers and digital-first brands)
- Target narrow technical niches (e.g., jewelry, woodturning, professional culinary) with high‑margin SKUs, direct content marketing, and rapid iteration informed by reviewer feedback.
- Use subscription and replenishment models to capture recurring revenue from consumable surfaces and finishing products.
Tactical 90–365 day priorities
- 90 days: complete a raw‑material risk assessment and vendor qualification for the next 12–18 months; validate any provenance claims against FTC guidance; run a SKU profitability sweep to identify low-turn inventory candidates.
- 180 days: execute a chef/influencer pilot tied to a premium SKU, instrument customer review tracking, and implement a supplier buffering policy for critical grades.
- 365 days: finalize a one‑year roadmap for product and channel expansion tied to a go/no‑go M&A threshold; operationalize the dashboard KPIs recommended in our report (fill rate, review velocity, ASP by channel, raw material cost delta).
What we recommend you track in 2026
- Editorial and testing cycles in major culinary outlets and specialist trade media — these create outsized episodic demand.
- Raw material supply announcements and long‑term lease activity in known quarry regions.
- New product introductions from ceramic and bonded‑stone specialists that change expected cut/time trade‑offs.
- Regulatory guidance updates related to provenance and origin claims in key consumer markets.
Accessing full intelligence
This release is a director‑level briefing designed to establish the strategic view. The full Whetstones Market report contains the proprietary segmentation tables, regional and application forecasts, vendor scorecards and downloadable model files that are required to execute the playbooks we outline here. If you are planning capital allocation, procurement commitments or acquisition diligence in 2026, the detailed forecasts and supplier evaluations in the full report will materially accelerate and de‑risk those workflows.
PW Consulting is ready to walk your executive team through a tailored briefing that translates these findings into a company‑specific action plan with prioritized initiatives, financial impact scenarios and a monitored KPIs dashboard for 2026. Contact our industry practice to schedule a strategy session and gain access to the complete dataset and forecasting model.
For detailed analysis of this topic, please visit the official page: Whetstones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: New report predicts Epoxy Electrocoating market to expand at a 4.5% CAGR through 2032
By pmarketresearch, 2026-08-12
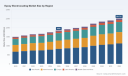
Epoxy Electrocoating Market — Strategic Outlook 2026: PW Consulting Insights
Executive summary
PW Consulting’s latest Epoxy Electrocoating Market report (base year 2025) delivers a forward-looking toolkit for executives making high-stakes sourcing, manufacturing, and M&A decisions in 2026. After tracking the market through the 2020–2025 historical window, our model forecasts the global epoxy e-coat market to grow at a steady compound annual growth rate (CAGR) of 4.5% over the 2026–2032 forecast horizon. The market expanded from about USD 1.5 billion in 2020 to roughly USD 1.85 billion in 2025, and is projected to surpass USD 2.5 billion by 2032 under our central scenario.
XR Imaging Waveguide Market
This release summarizes the strategic implications that matter most to C-suite and business unit leaders — while reserving proprietary, line-item segmentation and scenario tables for the full report. Consider this a high-fidelity preview: deep enough to guide near-term strategy, intentionally limited to encourage direct access to the complete dataset and decision-support materials.
Kraft Interleaving Paper Market
Market trajectory and macro drivers
-
Demand resilience and steady growth: The epoxy electrocoating market has shown consistent expansion through 2020–2025, reflecting its entrenched role in corrosion protection for automotive OEMs, industrial machinery, and durable appliances. Our base-year assessment (2025) captures the market at approximately USD 1.85 billion, with a prudent baseline projection rising to ~USD 1.92 billion in 2026 and continuing to reach roughly USD 2.52 billion by 2032 under the central-case 4.5% CAGR.
Spaceborne Multibeam Antennas Market -
Cost and supply-chain volatility: Raw-material headwinds have intensified in early 2026. Regional epoxy resin price observations in April 2026 show material cost pressures — for example, Northeast Asia pricing near USD 2.62/kg (up ~23% year-over-year in our monitoring window) and increases in Europe and the Middle East that have meaningfully raised input cost baselines. These moves are being reinforced by corporate pricing actions across the value chain.
-
Policy and trade friction: Recent regulatory actions — notably final affirmative determinations by the U.S. Department of Commerce in antidumping and countervailing duty investigations on epoxy resins from several producing countries — introduce a new layer of trade risk and cost of goods considerations for manufacturers and importers in 2026.
Dynamics shaping 2026 decisions
-
Input-cost passthrough and margin management: Manufacturers and OEMs must reassess price models and contractual terms. Our scenario workbench demonstrates that in most cases, immediate margin pressure from April–June 2026 epoxy resin inflation cannot be absorbed without operational levers or renegotiated supply agreements.
-
Sourcing diversification vs. consolidation: The ecosystem remains moderately concentrated; the top three suppliers control a clear majority of market supply, with the top five exerting near-three-quarters influence on the market. This concentration amplifies supplier-side pricing influence but also presents targeted partnership opportunities for buyers seeking security of supply.
-
Technology and application transitions: Low-temperature curing formulations, lower-voltage application systems, and sustainability-focused chemistries are gaining traction. Investments in these technology vectors reduce energy intensity and support OEM sustainability commitments — a material consideration for capex prioritization in 2026.
-
Regional demand shifts: Growth momentum in Asia-Pacific continues to shape capacity decisions, while mature markets sustain demand through replacement and aftermarket activity. Our full report quantifies these flows at a granular level and models cross-border trade under varying tariff and duty scenarios.
Competitive landscape — what the leading players are doing
We examined the strategies and capabilities of leading suppliers and technology owners to map competitive advantage across production footprint, product performance, and customer intimacy. Highlights:
-
PPG Industries, Inc. (Pittsburgh, USA) — maintains leadership through its Powercron cathodic epoxy line, emphasizing high corrosion resistance and uniform film build. Its global customer relationships in industrial and automotive sectors are a structural advantage for volume and innovation partnerships.
-
Axalta Coating Systems (Philadelphia, USA) — positions its AquaEC cathodic epoxy series toward OEMs prioritizing corrosion protection and mechanical performance. Axalta’s strength is in integrated coatings systems and OEM program alignment.
-
BASF SE (Ludwigshafen, Germany) — leverages its CathoGuard family and broad materials science platform. Recent greenfield and expansion investments underscore BASF’s intention to support automotive OEM re-shoring and regional capacity needs.
-
The Sherwin-Williams Company (Cleveland, USA) — focuses on heavy machinery and industrial applications with formulations engineered for edge coverage and substrate performance in challenging environments.
-
Nippon Paint and Kansai Paint (Japan) — together with regional specialists like KCC Corporation and Tatung Fine Chemicals, they offer strong local capabilities across Asia, often emphasizing eco-efficiency, low-temperature curing, and supply reliability for OEMs in the region.
Recent corporate actions matter for 2026 strategy. For example, BASF commissioned a new automotive coatings plant in Münster in late 2025 and expanded e-coat capacity in Mangalore in early 2026 — moves that change competitive capacity and customer lead-times in Europe and South Asia. Meanwhile, DIC Corporation’s April 2026 announcement of price increases for epoxy resins and curing agents is a leading indicator of continued upstream price volatility. These events reinforce the need for dynamic supplier engagement and scenario modeling.
What’s inside the full PW Consulting report (actionable, practitioner-focused)
The full report is structured to move teams from insight to action during 2026 planning cycles. Key deliverables include:
-
Market size and forecast model (2020–2032) with company-level roll-ups and scenario toggles — base case, upstream shock case, and accelerated electrification case.
-
Supplier risk heatmap — assessing concentration, geopolitical exposure, feedstock sensitivity, and capacity elasticity at the production-node level.
-
Cost-pass-through and margin impact calculators — sector-specific templates that allow procurement and finance teams to stress-test contracts against realistic resin-price trajectories.
-
Technology readiness assessment — performance, capex implications, and time-to-market for low-temp curing, low-VOC chemistries, and application equipment.
-
M&A and partnership playbook — prioritized target archetypes (bolt-on capacity, technology play, or channel access) and valuation benchmarks informed by concentration metrics and recent transactions.
-
Regulatory and trade impact matrix — mapping antidumping/countervailing outcomes and likely near-term trade frictions to procurement and distribution strategies.
Note: This summary intentionally preserves proprietary segmentation tables and unit economics that are included exclusively in the paid report. Those granular figures — including formulation-, region-, and end-use breakouts by revenue and volume — are available to subscribers and clients through our secure portal.
Practical recommendations for 2026
-
Immediate (0–3 months): Stabilize supply through dual-sourcing of critical resins, activate price-index clauses where feasible, and run the PW Consulting cost-pass-through calculator against current contracts to quantify near-term margin exposure.
-
Near-term (3–9 months): Prioritize small-capex pilot projects to qualify low-temperature and low-VOC formulations with key OEM customers. These pilots both reduce energy usage and create differentiators for future contracts.
-
Medium-term (9–18 months): Revisit capacity plans in light of upstream inflation and trade measures. For producers, we recommend a staged investment approach — conditional on validated off-take agreements or supply contracts that mitigate feedstock risk.
-
Strategic (12–36 months): Assess targeted M&A to plug strategic gaps — for example, acquiring regional formulation expertise or localized production to minimize tariff/duty exposures and logistics costs under stressed trade scenarios.
Methodology and data integrity
Our analysis synthesizes primary interviews with supply-chain executives, OEM procurement data, regional trade statistics, company filings, and independent price monitoring. The report uses the calendar year 2025 as the base year, covers the historical period 2020–2025, and presents a 2026–2032 forecast scenario set. Financials are reported in USD, with market values expressed in millions for comparability.
Why this matters for 2026
Two simultaneous trends define the strategic landscape for epoxy electrocoating in 2026: persistent upstream cost volatility and accelerating technology-driven product differentiation. Companies that act early — securing supply, validating energy-efficient formulations, and aligning with OEM decarbonization priorities — will convert transient pressures into durable competitive advantage. Conversely, passive actors risk margin compression and supply disruption as raw-material and trade dynamics evolve.
Next steps
PW Consulting’s full Epoxy Electrocoating Market report contains the granular segmentation, downloadable model files, supplier scorecards, and bespoke advisory options designed to support procurement, operations, and strategy teams through 2026 planning cycles. For tailored briefings, scenario workshops, or to acquire the complete dataset and modeling tools, please contact PW Consulting through our corporate channels or visit our report landing page for subscription details.
For detailed analysis of this topic, please visit the official page: Epoxy Electrocoating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MLCC Dielectric Materials Market Poised for 7.05% CAGR Through 2026–2032
By pmarketresearch, 2026-08-12
PW Consulting: Strategic Brief — Worldwide MLCC Dielectric Materials Market (2026 Outlook)
As the multilayer ceramic capacitor (MLCC) ecosystem enters a new phase of product miniaturization, electrification, and performance specialization, dielectric materials are emerging as the strategic fulcrum for OEMs, material suppliers, and capital allocators alike. PW Consulting’s latest market study — driven from a 2025 base and projecting through 2032 — shows the global MLCC dielectric materials market reached approximately USD 1,856.4 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 7.05% over the 2026–2032 horizon, reaching an expected market size near USD 2,981.0 Million by 2032. This press release summarizes the operational intelligence and decision-grade implications the full report delivers for executives planning resource allocation, R&D priorities, and go-to-market timing in 2026.
Induction Furnace Power Transformers Market
Why 2026 Is a Strategic Inflection Point
-
Convergence of technology cycles: Continued demand for higher capacitance per footprint, tighter dielectric tolerances for RF/5G front-ends, and the transition to automotive and industrial-grade reliability are compressing development timelines for dielectric chemistries and processing.
Worldwide Amps & Effects Market -
Supply-side tightening and concentration: The market shows material concentration at the top tier — our analysis indicates a high degree of market share captured by a few global players — creating both supply risk and strategic leverage for integrated MLCC manufacturers and material specialists.
Vertical Centrifuge Tube Market -
Regulatory and sustainability pressure: RoHS and lead-free mandates, together with customer-driven lifecycle carbon expectations, are forcing earlier-than-expected reformulations and qualification programs for legacy dielectric powders.
Key Market Dynamics Shaping 2026 Decisions
-
Material innovation as product differentiation: High‑purity barium titanate remains the workhorse dielectric base, but the competitive advantage is shifting to advanced formulations — rare-earth-doped oxides, engineered zirconates and stannates, and process-enabled microstructure control that underpins both Class I (C0G/NP0) and Class II (X7R, X5R, Y5V) performance envelopes.
-
Miniaturization vs. capacitance trade-offs: The race to squeeze microfarads into the smallest case sizes is increasing pressure on dielectric layering and particle engineering. Suppliers that can marry ultra-thin layers with stable permittivity and low loss will command premium positions in mobile, 5G, and EV applications.
-
Verticalization and strategic partnerships: Leading MLCC producers are investing in in-house dielectric R&D and securing upstream powder supply through long-term contracts or equity stakes — a dynamic that changes negotiation power and time-to-market for new formulations.
-
Geopolitical and supply-chain considerations: Concentration of high-purity powder production in specific geographies, combined with specialized processing know-how, means buyers must model multi-source strategies and consider geographically de-risked inventories for 2026 launch programs.
What the Report Delivers — Practical, Transaction-Ready Intelligence
PW Consulting’s Worldwide MLCC Dielectric Materials Market report is built for decision-makers who require executable insights rather than academic descriptions. The study pairs a rigorous, model-driven market forecast (2026–2032) with modular tools and playbooks that can be operationalized within 90–180 days:
-
Market sizing and scenario models — base, upside, and stress cases aligned to macro demand drivers and technology adoption curves (interactive spreadsheet models accompany the report).
-
Technology roadmaps — comparative performance matrices for Class I vs. Class II dielectrics, emergence timelines for doped oxides, and threshold conditions (temperature, voltage, miniaturization) where specific materials become preferred.
-
Supply-chain maps — tiered supplier lists for powders, formulation houses, and sintering/processing specialists, with risk flags tied to geographic concentration, single points of failure, and qualification lead times.
-
Commercial playbooks — go-to-market sequencing for entrants and incumbents including partnership archetypes, pricing benchmarks, and recommended contract structures for long-term powder supply or joint development agreements.
-
Regulatory and ESG checklist — compliance requirements for lead-free and RoHS-aligned formulations, anticipated testing and certification schedules, and suggestions for lifecycle disclosure to support OEM procurement policies.
Competitive Landscape — Who Matters and Why
The dielectric materials and MLCC production landscape features a mix of vertically integrated MLCC champions, specialized material formulators, and powder manufacturers. The competitive dynamics are defined by three interlocking capabilities: material science depth, process integration (layering, sintering, termination technologies), and scale of manufacturing.
-
Integrated MLCC leaders: Companies such as Murata Manufacturing, Samsung Electro-Mechanics, and TDK continue to hold structural advantages through deep in-house R&D on dielectric formulations and advanced layering processes. Their recent moves — from Murata’s commercialization of extremely high-capacitance 0402 MLCCs to TDK’s expansion of low-resistance, soft-termination automotive lines — illustrate how integrated players convert material advances into product differentiation.
-
Regional and portfolio players: Yageo (including KEMET/AVX), Taiyo Yuden, Kyocera/AVX, and Walsin play to strengths in product breadth, application-specific qualifications (automotive, medical, aerospace), and flexible manufacturing footprints. These players are often the first to respond to customer qualification windows in targeted market segments.
-
Specialists and upstream suppliers: Material-focused companies such as Prosperity Dielectrics, Vibrantz Technologies, Sakai Chemical Industry, and several Japanese powder producers (including Nippon Chemical, Fuji Titanium, and Toho Titanium) supply the high-purity ceramic powders and tailored formulations that underpin the next generation of MLCCs. Their hydrothermal and engineered powder technologies remain central to achieving high density and reliability in ultra-thin dielectric layers.
-
Niche high-reliability suppliers: US-based Vishay, Knowles Precision Devices, and others retain strategic roles in military, medical and certain industrial markets where qualification timelines and reliability thresholds create premium windows.
From a market structure standpoint, the market exhibits notable concentration at the top tiers, creating competitive moats for incumbents while leaving opportunity for specialized entrants through vertical partnerships and focused IP plays. Managers should assume tighter access to differentiated dielectric chemistries without contractual or JV safeguards.
Recent Developments and What They Signal
-
Murata’s mass production of 0402 high-capacitance devices (47 µF) underscores how material-layering innovation is enabling size-to-capacitance leaps, directly impacting mobile and wearable BOMs.
-
TDK’s product expansions — particularly low-resistance soft-termination MLCCs and high-voltage C0G types — highlight demand in automotive and industrial power electronics where both electrical performance and mechanical robustness matter.
Together these product moves reinforce a strategic playbook: accelerate material qualification programs for targeted applications, and align production scale-up with customer qualification windows to avoid missed adoption cycles in 2026.
Strategic Recommendations for 2026
-
Prioritize material partnerships over short-term price plays. Securing co-development or long-term supply agreements with advanced powder/formulation suppliers will be a decisive advantage for firms launching new MLCC SKUs in 2026.
-
Invest in accelerated qualification resources. The parallel pressures of miniaturization and automotive-grade requirements demand parallel investments in test labs and accelerated life testing to compress qualification timelines.
-
Adopt a dual-sourcing strategy for critical powders. Identify and qualify at least one geographically diversified supplier to mitigate regional disruptions and regulatory risks.
-
Assess vertical integration selectively. For firms with scale and capital capacity, backward integration into powder formulation or equity stakes in strategic suppliers can protect roadmaps; for others, exclusivity arrangements and co-development licensing can yield faster routes to differentiated specs.
-
Embed ESG into material strategy. Reformulation for lead-free, lifecycle reporting, and lower-temperature sintering processes will increasingly influence OEM selection criteria and cost of compliance.
How PW Consulting’s Report Supports 2026 Decision Windows
Executives evaluating capital allocation, M&A targets, or R&D roadmaps will find the report’s scenario models, supplier scoring, and time-to-market matrices especially useful. Our deliverables are structured to enable three concrete actions within 90 days: identify the top two critical materials for your 2026 product roadmap; select and initiate discussions with at least one upstream supplier for pilot qualification; and construct a contingency sourcing plan for any single-source powders in your bill of materials.
Next Steps
PW Consulting has intentionally preserved detailed segment-level forecasts, regional breakdowns, and supplier-level financials for subscribers of the full report and data pack. These are the core inputs most procurement officers and corporate strategists need when converting insights into commitments. To access the full dataset, interactive models, and supplier scorecards that underpin our 2026 playbooks, visit our Worldwide MLCC Dielectric Materials Market report page or contact our client services to schedule a briefing tailored to your strategic agenda.
For detailed analysis of this topic, please visit the official page: Worldwide MLCC Dielectric Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Turbocharger Bearing Market to Reach USD 3,075.89 Million by 2032, Growing at a 5.25% CAGR
By pmarketresearch, 2026-08-12
Worldwide Turbocharger Bearing Market: Strategic Imperatives for 2026 — PW Consulting Preview
As PW Consulting releases its latest market study on the Worldwide Turbocharger Bearing Market (base year: 2025; historical window: 2020–2025; forecast period: 2026–2032), this briefing highlights the report’s strategic value for executive decision-making in 2026. The study offers an integrated, commercially actionable view of a market that continues to expand under regulatory pressure, materials volatility and technology-driven product migration. Our forecast shows the market growing at a 5.25% CAGR through 2032, moving from a 2025 base of USD 2,150 Million to a multi-billion-dollar opportunity by 2032. This preview sets out the angles that matter to boardrooms, investment committees and product strategy teams — while reserving the granular segment data for the full report.
Decomposition Product Tester Market
Market Snapshot and What It Means for 2026
The turbocharger bearing market is at an inflection point where mechanical engineering meets emissions policy and supply-chain realism. After several years of steady growth through 2025, the market is projected to expand at a 5.25% compound annual growth rate across 2026–2032. The trajectory reflects continued OEM adoption of advanced bearing technologies (low-friction journal bearings, foil air bearings and hybrid ceramic bearings), growth in downsized and boosted internal combustion platforms, and increasing cross-industry demand from industrial, marine, and power-generation applications.
Metal Enclosures for Electrical Market
For decision-makers planning 2026 investments, two implications stand out: first, the upside is broad but requires targeted capability bets (materials engineering, high-speed dynamics, and thermal resilience); second, cost and supply risks have risen materially, meaning timing and procurement strategy will determine margin outcomes as much as product innovation.
Beating Homogenizer Market
Macro and Industry Dynamics Driving 2026 Choices
-
Regulatory acceleration: Stricter emissions rules — notably Euro 7 in Europe and stage-based heavy-duty engine standards in the U.S. — are increasing demand for turbocharger efficiency improvements. For example, forthcoming heavy-duty standards that target major NOx reductions will force turbocharger system upgrades across fleets, creating a near-term window for bearing upgrades and retrofits.
-
Materials and cost pressure: Supply-side pressures are acute. High-strength alloy steel prices rose ~8% in 2023 and copper inputs for bronze journal bearings experienced notable spikes. These input cost increases compress supplier margins and influence sourcing strategies — making raw material hedging, alternative metallurgy and supplier co-development essential topics for any 2026 procurement plan.
-
Geopolitical and trade considerations: Elevated tariffs and trade frictions have raised cross-border bearing costs and shifted localization calculus for OEMs and Tier 1s. Procurement footprints and nearshoring will be active agenda items in 2026 planning cycles.
-
Technology transitions: Electric turbochargers and e-boost systems change bearing requirements (higher rotational speeds, different thermal profiles), which favors suppliers with foil-air and hybrid-ceramic expertise. Investments in R&D and selective partnerships will determine who captures early-adopter share.
Competitive Landscape — What We Found
The market remains moderately concentrated, with the top three players accounting for roughly half of industry revenues and the top five controlling north of sixty percent — a structure that encourages both competitive specialization and M&A activity. Key incumbent strengths and near-term moves to watch include:
-
Schaeffler Group (Herzogenaurach, Germany) — a recognized leader in journal and foil-air bearings for automotive and commercial turbochargers. Their visible investments in next-generation foil technology position them well for e-turbo applications and OEM co-development programs.
-
SKF AB (Gothenburg, Sweden) — notable for hybrid ceramic and air-foil offerings targeted at high-speed turbo operation. Recent product introductions emphasize durability and lifecycle cost advantages in heavy-duty applications.
-
NTN Corporation and NSK Ltd. (Japan) — both remain strong in conventionally engineered roller and ball bearings, with a focus on low-friction designs for downsized passenger and heavy-duty engines.
-
The Timken Company and RBC Bearings (USA) — known for super-precision and specialty thrust/foil solutions respectively; both are active in niche, high-value segments such as aerospace, marine and power generation where service profiles and qualification timelines favor established suppliers.
-
JTEKT Corporation and Waukesha Bearings — offer depth in needle roller architectures and hydrodynamic journal/tilt-pad bearings that meet industrial turbocharger requirements.
Recent corporate activity (product launches, trade-show reveals, and regional exhibitions) signals a clear pattern: incumbents are accelerating product differentiation through materials science, bearing architecture and system-level partnerships with turbocharger OEMs. Competitive dynamics will center on technical validation cycles, qualification lead times, and aftermarket penetration.
Strategic Imperatives for 2026 Decision-Makers
For executives setting priorities in 2026, our analysis recommends a set of practical, prioritized actions that link technology, procurement and commercial positioning.
-
Prioritize material strategy and supplier co-development: Locking in alloy and copper supply via strategic contracts, co-investing in alternative alloys or coating technologies, and qualifying multi-source suppliers are essential. Without proactive measures, margin erosion from input inflation will continue.
-
Invest selectively in foil-air and ceramic-hybrid capabilities: These technologies carry premium margins in high-speed and e-turbo applications. Allocate a portion of R&D and M&A budgets to accelerate pathway-to-production for foil air-bearing systems or partnerships that shorten qualification timelines with major OEMs.
-
Align product roadmaps to regulatory timelines: Position upgrades and product launches to coincide with Euro 7 and upcoming heavy-duty compliance deadlines. There is a narrow commercialization window where OEMs prioritize validated suppliers; being first to qualify yields outsized share gains.
-
Sharpen aftermarket and service propositions: With many fleets deferring full vehicle replacements, retrofits and turbocharger rebuilds will be a growth pocket. Retain pricing power by bundling bearing upgrades with condition-monitoring and extended-life service agreements.
-
Prepare for M&A and capability-led partnerships: Use M&A selectively to acquire niche capabilities (e.g., foil fabrication, high-temperature ceramics) rather than only volume manufacturing. Smaller bolt-on acquisitions can accelerate time to market more effectively than greenfield development.
-
Scenario-ready procurement: Build upside/downside procurement models that incorporate raw material shock scenarios, tariff paths and supplier outage probabilities. Include pass-through frameworks so commercial teams can respond quickly to cost shocks without long negotiation cycles.
What the PW Consulting Report Delivers (Practical Components)
The full report is built around decision-useful modules designed for commercial, product and procurement teams:
-
Comprehensive market-sizing and growth scenarios — macro-backed forecasts (2026–2032) and sensitivity analyses under multiple regulatory and price-shock pathways.
-
Competitive benchmarking — supplier scorecards that assess technology depth, qualification timelines, manufacturing footprint, and aftermarket capability.
-
Technology and product roadmaps — comparative assessment of journal, ball/roller, foil-air and hybrid architectures, with lifecycle cost and performance tradeoffs.
-
Raw-material and cost-pass-through models — practical tools to quantify margin exposure and to stress-test procurement contracts under commodity price swings and tariff scenarios.
-
Go-to-market playbooks — OEM engagement strategies, qualification-timeline templates, and aftermarket commercialization checklists.
-
M&A and partnership heatmaps — prioritized targets by capability, region and valuation band, together with integration risk assessments.
-
Supply-chain risk map — node-level vulnerabilities, alternative sourcing routes, and recommended contingency mitigations for 12–36 month planning horizons.
Each module pairs quantitative models with executable recommendations — for example, a supplier qualification sequence with estimated lead-time, capex, and validation cost ranges — enabling 2026 program planning to move from strategy to implementation in months, not quarters.
How to Use This Intelligence in 2026
-
Boards: Use the forecast scenarios and concentration metrics to validate capital allocation, M&A appetite and risk tolerance for near-term deals.
-
Product leaders: Prioritize R&D sprints on foil-air and hybrid materials; secure OEM pilot programs timed against regulatory milestones.
-
Procurement: Execute layered supplier contracts with hedging and qualification contingencies informed by our raw-material sensitivity model.
-
Commercial teams: Rework customer propositions to include retrofit pathways and long-term service agreements that capture aftermarket recurring revenue.
Closing — Why This Matters Now
The turbocharger bearing market presents a classic strategic dilemma: expanding demand set against heightened input volatility and compressed qualification timetables. The top-three players already account for roughly half of industry revenue, and the top-five for well over sixty percent, which creates both barriers and opportunities for entrants and incumbents. For companies plotting 2026 moves, success will depend on integrating materials strategy, focused capability investments and nimble commercial execution.
PW Consulting’s report converts these high-level truths into operational plans: prioritised R&D investments, procurement hedges, deal targets and go-to-market sequences that can be actioned in 2026. The sections above outline the strategic stakes and practical levers; the full report contains the underlying models, segmented forecasts, and supplier-level analysis needed to execute with confidence.
Next Steps
To access the complete market models, our supplier scorecards, and the full set of scenario outputs — including granular segment-level forecasts and the proprietary matrices used to generate the 5.25% CAGR outlook — please consult the PW Consulting report landing page. The full dataset and playbooks are designed to be directly deployable into 2026 planning cycles and will support rapid decision-making across commercial, product and procurement teams.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pro Microphone Market Reaches USD 3,215.4 Million in 2025, Forecast to Grow at a 6.01% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Pro Microphone Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Professional Microphone Market delivers the evidence-based intelligence executives need to make confident 2026 decisions. Built on a 2020–2025 historical foundation and a 2026–2032 forecasting framework, the report quantifies the market trajectory and converts that insight into operational playbooks for product, procurement, channel, and M&A leaders. In summary: the professional microphone market reached USD 3,215.4 Million in 2025 and is forecast to expand at a 6.01% compound annual growth rate to roughly USD 4,834.8 Million by 2032. This growth creates clear opportunities — and specific risks — that require targeted strategic responses in 2026.
Portable Constant Temperature Amplification Nucleic Acid Analyzer Market
Why this report matters now
-
Decision alignment for 2026 budget cycles — deploy capital where growth and margin expansion intersect, and avoid areas where price compression or supply risk will erode returns.
Worldwide Asphalt Rollers Market -
Mitigating supply-chain stress — executable sourcing and inventory strategies that address rare-earth concentration, extended component lead times, and tariff exposure.
Worldwide Stainless Steel Sanitary Ware Market -
Commercial acceleration — playbooks for OEMs, pro audio brands, and channel partners to capture demand generated by streaming, podcasting, corporate AV upgrades, and the rebound in live performance spend.
-
M&A and partnership screening — a prioritized list of capability gaps and target archetypes to accelerate time-to-market for DSP-enabled, networked, and miniaturized product lines.
What the report contains — practical, actionable modules
-
Market sizing and validated forecasts (2020–2025 historical; 2026–2032 projection) with scenario variants to stress-test macro shocks.
-
Price and margin archetypes across product classes and channels, with guidance on where premiumization yields the best incremental EBITDA.
-
Supply-chain risk matrix — rare-earth dependence, component lead-time modeling, tariff pass-through scenarios, and a supplier-diversification playbook.
-
Competitive intelligence dossiers — capability maps, recent product moves, and tactical responses for incumbents and challengers.
-
Go-to-market blueprints — retailer and pro-channel strategies, enterprise tender playbooks, and direct-to-creator engagement models.
-
M&A screening toolkits — value-creation levers, integration risks, and prioritized target archetypes for bolt-on acquisitions.
-
Regulatory and sustainability compliance checklist (including RoHS and other EEE restrictions) and implications for product redesign and labeling.
Market snapshot & concentration dynamics
The market’s mid-decade size and projected trajectory signal a resilient, mid-single-digit expansion driven by multiple secular trends: professional content creation, broadcast technology refresh cycles, and recovery in live events and corporate AV investments. Market concentration is meaningful but not prohibitive — the top three firms account for a material share of sales while the top five consolidate a clear majority of the market’s leading brands. In practice, this structure creates both defendable franchises for incumbents and whitespace opportunities for nimble challengers that combine hardware with software and services.
Competitive landscape — capabilities and strategic positioning
Our analysis profiles the full spectrum of industry participants, from global incumbents to specialist boutique makers. Key strategic takeaways:
-
Heritage live-sound and wireless strength: Established names with deep pro-audio distribution and legacy catalogue advantage continue to defend lead positions in live sound and installed applications through brand trust and channel density.
-
Studio and broadcast premium: High-end manufacturers focused on studio condensers and precision measurement equipment retain margin advantage through product differentiation and strong placement in professional facilities.
-
Creator and entry-pro disruption: Newer entrants and value brands have successfully grown share among podcasters, streamers, and small studios by offering high performance at aggressive price-to-value ratios, often bundled with software and ecosystem features.
-
Networked audio and DSP convergence: Vendors launching Dante-enabled boundary microphones, integrated DSP, and low-noise condenser upgrades represent the fastest route to higher ASPs and recurring revenue through software services and firmware-enabled features.
Recent product activity reinforces these themes: companies across the spectrum have introduced ultra-low-noise condensers, integrated DSP/wireless systems, and Dante-enabled conferencing boundary mics — moves that validate the strategic importance of low self-noise, network interoperability, and wireless robustness in product roadmaps.
Industry headwinds and tailwinds
-
Raw materials and supplier concentration — a significant share of refined rare earth output is concentrated geographically, and the average price of key rare-earth oxides has experienced upward pressure. For dynamic microphone magnets and related components, this translates into input-cost volatility that can compress margins or force price increases if not proactively managed.
-
Component lead times — capacitors, ICs, and other electronic parts saw extended lead times throughout recent quarters; product planning must assume multi-quarter procurement windows and identify alternative form, fit, and function suppliers.
-
Trade-policy friction — tariffs on certain imported microphones can materially alter landed-cost economics for firms with concentrated manufacturing footprints. Nearshoring or tariff-classification strategies are no longer optional for cost-sensitive product lines.
-
Regulatory compliance — directives restricting hazardous substances continue to affect design, supplier selection, and certification timelines. Compliance-driven redesigns can create both cost pressure and a barrier to entry for smaller suppliers.
-
Demand-side accelerants — streaming, podcasting, esports, and corporate AV digitization are persistent growth vectors that reward products designed for ease-of-use, integrated software, and platform compatibility.
2026 Strategic playbook — prioritized moves for executive teams
PW Consulting’s recommended actions are organized by horizon and impact to help senior teams translate market signals into measurable outcomes in 2026.
-
Short term (0–12 months): secure critical components via multi-source agreements, hedge exposure to rare-earth price moves, and review tariff mitigation through alternative manufacturing locations or HTS reclassification strategies. Implement inventory buffers for long-lead components tied to critical SKUs.
-
Medium term (12–24 months): accelerate product lines that embed DSP and network connectivity (e.g., Dante, AES67), and launch feature tiers that enable subscription-based firmware or cloud services. Prioritize compliance-ready designs to reduce time-to-market risk for regulated geographies.
-
Strategic deals and M&A: target technical niche plays (miniature lavaliers, measurement mics, or DSP-software specialists) that can be integrated to expand margin pools and shorten time to market for new integrated offerings. Use our scoring model to evaluate five archetypes that deliver the best probability-adjusted returns.
-
Commercial and channel: bifurcate GTM by buyer segment — defend pro-channel relationships with service-level agreements and exclusive SKUs, while scaling direct-to-creator channels through bundled software, content partnerships, and influencer-driven trials.
-
Operational excellence: institute supplier KPIs tied to lead time and quality, and create a joint risk register with top suppliers. Conduct a tariff and tax optimization review to quantify landed-cost improvements from reshoring or contract manufacturing shifts.
How to use the full report
This press briefing highlights the macro trajectory, competitive dynamics, and operational levers that shape 2026 choices. The full PW Consulting report contains the proprietary datasets, scenario-model workbooks, and executable templates you need to implement the recommendations above — including downloadable procurement playbooks, M&A screening sheets, and regional market tables. For pricing-by-product, channel-specific margin models, and the full segmentation dataset, please consult the complete report on PW Consulting’s website or contact our industry team for a tailored briefing.
Final note — where to focus in 2026
As the professional microphone market grows into the mid-2030s, the winners will be those who combine differentiated acoustical IP and product design with modern supply-chain resilience and software-enabled revenue models. 2026 is the inflection year for many firms: moves made now on sourcing, platform partnerships, and product-tier strategy will determine who captures the higher-margin segments of the market and who is left to compete solely on price. PW Consulting’s Worldwide Pro Microphone Market report is designed to fast-track those decisions with validated data and playbooks you can act on immediately.
For detailed analysis of this topic, please visit the official page: Worldwide Pro Microphone Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Heavy Truck Battery Swap Stations Market Poised to Grow at a 21% CAGR
By pmarketresearch, 2026-08-12
PW Consulting Releases Strategic Brief: Worldwide Heavy Truck Battery Swap Stations Market — A 2026 Decision-Maker’s Guide
PW Consulting today publishes an executive briefing that previews our forthcoming in-depth market research report on the Worldwide Heavy Truck Battery Swap Stations Market. Built on a 2025 base year and a seven-year forecast horizon (2026–2032), the report synthesizes five years of historical market movement (2020–2025) and projects an accelerated adoption curve with a compound annual growth rate (CAGR) of 21.0% through 2032. The market—measured in USD millions—grew from the low hundreds in 2020 to USD 1,250 million in 2025 and is forecast to approach USD 4,747 million by 2032. For infrastructure owners, OEMs, fleet operators and energy partners preparing strategic moves in 2026, this briefing highlights the decision levers that matter while directing readers to the full report for proprietary segmentation and financial models.
Worldwide Silicon Friction Resistant Bronze Alloys Market
Why 2026 Is a Pivotal Year
-
Transition from pilots to rollouts: The market dynamics observed between 2020 and 2025 show a rapid transition from proof-of-concept deployments to early commercial networks. Our forecast quantifies the scale-up and identifies the inflection points where capex commitments and operational models will determine winners and losers.
Christmas Travel Market -
Standardization and interoperability: Regulatory and industry standard progress is reducing technical risk. Notably, recent group standards define upper bounds on system voltage and swap-time targets for heavy trucks—benchmarks that materially affect station design, battery form factor strategies and interoperability frameworks.
Smart Wearable Button Battery Market -
Market concentration: The heavy truck swap-station market is already meaningfully concentrated. Our analysis estimates that the top three firms command roughly two-thirds of the market, while the top five extend control to well over three-quarters. This concentration has strategic implications for new entrants and for potential partnership or consolidation plays.
Key Strategic Imperatives for 2026 Decision-Makers
-
Choose your route to scale: Build, partner or license. Our report provides a framework for evaluating full-ownership networks versus fleet-dedicated alliances and asset-light models. The right choice depends on balance-sheet capacity, access to site footprints, and the ability to control interoperability standards.
-
Optimize CAPEX/OPEX trade-offs under evolving standards: Station automation levels, battery handling systems and grid-upgrade strategies materially change lifecycle economics. We map out scenarios that link automation investments to swap throughput, downtime risk and technician requirements.
-
Site and grid triage for rollouts: A pragmatic deployment roadmap—prioritizing corridors, freight hubs and integrated fleet depots—will determine early cash-flow profiles. Grid capacity is a binding constraint for high-throughput stations; specifications for grid connection should be part of any site due diligence.
-
Commercial models and fleet contracts: Capturing recurring revenue via subscription, pay-per-swap or hybrid models requires coordinated battery ownership and warranty strategies. Our commercial model templates show pricing sensitivities and scenario-based payback timelines.
-
Regulatory capture and incentive timing: Where subsidy windows and local infrastructure programs exist, timing market entry to capture incentive support materially improves returns. Regulatory engagement and compliance with emerging technical standards will be a gating item for cross-operator compatibility.
Competitive Landscape: Who’s Shaping the Market Now
-
CATL (Ningde, China) — A major systems integrator whose heavy-duty swap network demonstrates end-to-end standardization across stations and battery packs; engineering focus is on standardized interfaces and fast-swap flows designed for very high-capacity batteries and short turnaround times. Recent field commissioning of a standardized heavy-duty station underscores CATL’s intent to set operational benchmarks.
-
Farizon Auto (Hangzhou, China) — Leverages OEM convergence with modular swap architectures optimized for specific logistics vehicle families. Its early network deployments show the advantages of OEM-aligned swap formats and tightly integrated vehicle-station ecosystems.
-
TGOOD (Shenzhen, China) — Positions as a turnkey provider for operators, combining station hardware, control software and maintenance operations; commercial deployments across multiple provinces illustrate its channel and project-execution capabilities.
-
Aulton New Energy (Wuxi, China) — Translates mass-transit swap expertise to heavy trucks, offering automated battery handling and station-level automation; its approach highlights the transferability of technology from buses to heavy-duty truck applications.
These vendors illustrate the strategic archetypes in the market—standard-setters, OEM-backed integrators, turnkey station suppliers and technology-transfer specialists. For established players and newcomers alike, the competitive task is less about raw capability and more about network economics, partner ecosystems and standards alignment.
Industry Dynamics and Operational Constraints
-
Technical standards: Recent government-endorsed standards set performance targets (including upper voltage limits and swap-time ceilings) that influence battery architecture and station automation investments. Compliance reduces fragmentation risk but raises the bar for engineering tolerances.
-
Grid and infrastructure requirements: High-throughput stations require robust grid connections and energy management systems. Grid reinforcement and local distribution coordination are frequently on the critical path for deployment timelines.
-
Component cost trajectories and supply chain: Large-format LFP packs and high-capacity swap batteries remain a major cost element. Economies of scale and supply chain localization are the primary levers to reduce pack costs over time.
-
Public policy and local incentives: Many jurisdictions are offering targeted incentives to accelerate rollout. Capturing these incentives requires nimble project execution and adherence to eligibility rules, which vary by location and program.
What the PW Consulting Report Contains (Actionable Modules)
Our full report is organized to support immediate 2026 action planning. Key components include:
-
Market sizing and forecasting models (base year 2025) with downloadable, scenario-driven financial models that allow users to test sensitivity to throughput, pricing and capex assumptions.
-
Deployment playbooks detailing site selection criteria, phasing strategies, and rollout sequencing optimized for commercial and fleet-first approaches.
-
Capex and opex benchmarking across automation levels and station formats, with cost drivers and risk levers identified for procurement teams.
-
Regulatory and standards compendium outlining technical requirements, certification pathways and implications for interoperability.
-
Competitive matrix and vendor scorecards that evaluate technology fit, execution capacity, partnership openness and potential M&A targets.
-
Commercial templates—for swap pricing, subscription structures, fleet contracts and revenue-sharing agreements—ready to be adapted to specific markets.
-
Investment case studies and scenario-based IRR/payback analyses under multiple market adoption curves.
-
Risk register and mitigation playbook covering technical, commercial, regulatory and grid-related risks.
How to Use This Intelligence in 2026
-
For OEMs: Use the report to decide whether to standardize battery interfaces, pursue owner-operated stations, or align with third-party networks to protect long-term vehicle value and customer proposition.
-
For fleet operators: Evaluate whether to co-invest in fleet-dedicated stations or partner with public networks. Our sensitivity models help determine the threshold utilization rates at which each option becomes preferable.
-
For energy and infrastructure investors: Prioritize investments in grid-enabled sites and energy-storage co-locations that improve station economics and deliver ancillary grid services.
-
For station operators and system suppliers: Benchmark automation choices, O&M staffing models and spare-parts strategies to reduce downtime and improve throughput.
Why PW Consulting’s Analysis Is Distinctive
-
Integrated perspective: We combine market-sizing rigour with engineering realism and commercial templates—bridging the gap between strategic forecasts and executable roll-out plans.
-
Scenario-driven tools: Instead of a single forecast narrative, subscribers receive modular financial models that stress-test business cases under alternative adoption trajectories.
-
Vendor-agnostic operational playbooks: Our recommendations are oriented toward pragmatic decision-making—what to build, when to partner, and how to protect optionality as standards and technology evolve.
Next Steps and Accessing the Full Report
This briefing is a preview designed to equip senior leaders with the strategic framing necessary for 2026 decision-making. The full PW Consulting report contains the detailed segmentation, proprietary unit-cost models, and granular regional analyses that underpin the conclusions summarized here. Organizations seeking to translate this intelligence into an actionable 12–24 month plan can commission a tailored advisory engagement, access the full report, or request the downloadable financial model.
To request the complete report or to discuss a bespoke advisory engagement, please contact PW Consulting’s Heavy Transportation and Energy Infrastructure practice. Our team will help you rapidly convert market insight into investment-grade plans.
PW Consulting — translating market foresight into executable strategy for the heavy-duty electrification era.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy Truck Battery Swap Stations Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Image Signal Processor Market to Hit USD 8.8 Billion by 2032, Growing at a 13.01% CAGR—Asia Pacific Leads with USD 1.79B in 2025
By pmarketresearch, 2026-08-12
Worldwide Automotive Image Signal Processor Market: Strategic Insights for 2026 Decision-Makers
PW Consulting — Official Release (based on our 2025 base year study)
The market for automotive Image Signal Processors (ISPs) has shifted from a niche enabling technology to a central pillar of vehicle perception, occupant monitoring, and safety-systems architectures. Our new Worldwide Automotive Image Signal Processor Market report — using 2025 as the base year and projecting across a 2026–2032 forecast horizon — synthesizes technology roadmaps, supplier economics, regulatory pressure points, and program-level demand signals to give senior executives the action-oriented intelligence needed to make confident decisions in 2026.
Research Cell Analyzers Market
Why this market matters in 2026
ISPs are no longer “image tuning” peripherals. They are compute elements that determine how camera-based sensors translate photons into reliable inputs for ADAS, automated driving stacks, and in-cabin systems. The sector is expanding rapidly: our market model shows growth from roughly USD 2.15 billion in 2020 to USD 3.74 billion in 2025, with projections that place the market near USD 8.80 billion by 2032 — an implied compound annual growth rate of 13.01% over the forecast period. Concentration is meaningful: the top three suppliers control a clear majority of market value, and the top five extend that dominance further, creating both challenges and windows of opportunity for new entrants and OEM procurement strategies.
Human Skin Equivalent Market
What the PW Consulting report delivers (practical, decision-ready content)
- Market-sizing and validated demand model: a bottom-up revenue model calibrated to automotive program cadences and camera content-per-vehicle trends across light-vehicle platforms (global forecast 2026–2032).
- Technology deep dives: comparative analysis of integrated vs. standalone ISP architectures; HDR and multi-exposure pipelines; AI/NPU integration trends; and the emerging role of MIPI A-PHY and sensor-ISP co-design for high-bandwidth applications.
- Supplier landscaping and heat maps: competitive positioning, go-to-market motions, design-win velocity, and a proprietary supplier-readiness index for ADAS and in-cabin use cases.
- Regulatory and supply-risk assessment: scenarios that quantify the potential impact of tariffs, raw-material constraints, and lead-time variability on program-level BOMs and supplier selection.
- Strategic playbooks: templates for sourcing negotiations, tiered-supplier strategies, modularization vs. integration decisions, and M&A/partnership screening criteria tailored to 2026 objectives.
- Executive-ready dashboards: KPIs and trigger points for procurement, R&D prioritization, and product roadmap alignment — designed to be used in quarterly board discussions.
How the findings change 2026 decision-making — three priority implications
- Architectural posture matters: ISPs are becoming design choices with systems-level consequences. Choosing integrated SoCs vs. standalone ISPs affects supplier leverage, update cadence for algorithms, and functional-safety pathways. Our scenario analysis quantifies the trade-offs for both near-term cost and medium-term TCO.
- Safety and certification will drive supplier selection: With recent certifications and ASIL compliance progress, functional-safety readiness is now a procurement filter, not an afterthought. Programs that lock into suppliers without certified IP risk costly redesigns as OEMs move to higher ADAS levels.
- Supply-chain and trade policy risk is real: New trade measures and extended semiconductor lead times materially change the risk profile of single-source strategies. The report provides probability-weighted impact analyses that map potential tariff scenarios to supplier cost uplifts and schedule slippage.
Competitive landscape — who matters and why
The ISP ecosystem blends pure-play image specialists, broad-based semiconductor houses, and system-SoC providers. PW Consulting profiles the active competitive set and assesses strategic levers for each player class:
Worldwide Wind Turbine Maintenance, Repair & Overhaul (MRO) Market
- onsemi (Semiconductor Components Industries, LLC) — a supplier with automotive-dedicated ISP co-processors optimized for HDR sensors; their automotive focus and sensor partnerships make them a compelling partner for surround-view and ADAS programs that emphasize low-latency pipelines.
- OmniVision Technologies — offers a portfolio of automotive ISPs and companion processors with integrated NPUs and advanced HDR/LED-flicker mitigation; suited to customers prioritizing sensor-to-perception integration and OEMs seeking compact camera-module stacks.
- STMicroelectronics — integrates ISP capabilities within broader sensor and vision portfolios, appealing to Tier-1s aiming to simplify system integration and accelerate time-to-market for zonal architectures.
- Texas Instruments — leverages broad analog-to-digital and vision ecosystems, serving programs where mixed-signal integration and robust automotive-grade supply are primary concerns.
- NXP Semiconductors — positions ISP functionality within platform processors (e.g., i.MX derivatives), attractive when OEMs or Tier-1s seek consolidated compute platforms with software ecosystems.
- Renesas Electronics — focuses on vision processors and ISP capability tuned to automotive-grade requirements, especially where integration with microcontroller domains is a program priority.
- Nextchip — differentiates through ADAS/SoC offerings targeted at L2+ to L3 deployments, appealing to customers across markets looking for performance at scale.
- VeriSilicon — supplies automotive ISP IP with high throughput and a growing functional-safety pedigree, making it a go-to for companies seeking licensable ISP cores with ISO 26262 certifications.
- Sony Semiconductor Solutions — as a sensor leader, Sony’s moves (including the introduction of sensor interfaces like MIPI A-PHY) influence ISP requirements and camera-module economics; pairing Sony sensors with tuned ISP pipelines yields performance differentiation.
- Ambarella — brings high-performance vision SoCs with advanced ISP stacks for compute-heavy ADAS applications, attractive where local perception and compression are both required.
- Qualcomm — integrates ISP capability into vehicle platforms and infotainment/AD stacks, offering software ecosystems and long-tail support beneficial for connected-vehicle strategies.
Recent developments underscore dynamic competitive shifts: Sony’s IMX828 (announced Oct 2025) introduced a MIPI A-PHY-enabled sensor with extended HDR capability; VeriSilicon achieved ISO 26262 certification for a second-generation ISP IP (Feb 2026); and specialist IP upgrades from logicBRICKS enhanced RGB-IR processing in 2025. Each event alters technical ceilings and procurement considerations for OEMs and Tier-1s.
Risk vectors and regulatory dynamics to watch in 2026
- Trade policy and tariffs: Recent U.S. measures imposing duties on certain advanced computing chips and ongoing Section 232 negotiations introduce near-term price and sourcing uncertainty. Our report models tariff pass-through scenarios and recommended sourcing hedges.
- Supply-chain strain: Automotive semiconductor lead times lengthened materially in late 2025; the report models how two-week shifts in lead time cascade into program buffer needs and just-in-time inventory policies.
- Functional safety and certification: With IP vendors and partners reaching ASIL-B/D milestones, OEMs must elevate certification timelines into supplier selection criteria to avoid late-stage rework.
- Technology obsolescence and software risk: Rapid innovation in NPUs, HDR pipelines, and interface standards (e.g., MIPI A-PHY) means hardware choices lock software constraints; our scenario planning quantifies upgrade costs across multiple product lifecycles.
How to use this intelligence in 2026 — tactical next steps for leaders
- Procurement: Re-calibrate supplier scorecards to include functional-safety readiness, A-PHY interface support, and roadmap alignment for AI-enabled pipelines; activate dual-sourcing where tariff exposure or lead-time sensitivity is high.
- R&D and product planning: Prioritize sensor-ISP co-development in projects targeting high-HDR or multi-sensor perception; budget for incremental software headroom to exploit on-chip NPUs.
- M&A and partnerships: Use our supplier-readiness index and thermal maps to shortlist acquisition or JV targets that close capability gaps (e.g., certified ISP IP, high-throughput pipelines, or sensor integration competencies).
- Risk mitigation: Implement trigger-based inventory buffers tied to lead-time and tariff scenarios modeled in the report; negotiate price-protection clauses with strategic suppliers.
- Regulatory preparedness: Integrate ISO 26262 milestones into program Gantt charts and require proof points for ASIL compliance in early design phases.
About the market model and confidence in our projections
Our forecast combines demand-side indicators (vehicle production, camera content per vehicle, ADAS penetration curves) with supply-side modelling (supplier capacity, wafer constraints, and BOM change dynamics). Scenario sensitivity testing around tariffs, lead-time shocks, and accelerated ADAS adoption informs our central 13.01% CAGR projection and the pathway to approximately USD 8.80 billion by 2032. The model is designed for iterative use — teams can re-run scenarios with program-specific inputs using templates included with the report.
Next steps — access and engagement
This release is an executive preview designed to highlight the strategic value of the full report. The complete study contains granular, program-level intelligence (including supplier matrices, build-cost frameworks, and downloadable model files) that we intentionally withhold here to protect the actionable core of the research. PW Consulting offers tailored briefings, workshop sessions to map these findings into client roadmaps, and customized scenario runs for procurement and M&A teams.
For procurement leaders, systems architects, and corporate strategists preparing 2026 budgets and roadmap commitments, the report provides the decision-ready analytics needed to balance performance, safety, and supply security in an ISP-driven world. To request the full report or schedule a briefing, please visit the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Image Signal Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com