

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
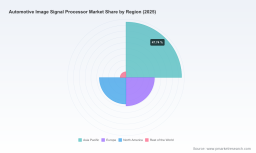
PW Consulting: Automotive Image Signal Processor Market to Hit USD 8.8 Billion by 2032, Growing at a 13.01% CAGR—Asia Pacific Leads with USD 1.79B in 2025

Worldwide Automotive Image Signal Processor Market: Strategic Insights for 2026 Decision-Makers
PW Consulting — Official Release (based on our 2025 base year study)
The market for automotive Image Signal Processors (ISPs) has shifted from a niche enabling technology to a central pillar of vehicle perception, occupant monitoring, and safety-systems architectures. Our new Worldwide Automotive Image Signal Processor Market report — using 2025 as the base year and projecting across a 2026–2032 forecast horizon — synthesizes technology roadmaps, supplier economics, regulatory pressure points, and program-level demand signals to give senior executives the action-oriented intelligence needed to make confident decisions in 2026.
Research Cell Analyzers Market
Why this market matters in 2026
ISPs are no longer “image tuning” peripherals. They are compute elements that determine how camera-based sensors translate photons into reliable inputs for ADAS, automated driving stacks, and in-cabin systems. The sector is expanding rapidly: our market model shows growth from roughly USD 2.15 billion in 2020 to USD 3.74 billion in 2025, with projections that place the market near USD 8.80 billion by 2032 — an implied compound annual growth rate of 13.01% over the forecast period. Concentration is meaningful: the top three suppliers control a clear majority of market value, and the top five extend that dominance further, creating both challenges and windows of opportunity for new entrants and OEM procurement strategies.
Human Skin Equivalent Market
What the PW Consulting report delivers (practical, decision-ready content)
- Market-sizing and validated demand model: a bottom-up revenue model calibrated to automotive program cadences and camera content-per-vehicle trends across light-vehicle platforms (global forecast 2026–2032).
- Technology deep dives: comparative analysis of integrated vs. standalone ISP architectures; HDR and multi-exposure pipelines; AI/NPU integration trends; and the emerging role of MIPI A-PHY and sensor-ISP co-design for high-bandwidth applications.
- Supplier landscaping and heat maps: competitive positioning, go-to-market motions, design-win velocity, and a proprietary supplier-readiness index for ADAS and in-cabin use cases.
- Regulatory and supply-risk assessment: scenarios that quantify the potential impact of tariffs, raw-material constraints, and lead-time variability on program-level BOMs and supplier selection.
- Strategic playbooks: templates for sourcing negotiations, tiered-supplier strategies, modularization vs. integration decisions, and M&A/partnership screening criteria tailored to 2026 objectives.
- Executive-ready dashboards: KPIs and trigger points for procurement, R&D prioritization, and product roadmap alignment — designed to be used in quarterly board discussions.
How the findings change 2026 decision-making — three priority implications
- Architectural posture matters: ISPs are becoming design choices with systems-level consequences. Choosing integrated SoCs vs. standalone ISPs affects supplier leverage, update cadence for algorithms, and functional-safety pathways. Our scenario analysis quantifies the trade-offs for both near-term cost and medium-term TCO.
- Safety and certification will drive supplier selection: With recent certifications and ASIL compliance progress, functional-safety readiness is now a procurement filter, not an afterthought. Programs that lock into suppliers without certified IP risk costly redesigns as OEMs move to higher ADAS levels.
- Supply-chain and trade policy risk is real: New trade measures and extended semiconductor lead times materially change the risk profile of single-source strategies. The report provides probability-weighted impact analyses that map potential tariff scenarios to supplier cost uplifts and schedule slippage.
Competitive landscape — who matters and why
The ISP ecosystem blends pure-play image specialists, broad-based semiconductor houses, and system-SoC providers. PW Consulting profiles the active competitive set and assesses strategic levers for each player class:
Worldwide Wind Turbine Maintenance, Repair & Overhaul (MRO) Market
- onsemi (Semiconductor Components Industries, LLC) — a supplier with automotive-dedicated ISP co-processors optimized for HDR sensors; their automotive focus and sensor partnerships make them a compelling partner for surround-view and ADAS programs that emphasize low-latency pipelines.
- OmniVision Technologies — offers a portfolio of automotive ISPs and companion processors with integrated NPUs and advanced HDR/LED-flicker mitigation; suited to customers prioritizing sensor-to-perception integration and OEMs seeking compact camera-module stacks.
- STMicroelectronics — integrates ISP capabilities within broader sensor and vision portfolios, appealing to Tier-1s aiming to simplify system integration and accelerate time-to-market for zonal architectures.
- Texas Instruments — leverages broad analog-to-digital and vision ecosystems, serving programs where mixed-signal integration and robust automotive-grade supply are primary concerns.
- NXP Semiconductors — positions ISP functionality within platform processors (e.g., i.MX derivatives), attractive when OEMs or Tier-1s seek consolidated compute platforms with software ecosystems.
- Renesas Electronics — focuses on vision processors and ISP capability tuned to automotive-grade requirements, especially where integration with microcontroller domains is a program priority.
- Nextchip — differentiates through ADAS/SoC offerings targeted at L2+ to L3 deployments, appealing to customers across markets looking for performance at scale.
- VeriSilicon — supplies automotive ISP IP with high throughput and a growing functional-safety pedigree, making it a go-to for companies seeking licensable ISP cores with ISO 26262 certifications.
- Sony Semiconductor Solutions — as a sensor leader, Sony’s moves (including the introduction of sensor interfaces like MIPI A-PHY) influence ISP requirements and camera-module economics; pairing Sony sensors with tuned ISP pipelines yields performance differentiation.
- Ambarella — brings high-performance vision SoCs with advanced ISP stacks for compute-heavy ADAS applications, attractive where local perception and compression are both required.
- Qualcomm — integrates ISP capability into vehicle platforms and infotainment/AD stacks, offering software ecosystems and long-tail support beneficial for connected-vehicle strategies.
Recent developments underscore dynamic competitive shifts: Sony’s IMX828 (announced Oct 2025) introduced a MIPI A-PHY-enabled sensor with extended HDR capability; VeriSilicon achieved ISO 26262 certification for a second-generation ISP IP (Feb 2026); and specialist IP upgrades from logicBRICKS enhanced RGB-IR processing in 2025. Each event alters technical ceilings and procurement considerations for OEMs and Tier-1s.
Risk vectors and regulatory dynamics to watch in 2026
- Trade policy and tariffs: Recent U.S. measures imposing duties on certain advanced computing chips and ongoing Section 232 negotiations introduce near-term price and sourcing uncertainty. Our report models tariff pass-through scenarios and recommended sourcing hedges.
- Supply-chain strain: Automotive semiconductor lead times lengthened materially in late 2025; the report models how two-week shifts in lead time cascade into program buffer needs and just-in-time inventory policies.
- Functional safety and certification: With IP vendors and partners reaching ASIL-B/D milestones, OEMs must elevate certification timelines into supplier selection criteria to avoid late-stage rework.
- Technology obsolescence and software risk: Rapid innovation in NPUs, HDR pipelines, and interface standards (e.g., MIPI A-PHY) means hardware choices lock software constraints; our scenario planning quantifies upgrade costs across multiple product lifecycles.
How to use this intelligence in 2026 — tactical next steps for leaders
- Procurement: Re-calibrate supplier scorecards to include functional-safety readiness, A-PHY interface support, and roadmap alignment for AI-enabled pipelines; activate dual-sourcing where tariff exposure or lead-time sensitivity is high.
- R&D and product planning: Prioritize sensor-ISP co-development in projects targeting high-HDR or multi-sensor perception; budget for incremental software headroom to exploit on-chip NPUs.
- M&A and partnerships: Use our supplier-readiness index and thermal maps to shortlist acquisition or JV targets that close capability gaps (e.g., certified ISP IP, high-throughput pipelines, or sensor integration competencies).
- Risk mitigation: Implement trigger-based inventory buffers tied to lead-time and tariff scenarios modeled in the report; negotiate price-protection clauses with strategic suppliers.
- Regulatory preparedness: Integrate ISO 26262 milestones into program Gantt charts and require proof points for ASIL compliance in early design phases.
About the market model and confidence in our projections
Our forecast combines demand-side indicators (vehicle production, camera content per vehicle, ADAS penetration curves) with supply-side modelling (supplier capacity, wafer constraints, and BOM change dynamics). Scenario sensitivity testing around tariffs, lead-time shocks, and accelerated ADAS adoption informs our central 13.01% CAGR projection and the pathway to approximately USD 8.80 billion by 2032. The model is designed for iterative use — teams can re-run scenarios with program-specific inputs using templates included with the report.
Next steps — access and engagement
This release is an executive preview designed to highlight the strategic value of the full report. The complete study contains granular, program-level intelligence (including supplier matrices, build-cost frameworks, and downloadable model files) that we intentionally withhold here to protect the actionable core of the research. PW Consulting offers tailored briefings, workshop sessions to map these findings into client roadmaps, and customized scenario runs for procurement and M&A teams.
For procurement leaders, systems architects, and corporate strategists preparing 2026 budgets and roadmap commitments, the report provides the decision-ready analytics needed to balance performance, safety, and supply security in an ISP-driven world. To request the full report or schedule a briefing, please visit the PW Consulting research portal.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Image Signal Processor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com