

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Turbocharger Bearing Market to Reach USD 3,075.89 Million by 2032, Growing at a 5.25% CAGR

Worldwide Turbocharger Bearing Market: Strategic Imperatives for 2026 — PW Consulting Preview
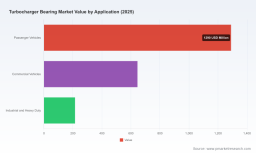
As PW Consulting releases its latest market study on the Worldwide Turbocharger Bearing Market (base year: 2025; historical window: 2020–2025; forecast period: 2026–2032), this briefing highlights the report’s strategic value for executive decision-making in 2026. The study offers an integrated, commercially actionable view of a market that continues to expand under regulatory pressure, materials volatility and technology-driven product migration. Our forecast shows the market growing at a 5.25% CAGR through 2032, moving from a 2025 base of USD 2,150 Million to a multi-billion-dollar opportunity by 2032. This preview sets out the angles that matter to boardrooms, investment committees and product strategy teams — while reserving the granular segment data for the full report.
Decomposition Product Tester Market
Market Snapshot and What It Means for 2026
The turbocharger bearing market is at an inflection point where mechanical engineering meets emissions policy and supply-chain realism. After several years of steady growth through 2025, the market is projected to expand at a 5.25% compound annual growth rate across 2026–2032. The trajectory reflects continued OEM adoption of advanced bearing technologies (low-friction journal bearings, foil air bearings and hybrid ceramic bearings), growth in downsized and boosted internal combustion platforms, and increasing cross-industry demand from industrial, marine, and power-generation applications.
Metal Enclosures for Electrical Market
For decision-makers planning 2026 investments, two implications stand out: first, the upside is broad but requires targeted capability bets (materials engineering, high-speed dynamics, and thermal resilience); second, cost and supply risks have risen materially, meaning timing and procurement strategy will determine margin outcomes as much as product innovation.
Beating Homogenizer Market
Macro and Industry Dynamics Driving 2026 Choices
-
Regulatory acceleration: Stricter emissions rules — notably Euro 7 in Europe and stage-based heavy-duty engine standards in the U.S. — are increasing demand for turbocharger efficiency improvements. For example, forthcoming heavy-duty standards that target major NOx reductions will force turbocharger system upgrades across fleets, creating a near-term window for bearing upgrades and retrofits.
-
Materials and cost pressure: Supply-side pressures are acute. High-strength alloy steel prices rose ~8% in 2023 and copper inputs for bronze journal bearings experienced notable spikes. These input cost increases compress supplier margins and influence sourcing strategies — making raw material hedging, alternative metallurgy and supplier co-development essential topics for any 2026 procurement plan.
-
Geopolitical and trade considerations: Elevated tariffs and trade frictions have raised cross-border bearing costs and shifted localization calculus for OEMs and Tier 1s. Procurement footprints and nearshoring will be active agenda items in 2026 planning cycles.
-
Technology transitions: Electric turbochargers and e-boost systems change bearing requirements (higher rotational speeds, different thermal profiles), which favors suppliers with foil-air and hybrid-ceramic expertise. Investments in R&D and selective partnerships will determine who captures early-adopter share.
Competitive Landscape — What We Found
The market remains moderately concentrated, with the top three players accounting for roughly half of industry revenues and the top five controlling north of sixty percent — a structure that encourages both competitive specialization and M&A activity. Key incumbent strengths and near-term moves to watch include:
-
Schaeffler Group (Herzogenaurach, Germany) — a recognized leader in journal and foil-air bearings for automotive and commercial turbochargers. Their visible investments in next-generation foil technology position them well for e-turbo applications and OEM co-development programs.
-
SKF AB (Gothenburg, Sweden) — notable for hybrid ceramic and air-foil offerings targeted at high-speed turbo operation. Recent product introductions emphasize durability and lifecycle cost advantages in heavy-duty applications.
-
NTN Corporation and NSK Ltd. (Japan) — both remain strong in conventionally engineered roller and ball bearings, with a focus on low-friction designs for downsized passenger and heavy-duty engines.
-
The Timken Company and RBC Bearings (USA) — known for super-precision and specialty thrust/foil solutions respectively; both are active in niche, high-value segments such as aerospace, marine and power generation where service profiles and qualification timelines favor established suppliers.
-
JTEKT Corporation and Waukesha Bearings — offer depth in needle roller architectures and hydrodynamic journal/tilt-pad bearings that meet industrial turbocharger requirements.
Recent corporate activity (product launches, trade-show reveals, and regional exhibitions) signals a clear pattern: incumbents are accelerating product differentiation through materials science, bearing architecture and system-level partnerships with turbocharger OEMs. Competitive dynamics will center on technical validation cycles, qualification lead times, and aftermarket penetration.
Strategic Imperatives for 2026 Decision-Makers
For executives setting priorities in 2026, our analysis recommends a set of practical, prioritized actions that link technology, procurement and commercial positioning.
-
Prioritize material strategy and supplier co-development: Locking in alloy and copper supply via strategic contracts, co-investing in alternative alloys or coating technologies, and qualifying multi-source suppliers are essential. Without proactive measures, margin erosion from input inflation will continue.
-
Invest selectively in foil-air and ceramic-hybrid capabilities: These technologies carry premium margins in high-speed and e-turbo applications. Allocate a portion of R&D and M&A budgets to accelerate pathway-to-production for foil air-bearing systems or partnerships that shorten qualification timelines with major OEMs.
-
Align product roadmaps to regulatory timelines: Position upgrades and product launches to coincide with Euro 7 and upcoming heavy-duty compliance deadlines. There is a narrow commercialization window where OEMs prioritize validated suppliers; being first to qualify yields outsized share gains.
-
Sharpen aftermarket and service propositions: With many fleets deferring full vehicle replacements, retrofits and turbocharger rebuilds will be a growth pocket. Retain pricing power by bundling bearing upgrades with condition-monitoring and extended-life service agreements.
-
Prepare for M&A and capability-led partnerships: Use M&A selectively to acquire niche capabilities (e.g., foil fabrication, high-temperature ceramics) rather than only volume manufacturing. Smaller bolt-on acquisitions can accelerate time to market more effectively than greenfield development.
-
Scenario-ready procurement: Build upside/downside procurement models that incorporate raw material shock scenarios, tariff paths and supplier outage probabilities. Include pass-through frameworks so commercial teams can respond quickly to cost shocks without long negotiation cycles.
What the PW Consulting Report Delivers (Practical Components)
The full report is built around decision-useful modules designed for commercial, product and procurement teams:
-
Comprehensive market-sizing and growth scenarios — macro-backed forecasts (2026–2032) and sensitivity analyses under multiple regulatory and price-shock pathways.
-
Competitive benchmarking — supplier scorecards that assess technology depth, qualification timelines, manufacturing footprint, and aftermarket capability.
-
Technology and product roadmaps — comparative assessment of journal, ball/roller, foil-air and hybrid architectures, with lifecycle cost and performance tradeoffs.
-
Raw-material and cost-pass-through models — practical tools to quantify margin exposure and to stress-test procurement contracts under commodity price swings and tariff scenarios.
-
Go-to-market playbooks — OEM engagement strategies, qualification-timeline templates, and aftermarket commercialization checklists.
-
M&A and partnership heatmaps — prioritized targets by capability, region and valuation band, together with integration risk assessments.
-
Supply-chain risk map — node-level vulnerabilities, alternative sourcing routes, and recommended contingency mitigations for 12–36 month planning horizons.
Each module pairs quantitative models with executable recommendations — for example, a supplier qualification sequence with estimated lead-time, capex, and validation cost ranges — enabling 2026 program planning to move from strategy to implementation in months, not quarters.
How to Use This Intelligence in 2026
-
Boards: Use the forecast scenarios and concentration metrics to validate capital allocation, M&A appetite and risk tolerance for near-term deals.
-
Product leaders: Prioritize R&D sprints on foil-air and hybrid materials; secure OEM pilot programs timed against regulatory milestones.
-
Procurement: Execute layered supplier contracts with hedging and qualification contingencies informed by our raw-material sensitivity model.
-
Commercial teams: Rework customer propositions to include retrofit pathways and long-term service agreements that capture aftermarket recurring revenue.
Closing — Why This Matters Now
The turbocharger bearing market presents a classic strategic dilemma: expanding demand set against heightened input volatility and compressed qualification timetables. The top-three players already account for roughly half of industry revenue, and the top-five for well over sixty percent, which creates both barriers and opportunities for entrants and incumbents. For companies plotting 2026 moves, success will depend on integrating materials strategy, focused capability investments and nimble commercial execution.
PW Consulting’s report converts these high-level truths into operational plans: prioritised R&D investments, procurement hedges, deal targets and go-to-market sequences that can be actioned in 2026. The sections above outline the strategic stakes and practical levers; the full report contains the underlying models, segmented forecasts, and supplier-level analysis needed to execute with confidence.
Next Steps
To access the complete market models, our supplier scorecards, and the full set of scenario outputs — including granular segment-level forecasts and the proprietary matrices used to generate the 5.25% CAGR outlook — please consult the PW Consulting report landing page. The full dataset and playbooks are designed to be directly deployable into 2026 planning cycles and will support rapid decision-making across commercial, product and procurement teams.
For detailed analysis of this topic, please visit the official page: Worldwide Turbocharger Bearing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com