

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Deicing Salt Market to Top USD 3,447 Million by 2032, Expanding at a 3.55% CAGR (Forecast 2026–2032)

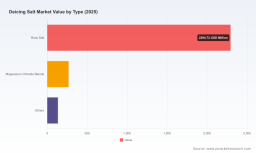
Worldwide Deicing Salt Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases a strategic briefing drawn from our forthcoming Worldwide Deicing Salt Market report (base year 2025, historical coverage 2020–2025, forecast 2026–2032). This briefing distills the high‑impact insights that will matter most to executives making procurement, capital allocation, regulatory compliance, and M&A decisions in 2026. The market is projected to expand at a steady compound annual growth rate (CAGR) of 3.55% across the 2026–2032 forecast window, extending a measured recovery and structural adjustment that began in the early 2020s. Our analysis synthesizes price, capacity, regulatory and environmental vectors into actionable scenarios — while reserving detailed segment-level tables and proprietary model outputs for the full report.
Worldwide Industrial Rugged Smartphone Market
Market snapshot: steady growth, concentrated incumbency, and operational headwinds
PW Consulting’s topline model estimates the global deicing salt market at approximately 2.7 billion USD (revenue unit: Million, base year 2025), up from roughly 2.27 billion USD in 2020. Under our central forecast, the market reaches roughly 3.45 billion USD by 2032. Growth at a 3.55% CAGR reflects a mix of volume recovery in transportation maintenance, incremental premiumization through treated and blended products, and regional policy-driven substitution toward lower-chloride alternatives in environmentally sensitive areas.
Worldwide Anisotropic Conductive Film (ACF) Tape Market
Market concentration remains moderate: the three largest producers account for a little over one‑fifth of global supply, while the top five account for just under one‑third. That structure leaves room for national champions, regional miners, and smaller specialty suppliers to exert outsized influence in local tender markets and niche product categories.
Worldwide Massage Therapy Software Market
Why this report matters for 2026 planning
- Procurement optimization: Procurement teams should anticipate persistently elevated input cost volatility (notably energy and packaging) even as volumes grow. Our demand/supply scenarios quantify how a 5–10% swing in mining energy costs or imported container tariffs propagates into landed costs — crucial for RFP timing and contract length decisions.
- Capex and capacity planning: Capital planners will find the report’s scenario-based mine and evaporation‑facility utilization curves essential for deciding whether to accelerate expansions, pursue brownfield upgrades, or defer investment until pricing stabilizes.
- Regulatory compliance and product strategy: With tightening chloride discharge limits in parts of Europe and growing preference in North America for corrosion‑mitigating blends, our strategic playbook maps R&D prioritization and go‑to‑market timing for low‑chloride and corrosion‑inhibited products.
- M&A and partnership targeting: The moderate concentration ratio indicates acquisition targets exist across the value chain. Our company-screening matrix combines financial health, reserve life, and local regulatory exposure to highlight deals that materially improve a buyer’s route to market or technical capability.
Key market dynamics shaping 2026 decisions
- Raw material and energy cost pressure: PW Consulting observed that underground rock salt mining faced higher operational input costs in 2024 — energy intensity translated into an 8–12% rise in unit mining costs in many operations. Evaporation facilities also remained sensitive to natural gas prices; North American evaporation margins were influenced by average natural gas prices near $3.50/MMBtu in late 2024. Procurement and hedging strategies must factor these drivers into both short and multi‑year contracts.
- Packaging and logistics: Trade policy and tariffs have a tangible bearing on delivered costs. For example, tariffs that increased the landed cost of steel containers last cycle raised packaging expense by several percentage points for import‑dependent suppliers. Organizations reliant on cross‑border packaged deliveries will need to review packaging strategies and nearshore manufacturing options.
- Environmental regulation and product substitution: Environmental directives that restrict chloride discharge in sensitive waterways are accelerating demand for lower‑chloride alternatives and magnesium‑based blends in certain jurisdictions. Concurrently, North American regulatory guidance favoring magnesium chloride blends to reduce infrastructure corrosion is shifting procurement specifications for highway and airport authorities.
- Product innovation and differentiators: Treated salts and corrosion‑inhibited formulations are transitioning from niche to mainstream for infrastructure‑sensitive customers. Value capture will lie in formulations that demonstrably reduce corrosive impact while preserving deicing performance, and in commercialization pathways that minimize price premium friction.
Competitive landscape — strategic implications from leading players
The market’s leading global and regional suppliers deploy differing strategies that provide a template for both incumbents and challengers:
- Cargill, Incorporated (Minneapolis, MN): As the world’s largest producer, Cargill leverages scale across mining and evaporation assets to serve road and airport channels. Recent capacity expansion announcements (e.g., Belle Plaine) underscore a volume play to crowd out higher‑cost competitors — a signal that price‑competitive supply will be a central strategy in North America in 2026.
- Morton Salt, Inc. (Chicago, IL): Morton’s integrated underground mines and focus on packaged and bulk highway supply point to a dual strategy of operational reliability and customer segmentation. Morton’s footprint makes it a barometer for packaged supply economics and commercial channel renewals.
- K+S Aktiengesellschaft (Germany): The firm’s European mining focus and renewed environmental certifications (updated ISO 14001) position it well for regulated markets where sustainability credentials influence tender outcomes. Expect continued investment in treated anti‑caking and low‑environmental‑impact product lines.
- Compass Minerals (Overland Park, KS): Compass’s product innovation (e.g., recent launch of a corrosion‑inhibited treated salt) shows the commercial upside of premium formulations. Their strategy highlights that product differentiation — not just low unit cost — can win share among infrastructure‑sensitive customers.
- CNSIC (Beijing): The state‑owned scale in solar‑evaporated salt gives CNSIC a competitive cost baseline for domestic markets and export corridors across Asia. Trade flows from large coastal evaporation facilities mean that global buyers must factor in Chinese capacity in sourcing scenarios.
- Ineos, Cheetham Salt, Sudsalz: These regional producers demonstrate the persistence of local champions in markets where logistics costs, licensing, and long‑standing relationships with highway agencies create durable moats. Their roles will remain prominent in anchor supply contracts and seasonal surge capability.
Operational playbook: six actions PW Consulting recommends for 2026
- Re‑baseline procurement contracts: Move from fixed‑price multi‑year contracts to hybrid arrangements that include indexed energy/packaging cost pass‑throughs and volume flex provisions tied to winter severity models.
- Prioritize product segmentation: In tender renewals, separate specifications by environmental sensitivity and infrastructure corrosion risk to allow procurement to choose performance tiers rather than a one‑size‑fits‑all standard.
- Invest selectively in treated blends: Given regulatory and buyer preference trends, allocate R&D or JV budgets to corrosion‑inhibited and low‑chloride blends where price elasticity is highest.
- Stress‑test supply chains: Conduct scenario analyses for energy price shocks, container tariff persistence, and mine downtime to inform inventory buffers and alternative sourcing corridors.
- Target M&A for capability, not just capacity: Look for targets that add treated product formulations, beachhead positions in regulated geographies, or logistical hubs that shorten lead times to high‑value customers.
- Embed sustainability into tender wins: Use environmental certifications, life‑cycle chloride discharge assessments, and transparent emissions reporting as differentiators in competitive bids.
Report deliverables — what’s in the full publication (high level)
The full PW Consulting Worldwide Deicing Salt Market report combines proprietary demand modelling, supply‑side capacity mapping, scenario analyses, and a decision‑oriented playbook. Highlights include:
- Topline and scenario forecasts (historical 2020–2025; base year 2025; forecast 2026–2032) with sensitivity testing for energy, packaging tariffs, and regulatory adoption curves.
- Supply‑chain risk heat maps and utilization scenarios for mines and evaporation facilities under alternative winter‑severity and gas‑price paths.
- Commercial strategy modules for product segmentation, pricing levers, and tender structuring — including sample contractual language and hedging templates.
- Competitive intelligence dossiers on global and regional players with deal‑rationale matrices for M&A and partnership pursuit.
- Regulatory impact assessment and environmental compliance roadmaps tailored to major jurisdictions.
To preserve the investigative value of our proprietary models, the report intentionally refrains from publishing live segment tables in summary releases. We provide headline market sizing, concentration metrics, and broad directional indicators here, but detailed regional, type, and application splits are available only in the full report and interactive databook.
Methodology and data integrity
PW Consulting’s forecast combines bottom‑up capacity and throughput modelling with demand drivers derived from transport activity, municipal procurement cycles, and industrial consumption trends. Historical reconciliation with publicly filed sales, mine output, and trade statistics anchors the model for 2020–2025, while forward scenarios incorporate observable inputs: energy price pathways, recent corporate capacity announcements, product innovation timelines, environmental regulation trajectories, and logistics cost shocks.
We corroborate our supply‑side assumptions with on‑the‑ground intelligence — including the 2024 expansions and product launches by market participants — and validate demand elasticities through municipality and maintenance contractor interviews across representative climates. The report flags data confidence levels by node so decision‑makers can weight model outputs appropriately in strategic planning.
Final word: how PW Consulting helps you act in 2026
As the deicing salt market transitions from post‑pandemic normalization into a period shaped by regulatory pressure and selective product premiumization, 2026 will be a year for disciplined strategy. PW Consulting’s report equips leaders with the scenario tools, supplier playbooks, and acquisition filters required to protect margins, secure supply, and win tenders where performance and environmental stewardship matter.
For procurement directors, CEOs and investors preparing capital and commercial decisions in 2026, the full report offers the granular segmentation, contractual templates, and interactive databook necessary to execute with confidence. Access to the complete intelligence and our bespoke advisory services is available via the PW Consulting report portal.
For detailed analysis of this topic, please visit the official page: Worldwide Deicing Salt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com