

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Paper Dry Strength Resin Market to Reach USD 1,333.1 Million by 2032 with 3.82% CAGR; Asia‑Pacific Leads at USD 428.8M (2025)
By pmarketresearch, 2026-08-12
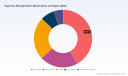
Worldwide Paper Dry Strength Resin Market — Strategic Imperatives for 2026
Executive summary
As the global paper industry navigates a post-pandemic demand realignment, decarbonization pressures and input-cost volatility, the dry strength resin market has quietly recalibrated. PW Consulting’s latest market study (base year 2025; historical window 2020–2025; forecast 2026–2032) finds a market that reached USD 1,025.4 Million in 2025 and is projected to grow to USD 1,333.1 Million by 2032 at a 3.82% CAGR across the forecast period. That headline growth masks short cyclical movements and structural shifts — information critical to capital allocation, procurement strategy and product development decisions in 2026.
Worldwide E-Notary Software Market
Why this report is strategically valuable for 2026 planners
-
Actionable clarity in a noisy environment: Paper makers and chemical suppliers face interlocking challenges — feedstock price swings (notably acrylamide monomer), increasing regulatory scrutiny and accelerating demand for bio-based or lower-impact chemistries. Our report separates transient noise from persistent trends so leaders can prioritize investments with asymmetric returns.
Coaxial Harness Market -
Bridges technical performance and commercial value: Dry strength additives are no longer sold as standalone chemistries — they are sold as levers to reduce basis weight, cut refining energy, improve runnability, or unlock recycled fiber blends. The analysis translates polymer performance into quantified operational outcomes that procurement and operations teams can act on in 2026.
Worldwide Fibre to X Market -
Scenario-ready planning for 2026 shocks: The study embeds scenario models that simulate raw-material shocks, tightening environmental regulation and shifts in tissue/packaging demand. These models are tuned to support contingency planning and near-term CAPEX decisions.
What the report delivers (practical toolkit for executives)
-
Commercially calibrated market model — a top‑down and bottom‑up framework that converts resin performance into dollar impacts on basis weight, energy consumption and unit cost, across legacy and emerging paper grades.
-
Scenario suite for 2026–2032 — three plausible industry paths (Base, Resource‑Shock, and Sustainability‑Fast), each populated with sensitivity outputs to guide supplier selection and inventory policy.
-
Supplier scorecards and procurement playbook — objective evaluation templates covering technical fit, supply continuity, sustainability credentials and total cost of ownership for evaluating incumbent and new entrants.
-
Technology roadmap and R&D prioritization matrix — ranks formulation strategies (synthetic vs. hybrid bio-synthetic blends, GPAM versus PAM, starch integration strategies) by near-term impact and commercialization risks.
-
Operational experiments and dosing optimizations — stepwise lab-to-line change management protocols that reduce implementation risk while accelerating benefits capture.
-
M&A and partnership playbook — target profiles and valuation sensitivities for acquisitions, joint ventures and licensing collaborations that accelerate sustainable product portfolios or fill geographic supply gaps.
Note: this press release intentionally highlights the report’s actionable structure while withholding granular regional and application split tables to preserve the commercial value of the full deliverable. The report’s datasets and proprietary segment-level inputs are available via PW Consulting’s report portal.
Competitive landscape — who matters and why
The market sits in a medium‑concentration space: aggregate measures indicate the leading three players hold a material share but do not control the market outright, and the top five expand that presence significantly. This structure encourages continued product innovation, regional specialists and margin competition from local producers.
-
Solenis — strong portfolio depth across amphoteric, anionic and cationic chemistries combined with application services. Recent sustainability recognition linked to Hercobond solutions reflects its ability to couple product performance with mill-level decarbonization messaging.
-
Kemira — positions itself on engineered polymer platforms and cellulose‑additive hybrids with commercial products that target tissue and molded-fiber lightweighting; the company’s November 2025 pump-and-go innovation exemplifies the market push for turnkey, mill-friendly solutions.
-
Buckman , SNF , and BASF — each brings a distinctive mix of chemistry depth, application knowledge and global supply reach. Their competitive advantage is less about single chemistry and more about bundled solutions that deliver measurable machine‑level gains.
-
Regional players and specialist innovators (from established Japanese, European and US firms to agile Chinese producers) continue to apply price pressure in commoditized segments while differentiating on service, custom formulations and local feedstock advantages.
Recent industry signals to factor into 2026 plans
-
New product commercialization cycles are accelerating. Example: a late‑2025 launch demonstrated how “pump‑and‑go” solutions can materially reduce mill implementation friction and produce immediate tensile/burst benefits.
-
Recognition programs and case studies linking resin selection to site-level CO2 and resource efficiency are increasingly important sales drivers — buyers are rewarding suppliers that demonstrate credible whole‑mill impact.
-
Feedstock volatility (acrylamide price oscillations) and the persistent role of cationic starch as a natural complement to synthetics are reshaping formulation economics. Buyers must balance short‑term raw material hedging with longer‑term product diversification towards lower‑impact chemistries.
Implications for 2026 decision-making — prioritized actions
-
1. Re-calibrate procurement from cost to value — move beyond price per kg to a total‑cost framework that quantifies basis weight savings, energy reduction and runnability benefits. Contracts should incorporate performance KPIs and gain‑sharing clauses that align supplier incentives with mill outcomes.
-
2. Hedge feedstock risk strategically — combine shorter-term purchase commitments with options or index‑linked contracts for critical monomers. Parallel investments in alternate chemistries will reduce exposure to single-feedstock shocks.
-
3. Launch controlled R&D pilots for bio‑hybrid formulations — prioritize quick-win grades (where laboratory parity is achievable) and measure full‑mill impacts to build a commercial case by year‑end 2026.
-
4. Invest in dosing analytics and application services — digital dosing platforms reduce polymer consumption while increasing consistency. The reported winners to date are those that package chemistry with field services and analytics.
-
5. Revisit product positioning around sustainability — credible lifecycle claims and peer-reviewed mill case studies unlock premium positioning; align product roadmaps with verifiable environmental metrics.
-
6. Prioritize M&A/JV targets that close capability gaps — look for small to mid-sized players with specialized formulations, regional market access, or pilot‑scale biopolymer platforms rather than broad scale commodity producers.
-
7. Strengthen cross-functional change management — trials fail most often because lab wins are not translated to machine changes. Create a rapid decision loop between R&D, production and procurement to institutionalize positive results.
-
8. Monitor regulatory trajectories and prepare compliance pathways — anticipate tightening restrictions that favor reduced residual monomer and improved biodegradability; build regulatory scenarios into product development timelines.
How to use this report in a 90‑day planning cycle
For C-level and functional leads preparing 2026 plans, the report acts as both a diagnostic and an implementation kit. In the first 30 days, use the supplier scorecards and market scenarios to re-frame supplier conversations and identify two near-term pilots. By day 60, deploy dosing analytics pilots and finalize feedstock hedge options. By day 90, convert pilot results into contract amendments, CAPEX prioritization and an integrated R&D roadmap. Each stage is supported by templates and playbooks within the full report.
Where the report intentionally draws a line
PW Consulting’s public summary emphasizes strategic findings and operational recommendations while withholding the granular regional, type and application split tables that underpin our commercial models. These segment‑level datasets, scenario spreadsheets and proprietary supplier scoring matrices are included in the paid report package and are essential for transaction-level decisions, competitive intelligence and contract negotiations.
Conclusion — a narrow window to gain durable advantage in 2026
Dry strength resins sit at an inflection point: modest aggregate growth masks a re-rating of value drivers — sustainability credentials, whole‑mill performance and supply resilience. For executives planning 2026 actions, the choices made now about supplier partnerships, formulation strategy and operational analytics will determine whether companies capture the available efficiency and product‑mix gains or merely defend margins. PW Consulting’s Worldwide Paper Dry Strength Resin Market report is designed to make those choices clearer and executable. To access the full datasets, segment breakdowns and the proprietary decision tools, please consult the PW Consulting report portal and the full research package.
For detailed analysis of this topic, please visit the official page: Worldwide Paper Dry Strength Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Worldwide Electricity Trading Platform Market to Grow at a 13.12% CAGR Through 2032
By pmarketresearch, 2026-08-12
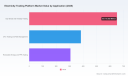
PW Consulting Release: Worldwide Electricity Trading Platform Market — Strategic Brief for 2026 Decision‑Makers
PW Consulting today publishes an executive briefing tied to our in‑depth market research, Worldwide Electricity Trading Platform Market (Base Year: 2025). The market has evolved rapidly — expanding from USD 730.45 million in 2020 to USD 1,342.22 million in 2025 — and our model projects continued acceleration through the 2026–2032 forecast window, reaching approximately USD 3,181.25 million by 2032 at a compound annual growth rate (CAGR) of 13.12% across the forecast period. For corporate strategy teams preparing budgets, procurement cycles, and regulatory engagement plans in 2026, this study delivers an operationally practical roadmap built on quantitative scenarios and vendor benchmarking.
Worldwide Military Avionics Market
What this report delivers — practical, decision‑ready content
-
Executive playbook for board and C‑suite: concise decision triggers, capital vs. operating cost tradeoffs, and go/no‑go criteria tailored to platform adoption and in‑market participation.
Worldwide Dual-side Aligners Market -
Vendor selection framework and RFP toolkit: scorecards, integration checklists (data, latency, clearing/settlement interfaces), and TCO models that show the upgrade path from legacy on‑premise systems to modern SaaS architectures.
5G RHUB Market -
Operational blueprints: step‑by‑step migration plans, API and standards map, latency and data quality thresholds by use‑case (day‑ahead, intraday, OTC, PPA and peer‑to‑peer), and real‑world implementation timelines from pilot to production.
-
Regulatory scenario stress‑tests: bespoke modeling of market‑design changes (shortening gate times, new margining rules, capacity allocation reforms) and their quantified impact on trading P&L, collateral needs and counterparty exposure.
-
Competitive intelligence and partnership strategy: publicly verifiable dossiers on major exchanges, platform vendors and emerging decentralised solutions, accompanied by acquisition and alliance heatmaps to guide strategic conversations.
-
Use cases and commercial models: standardized templates for PPAs, data‑center power procurement, and local peer‑to‑peer trading pilots, complete with contract design checklists and sample term sheets.
Market trajectory and strategic implications for 2026
The electricity trading platform market is maturing from fragmented pilots to commercially scaled deployments. Several structural drivers are underpinning the projected 13.12% CAGR: pervasive renewable integration increasing short‑term volatility, the rise of corporate PPAs and data‑center demand concentrated in specific grid pockets, and accelerating cloud adoption reshaping total cost of ownership. These macro forces are observed alongside rapid market‑rule changes — notably the European shift toward 15‑minute market time units in day‑ahead trading and attendant reforms in imbalance pricing — which change the technology and latency requirements for successful market participants.
Regulatory and reliability initiatives are also shifting commercial calculus. Recent actions in U.S. regional markets — from new transmission assignment approaches for co‑located generation to frameworks integrating large loads into capacity planning — mean that corporate buyers of power and platform vendors alike must embed regulatory scenario analysis into procurement decisions. Our report quantifies these effects and provides playbooks that enable executives to model collateral, margining and capacity‑auction exposure under multiple plausible regulatory pathways.
Competitive landscape — who matters and why
The market demonstrates meaningful concentration at the top: the leading three companies collectively command a material share, and the top five broaden that control further. That concentration influences go‑to‑market dynamics, partnership leverage and platform interoperability expectations.
-
Exchange operators and established venues — firms operating large spot and derivatives markets are doubling down on scale, clearing integration and new margining regimes. These incumbents remain fundamental partners for firms seeking deep liquidity and standardized contracts.
-
Proprietary platform and ETRM vendors — advanced trading system suppliers continue to compete on latency, algorithmic trade capabilities and integrated risk management. For firms managing complex portfolios, the ability to overlay risk analytics and straight‑through processing differentiates winners.
-
Decentralized and peer‑to‑peer innovators — blockchain‑enabled platforms and local flexibility marketplaces are gaining traction in municipal and behind‑the‑meter use‑cases. They present asymmetric opportunities for utilities and community energy projects looking to monetize distributed resources.
-
Regional specialists — local platforms focused on data center procurement or specific market designs are capitalizing on fast‑moving customer needs and regulatory openings. These players are attractive partners or targets in cross‑border expansion strategies.
Our dossier analyzes the strategic positioning and practical capabilities of key market actors across these categories, highlighting recent developments and near‑term strategic priorities. For example, certain European exchange operators reported double‑digit trading volume growth in power derivatives and are publicly signalling investment in upgraded margining systems to align with evolving clearing requirements — a clear signal that market structure and collateral dynamics will be front‑and‑center for trading participants in 2026. Similarly, regional platform providers that are executing targeted data‑center procurement strategies are emerging as critical intermediaries in specific markets.
Operational playbook for procurement, integration and risk management in 2026
-
Start with scenarios, not suppliers: build three market scenarios (baseline, stress, structural change) and run vendor RFP responses through scenario stress‑tests that include regulatory reforms and abrupt price shocks.
-
Prioritize modularity: prefer platforms that support hybrid deployments (cloud native with on‑prem gateways) to protect legacy integrations while enabling phased migration to SaaS operating models.
-
Tie vendor KPIs to market microstructure: set measurable SLAs for latency, reconciliation time, and failover that reflect the operational cadence of day‑ahead and intraday markets under faster settlement regimes.
-
Embed regulatory engagement as a supplier selection criterion: vendors that can support compliance workflows, audit trails and scenario reporting reduce operational friction when markets change rulebooks.
-
Design collateral and liquidity buffers into capital plans: anticipate higher margining requirements as clearing models and auction designs evolve; our TCO models show how different margining regimes shift the NPV of platform choices.
-
Plan partnerships around liquidity and data: alliances with established exchanges or liquidity aggregators can be faster and lower‑risk routes to access depth while your internal capability scales.
Why PW Consulting’s analysis matters for 2026 decisions
Companies entering procurement cycles this year face a compressed decision window. Budget cycles, vendor roadmaps and regulatory implementation timelines (including new capacity frameworks and shorter market time units) converge in 2026. The combination of rising wholesale costs in certain hot spots, evolving capacity assignment practices, and new auction mechanisms means that platform choice is not merely an IT decision — it is a strategic hedging and sourcing decision with multi‑year balance‑sheet implications.
Our report is purpose‑built for this inflection point. It combines market sizing and growth trajectories with hands‑on templates and quantified scenario outputs so decision‑makers can fast‑track procurement without exposing their organizations to avoidable regulatory or market‑design risks. The study also identifies partnership archetypes and integration patterns that have delivered the fastest path from pilot to commercial scale in recent implementations.
How to use the report and next steps
-
Download the executive brief to align the board and finance teams on the market trajectory and capital budgeting implications for 2026–2027.
-
Purchase the full report to access granular regional and application splits, our vendor benchmarking matrix, downloadable TCO models and RFP templates — the sections that enable procurement teams to run a rigorous selection process.
-
Engage PW Consulting for a tailored workshop: we map the report’s scenarios to your portfolio and run an implementation readiness assessment focused on integration risks and regulatory exposure.
PW Consulting’s Worldwide Electricity Trading Platform Market research bridges strategic foresight and operational specificity. For executives and practitioners planning platform investments or market participation in 2026, the analysis provides the tools to move from hypothesis to contract with confidence. To view the full scope, methodology and to procure the full dataset and proprietary models, visit our report page and request the detailed annexes and vendor scorecards.
For detailed analysis of this topic, please visit the official page: Worldwide Electricity Trading Platform Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Isopropyl Biphenyl Heat Transfer Fluid Market to Reach USD 346.61 Million by 2032, Growing at a 5.48% CAGR
By pmarketresearch, 2026-08-12
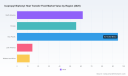
Isopropyl Biphenyl Heat Transfer Fluid Market — Strategic Outlook for 2026: PW Consulting Executive Brief
PW Consulting’s latest market study on the Isopropyl Biphenyl (IPB) heat transfer fluid market delivers a disciplined, decision-oriented view that executives and investment committees will use to shape strategy in 2026. The report synthesizes a seven-year historical track (2020–2025) and provides a forward-looking forecast through 2032. At the macro level the market is approaching a quarter‑billion USD in 2025 and is projected to expand at a mid‑single-digit compound annual growth rate (CAGR) into the next planning horizon—driving materially higher absolute demand by 2032. This briefing highlights the report’s strategic value while reserving the granular segmentation results for the full release.
Electrosynthesis Service Market
Why this report matters for 2026 corporate decisions
-
Actionable growth planning: With a clear trajectory established through 2025 and modeled scenarios for 2026–2032, boardrooms gain a defensible basis for CAPEX timing, product roadmaps, and channel expansion decisions. The forecast path allows procurement and commercial teams to align supplier contracts with anticipated volumetric shifts and price pressure points.
Derivative Porous Carbon Material Market -
Concentration-aware sourcing: The market exhibits meaningful supplier concentration among a small set of incumbent producers. Our analysis quantifies this dynamic and translates it into practical sourcing playbooks—covering dual‑sourcing thresholds, inventory hedging levels, and cost buffers suitable for 2026 operational plans.
Recipe Manager APP Market -
Regulatory & legacy substitution risk: IPB-based fluids have an established role as PCB replacements and dielectric alternatives. The report unpacks the regulatory history and projects potential compliance vectors that could affect product specification and liability exposure in the next 12–36 months—crucial input for legal, procurement, and product teams.
-
Project-level economics for industrial applications: For capital-intensive deployments (e.g., concentrated solar power and chemical process heating), we provide a comparative economics model that ties fluid selection to system efficiency, heat transfer performance limits, and operating temperature envelopes—tools that engineering and finance teams can plug directly into project business cases.
Data highlights that inform strategic trade-offs
PW Consulting’s base-year view (2025) anchors our models and supports a set of forecast scenarios. The central forecast applies an industry-validated CAGR that translates into a substantial market expansion through 2032. This growth is not uniform: it is driven by temperature‑intensive industrial processes, investments in waste heat recovery, and selected electronics cooling niches where IPB chemistry matches required thermal stability and dielectric properties. The report converts that macro growth into practical KPIs—revenues, implied capacity utilization, and stress-tested supplier availability—so decision-makers can compare strategic alternatives on a common economic basis.
Competitor landscape: Strategic takeaways
-
Eastman Chemical Company (Kingsport, TN, USA) — With globally available, high‑purity IPB mixtures designed for low‑pressure liquid-phase systems and bulk temperatures up to the upper 300°C range, Eastman operates from a commercial leadership posture. The report evaluates Eastman’s product positioning, global distribution strength, and implications for customers seeking branded, validated fluid platforms.
-
Nippon Chemical Texas Inc. (NCTI) (Texas, USA) — NCTI’s SS‑300 line targets high‑temperature and sub‑zero industrial use cases with robust thermal stability. We analyze how their isomer mix and regional manufacturing footprint affect competitive advantage in thermally demanding applications and in cold‑start operational regimes.
-
Dalian Richfortune Chemicals Co., Ltd. (Dalian, China) — As a supplier of Therminol‑62 equivalents, Richfortune’s experience in concentrated solar power projects and long‑term industry supply relationships gives them strategic relevance for utility‑scale customers. Our supplier scorecard assesses performance consistency, project delivery risk, and scale-up potential.
-
Jiangsu Zhongneng Chemical Technology Co., Ltd. (Lianyungang, China) — With product ranges covering broad temperature windows, Zhongneng is profiled for its technical breadth and regional industrial ties; the report discusses implications for OEM partnerships and regional specification influence.
-
Manto Chemistry (Jiangsu, China) — Producing a Therminol‑62 equivalent and operating a dedicated isopropylbiphenyl production capacity, Manto stands out on supply integration. The report examines how dedicated upstream capacity affects resilience, pricing power, and strategic options for vertical integration or tolling partnerships.
-
Rütgers GmbH (Germany) — Rütgers’ Ruetasolv BP series addresses high‑temperature industrial use cases. We profile Rütgers for specialty application performance, regional strength in European OEM ecosystems, and potential fit for clients prioritizing advanced performance envelopes.
Report contents: What you can apply immediately
The full PW Consulting report is structured to be directly operational. Core components include:
-
Proprietary market-sizing and trend models that reconcile historical shipments and revenue data with forward demand scenarios through 2032.
-
Supplier concentration and competitive positioning analysis with a five‑factor scorecard—used to derive risk-adjusted supply availability metrics for procurement planning.
-
End‑use economic modules that convert fluid selection into LCOH (levelized cost of heat) and process performance differentials for typical high-temperature systems.
-
Regulatory and compliance playbook: mapping historical PCB phase‑outs to current dielectric acceptance standards and outlining certification pathways for new fluid introductions.
-
Negotiation templates and contract language checklists tailored for 2026 sourcing cycles (e.g., clause libraries for volume flexibility, quality acceptance testing, and force majeure scenarios in complex international supply chains).
-
Scenario planning workshops and slide‑ready outputs for executive decision forums, including sensitivity analyses that stress supplier outages, raw material cost inflation, and accelerated adoption curves in selected end markets.
Strategic recommendations for 2026
-
Prioritize supply resilience through a two‑tier strategy: secure a primary supplier relationship with contractual protections and develop a validated secondary source. The report provides a decision tree to quantify the trade‑off between higher unit costs and business‑continuity exposure.
-
Invest in qualification testing early. For customers specifying fluids for new projects, completing qualification and compatibility testing in Q1–Q2 of 2026 avoids procurement bottlenecks later in the year when demand accelerates.
-
Embed regulatory scenario clauses in new product development and market entry plans. While IPB-based fluids currently address legacy PCB substitution needs, evolving environmental and safety expectations require traceable certifications embedded into product documentation.
-
Target partnerships in waste heat recovery and process modernization projects where fluid performance delivers quantified efficiency gains. The report provides templates to calculate incremental ROI by system class and operating temperature profile.
-
Consider selective M&A or JV activity to secure upstream feedstock or specialty blending capabilities where suppliers show concentration. The competitive analysis highlights where such consolidation would materially alter supplier bargaining power.
Methodology, data confidence, and what’s intentionally withheld
Our methodology triangulates public filings, vendor product literature, primary interviews with industry participants, and PW Consulting’s proprietary shipment and pricing models. We disclose broad market sizing and growth rates to support strategic planning, while granular segment allocations and company‑specific revenue shares are presented exclusively in the full report. This “preview” treatment is deliberate: executives receive the contextual insights needed to identify priority decisions, and the full dataset is reserved for subscribers and clients who require the operational numbers for procurement and investment execution.
Frequently asked practical questions (FAQ)
-
Q: Are IPB fluids still the accepted replacement for legacy PCBs? A: Yes—historical regulatory phase‑outs of PCBs led to wider adoption of IPB mixtures for heat transfer and dielectric applications. The report outlines how product specifications evolved post‑phase‑out and what certification pathways remain relevant today.
-
Q: Does upstream capacity matter? A: Absolutely. Dedicated production capacity for key IPB feedstocks materially affects supply flexibility and turnaround times. Our supplier profiles examine the impact of dedicated capacity on both price volatility and contract risk.
-
Q: Where should I look first if I’m building a heat transfer fluid sourcing strategy in 2026? A: Start with a supplier risk assessment based on concentration metrics and then overlay project‑level thermal requirements. The PW Consulting report supplies both a diagnostic checklist and a prioritized action plan for the first 90 days.
Conclusion and next steps
For 2026 planning cycles, PW Consulting’s Isopropyl Biphenyl Heat Transfer Fluid Market report furnishes the disciplined forecasting and supplier intelligence executives need to make confident operational and investment choices. The market’s trajectory—anchored by the 2025 base and a validated multi‑year CAGR—creates clear windows of opportunity for firms that act early on supply resilience, qualification velocity, and targeted partnerships in temperature‑sensitive applications.
To access the complete dataset, segmented forecasts, and vendor‑by‑vendor financial overlays that underpin these recommendations, please consult the full PW Consulting report or contact our industry practice for a tailored executive briefing.
For detailed analysis of this topic, please visit the official page: Isopropyl Biphenyl Heat Transfer Fluid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Digital Movie Projector Market Valued at USD 4,412.5 Million in 2025, Poised for 7.21% CAGR Through 2032
By pmarketresearch, 2026-08-12
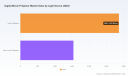
Worldwide Digital Movie Projector Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Digital Movie Projector Market positions enterprise leaders to make confident strategic choices in 2026. Built on a verified historical series (2020–2025) and a rigorous forecast (2026–2032), the report shows the market expanding from USD 4,412.5 Million in 2025 to an anticipated USD 7,183.43 Million by 2032, representing a compound annual growth rate (CAGR) of 7.21% over the forecast window. That trajectory, combined with high market concentration among a handful of tier‑one suppliers, creates a decision environment where timing, supplier strategy, and technology selection materially affect both cost and competitive positioning.
Cone-Beam Computed Tomography (CBCT) Equipment for Oral Maxillofacial Market
Market trajectory and macro dynamics
The projector market’s growth is being driven by a convergence of content demand, infrastructure investments (including large-scale cultural and entertainment projects), and rapid innovation in illumination and imaging subsystems. Laser illumination—now the dominant shipment generator among major original equipment manufacturers—has moved from niche to mainstream, materially reshaping product lifecycles, service models, and total cost of ownership calculations. Our cross-validated shipment and revenue models indicate that laser solutions accounted for a clear majority of 2025 volumes among primary vendors, and that trend continues into 2026.
Worldwide Multi Axis Controllers Market
At the same time, structural characteristics matter. Market concentration is high: the top three manufacturers control a very large share of revenue, and the top five capture an even larger share—creating an oligopolistic market dynamic that benefits incumbents but raises strategic issues for buyers and new entrants alike. Supply-side constraints—most notably the concentrated supply of high-performance laser diodes and rare earth inputs—introduce a non-trivial risk premium into procurement and capex planning. Licensing realities around key imaging technologies further reduce the field of substitute suppliers for certain high-brightness, DLP‑based cinema solutions.
Bifurcated Covered Stent Market
Why this matters for 2026 decision-makers
- CapEx planning: With stronger growth and upward price pressure on key components, late-2026 purchases may face higher acquisition and service costs than comparable 2025 deals. The value of staged procurement and vendor financing has increased.
- Technology choices: Laser vs. lamp, DLP vs. alternative imaging stacks, and 4K/120hz‑capable architectures each carry different upgrade paths and service cost profiles. Early adopters capture content and premium pricing advantages, while conservative buyers reduce technical obsolescence exposure.
- Supplier negotiation: High concentration allows leading OEMs to set terms; however, bundled services, multi-year maintenance contracts, and volume commitments remain effective levers for cost mitigation.
- Supply chain resilience: Rare earth and diode supply concentration means procurement teams should incorporate second‑source strategies, buffer inventories, and indexed pricing clauses into contracts.
- M&A & partnerships: Niche optics, laser diode assemblers, and software/automation players represent high-leverage targets for fast-tracking capabilities and protecting margins.
Competitive landscape — who matters and why
The market’s competitive core is populated by a few established players whose product roadmaps, manufacturing scale, and technology licenses shape industry direction. PW Consulting’s competitive assessment synthesizes public disclosures, primary interviews, and product teardowns to map relative strengths and strategic intent for each major vendor.
- Barco NV (Belgium) — A leader in laser-based cinema projectors, Barco’s next‑generation families focus on high‑brightness RGB laser systems, simplified serviceability, and performance consistency for commercial theaters. Barco’s investments in unified platforms reduce SKU complexity and accelerate rollout for large exhibitor chains.
- Christie Digital Systems (U.S., Ushio subsidiary) — Christie maintains a broad cinema portfolio with strong R&D in illumination (Phazer) and a track record of high-performance HDR/ Dolby Vision integrations. Recent mid‑2020s product introductions and expansions broaden their addressable screens, especially for small to mid‑size venues.
- NEC Display Solutions (Sharp NEC, Japan) — NEC’s DLP‑based strategy emphasizes reliability and long service life, particularly for theatre chains prioritizing uptime. Their laser models are engineered for low total operating cost and standardized maintenance workflows.
- Sony Corporation (Japan) — While Sony has shifted its focus across segments, its imaging technology heritage—especially in high‑end projection—keeps it relevant in premium and niche segments where proprietary display tech and color science matter.
Recent product and component developments materially change competitive calculus. In 2025–26, Christie refreshed product lines with Phazer‑illuminated CineLife+ variants and compact 1DLP Jazz series models; Texas Instruments unveiled next‑generation DMD chipsets at CES 2026 that enable higher brightness, better native contrast and 4K/120 fps capabilities; and major vendors expanded RGB and RGBH offerings to capture a wider portion of screen types and exhibitor footprints. Together, these moves compress feature differentiation while increasing technical barriers for late entrants.
What PW Consulting’s report delivers — practical, transaction‑oriented intelligence
This study is designed as a decision toolset, not just a descriptive market portrait. For boardrooms, procurement teams, and product leaders we include:
- Validated historical demand and revenue series (2020–2025) and a probabilistic forecast (2026–2032) with scenarios keyed to supply shocks and premium content cycles.
- Portfolio strategy playbooks: decision trees for purchase vs. lease, upgrade cadence models, and vendor selection matrices based on TCO, uptime, and service network depth.
- Procurement toolkits: supplier scorecards, negotiation scripts, indexed contract templates tied to raw material clauses, and suggested warranty/service bundling strategies.
- Supply risk dashboards: heatmaps of component concentration, supplier single‑point failures, and contingency plans for diode and rare earth disruptions.
- Technology adoption frameworks: capability maps aligning illumination and imaging choices to exhibitor needs (from boutique cinemas to megaplex chains), including upgrade prioritization and obsolescence timelines.
- M&A and partnership screens: prioritised targets, valuation anchors, and integration playbooks for buyers seeking vertical or capability consolidation.
- Executive-ready outputs: a concise strategic memo, investor briefing slides, and an interactive model (Excel + dashboard) so leadership can dynamically stress-test key assumptions.
Methodology and confidence levels
The report integrates multi-source inputs: audited vendor financials, OEM product specifications and teardowns, primary interviews with exhibitors and integrators, component supplier checks, and macroeconomic overlays. Forecasts use scenario-based Monte Carlo simulations to quantify downside (supply shock) and upside (accelerated global content rollouts) outcomes. Where single‑source commercial data exist—such as licensed DLP distributions—we explicitly flag those constraints and model alternatives. Overall, our confidence bands tighten at the market level (total revenue and CAGR) and widen at ultra‑granular segment slices, which is why the report delivers both high-certainty macro guidance and carefully validated segment scenarios for paid subscribers.
Immediate recommendations — what to do in 2026
- Accelerate procurement talks that include indexed price protections and multisupplier commitments to guard against diode and rare‑earth volatility.
- Prioritize pilot deployments of next‑generation 4K/120 workflows in flagship venues to capture premium viewers and set content‑delivery expectations.
- Negotiate multi-year service agreements with performance SLAs to offset the risk of new tech adoption and protect uptime during content premieres.
- For investors and M&A teams: focus on optics and diode assembly assets that can provide margin-insulating integration value to platform OEMs.
- In procurement and operations: deploy the report’s supply risk heatmaps and TCO templates before Q3 2026 capital approvals.
Next steps and how to obtain the full study
This release is a strategic preview intended to demonstrate the report’s depth and immediate applicability while directing decision‑makers to the full dataset, supplier-level scorecards, and forecast models. PW Consulting’s full Worldwide Digital Movie Projector Market report contains the primary datasets, supplier profiles, and executable toolkits referenced here—essential inputs for any organization planning capex, procurement, or partnership activity in 2026.
To access the complete study, interactive models, and bespoke advisory engagements, visit PW Consulting’s research portal or contact our industrial technology practice for a briefing. Our team will tailor the deliverables—scenarios, supplier scorecards, and negotiation playbooks—to your specific risk tolerance and business model.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Movie Projector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Industrial Diaphragm Pump Market Valued at USD 6,860.7 Million in 2025, Poised to Reach USD 9,750.6 Million by 2032 at a 5.15% CAGR
By pmarketresearch, 2026-08-12
Worldwide Industrial Diaphragm Pump Market — Strategic Brief for 2026 Decision-Makers
PW Consulting’s new market study, "Worldwide Industrial Diaphragm Pump Market (Base Year 2025) — Strategic Outlook 2026–2032," provides a focused, actionable intelligence package designed to inform capital allocation, product strategy, and supply-chain decisions for the coming planning cycle. The global market for industrial diaphragm pumps reached approximately USD 6.86 billion in 2025 and is modeled to expand at a compound annual growth rate of 5.15% through our 2026–2032 forecast horizon, reaching about USD 9.75 billion by 2032. This brief highlights the strategic value of the report for 2026 while preserving the granular segment-level detail reserved for subscribers and advisory clients.
Synchronous Demodulator Market
Why this report matters in 2026
2026 is shaping up as an inflection year for diaphragm-pump stakeholders. Three converging forces are reshaping demand and competitive dynamics:
Full HD Endoscopy Video Processor Market
- Regulatory and sustainability pressure: Tighter effluent and wastewater discharge standards and fugitive-emission limits are increasing adoption of sealless, PTFE-lined and ATEX-compliant solutions for hazardous environments. These compliance drivers are forcing faster product development and replacement cycles across industrial end-users.
- Electrification and efficiency opportunities: New electric diaphragm platforms and advancements in variable-drive integration are delivering dramatic energy and lifecycle benefits. Case references in the market indicate up to 80% energy reduction in some modern electric diaphragm systems versus older pneumatic models, creating a compelling TCO narrative for industrial buyers.
- Input-cost volatility and supply-chain concentration: Raw-material pressures — from stainless steel and high-grade elastomers to PTFE — are increasing unit-cost risk and shortening suppliers’ pricing visibility. For context, PTFE supply supporting chemical-resistant diaphragms is sized in the low hundreds of kilotons globally in 2026, underscoring its industrial-scale importance to pump manufacturers and OEMs.
What PW Consulting’s report delivers — practical, decision-ready content
Our study is structured to support C-suite and business-unit action plans. The report includes:
Worldwide Portable Storage Containers Market
- Top-down market sizing and a 2026–2032 forecast built from multiple demand-side and supply-side models, reconciled to historical performance (2020–2025).
- Driver-and-restraint mapping that quantifies the impact of regulatory shifts, energy mandates, and raw-material dynamics on procurement cycles and replacement demand.
- Go-to-market and pricing playbooks for OEMs and distributors — including channel segmentation, aftermarket-service monetization strategies, and recommended margin-management tactics under input-cost stress.
- Technology deep dives covering air-operated vs. electrically-operated architectures, sealless designs, PTFE and elastomer material choices, and embedded-sensor/digitalization pathways for predictive maintenance.
- Vendor assessment framework with capability matrices, technology roadmaps, and M&A/partnership scanning to identify bolt-on and transformational targets.
- Customizable dashboards and downloadable datasets for client-led scenario planning (models available in spreadsheet and API-ready formats for enterprise integration).
To preserve commercial value for strategic users, the public summary intentionally omits detailed segment revenue breakdowns and regional share tables; these are available in the full report and through PW Consulting advisory engagements.
Competitive landscape — patterns that matter
The diaphragm-pump sector remains moderately concentrated: the three largest groups collectively account for roughly one-third of market sales, while the top five approach the mid-forties in concentration. This structure creates distinct strategic opportunities for both established incumbents and agile challengers.
- Product-platform leaders: Established industrial pump groups that integrate diaphragm technologies within broader fluid-motion portfolios continue to leverage brand, distribution, and aftermarket footprints. These players benefit from multi-industry exposure (water, chemical processing, oil & gas) and can move quickly to bundle services and retrofit offerings.
- Specialists and high-performance innovators: Companies focused on high-pressure, metering, or sealless solutions are competing on material science and precision dosing. Recent product activity shows acceleration in sensor-integrated designs and precision electric diaphragm pumps aimed at industrial, laboratory, and analytic applications.
- Regional manufacturing and cost-advantage players: Manufacturers with flexible material sourcing and local production capacity in high-growth industrial markets are positioning to capture volume-based demand and shorter lead-time contracts.
- Service and digitalization battlegrounds: Embedded sensors, condition-based maintenance, and cloud analytics are fast becoming differentiators. The first movers in digital aftermarket services are creating recurring revenue channels that materially increase installed-base value.
Representative players profiled in our research include multinational incumbents and specialist manufacturers that signal the competitive breadth of the sector — from generalist industrial groups to niche metering and dosing experts. Recent product launches and exhibitor activity are reinforcing four tactical themes: electrification, sensor integration, larger flow-capacity plastic designs for chemical transfer, and electric diaphragm systems targeted at environmental applications.
Recent market signals and product activity
- March 2026: A leading diaphragm manufacturer introduced a family of pumps with integrated flow, pressure and vacuum sensing, signaling a rapid shift to intelligent dosing and remote diagnostics for industrial and medical markets.
- March 2026: High-flow plastic AODD models were launched targeting chemical transfer and environmental service providers — a direct response to demand for corrosion-resistant, lower-cost fluid-handling for bulk transfer.
- 2025–2026: Several vendors announced or demonstrated new electric diaphragm platforms and pressure-relief controllers at major trade shows, reflecting the market’s pivot toward energy-efficient and electronically controlled solutions.
These developments are representative, not exhaustive; the full report documents product roadmaps, patent trends, and comparative technology scorecards.
Strategic imperatives for 2026 planning cycles
For executives building 12–36 month plans, PW Consulting recommends a prioritized set of actions that balance near-term risk mitigation with medium-term growth capture:
- Prioritize electrification R&D and beta deployments: Fast-track electric diaphragm prototypes and retrofit kits for legacy pneumatic fleets to capture early-adopter industrial customers focused on TCO and sustainability.
- Secure critical raw-material exposure: Implement multi-year hedging, qualify alternative elastomers/PTFE suppliers, and consider selective vertical integration or long-term supply agreements to stabilize ASPs and margin forecasts.
- Monetize installed base through services: Build remote-monitoring offerings and predictive-maintenance contracts; these provide higher-margin, recurring revenue and strengthen customer stickiness.
- Design for compliance: Invest in ATEX, fugitive-emission certifications, and sealless PTFE-path offerings to meet accelerating regulatory requirements in wastewater and hazardous-chemicals handling sectors.
- Channel and aftermarket optimization: Rebalance distributor incentives and inventory models to shorten lead times in growth markets while protecting premium pricing for specialized, compliant products.
- M&A and alliance scouting: Identify bolt-on targets that add digital capabilities, regional manufacturing scale, or specialized material expertise rather than chasing commoditized volume alone.
- Scenario-based pricing and margin playbooks: Embed raw-material and energy-price scenarios into commercial bids and capital-project cost estimates to avoid margin compression during procurement cycles.
How PW Consulting can accelerate your 2026 choices
This study is designed to be execution-oriented: it provides the market context, vendor benchmarking, and implementation playbooks needed to operationalize strategic choices within procurement, product development, and M&A teams. For organizations that require tailored support, PW Consulting offers scenario modeling workshops, supplier negotiation support, and acquisition target screening based on the proprietary datasets underpinning the forecast.
Note on data access: This brief highlights headline market sizing and strategic insights while withholding detailed regional and segment-level breakdowns. The full report contains the granular segmentation, regional projections, product-level ASP trends, and company-level comparable metrics that procurement, strategy, and corporate development teams will require to finalize 2026 budgets and roadmaps.
Next steps
- Download the executive report summary and request the complete dataset to run your own scenarios.
- Engage PW Consulting for a tailored workshop to translate these insights into a 12–24 month implementation roadmap aligned with your supply-chain and R&D milestones.
PW Consulting’s Worldwide Industrial Diaphragm Pump Market study equips leaders with the contextual foresight and pragmatic tools needed to convert regulatory pressures, material volatility, and technological disruption into competitive advantage throughout 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Diaphragm Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Charging Port Door Actuators Market to Rise from USD 341.4 Million in 2025 to USD 994.36 Million by 2032 at a 16.5% CAGR — Asia‑Pacific Leads with USD 175.7M, Top‑5 Firms Hold 58.2%
By pmarketresearch, 2026-08-12
Worldwide Charging Port Door Actuators Market — Strategic Outlook for 2026 Decision-Making
Executive summary
PW Consulting’s newest market intelligence release on the Worldwide Charging Port Door Actuators market delivers a focused strategic toolkit for executives making technology, procurement, and partnership decisions in 2026. Built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study quantifies a market that grew from the low hundreds of millions in 2020 to an estimated USD 341.4 Million in 2025 and is projected to exceed USD 399 Million in 2026, tracking a compound annual growth rate (CAGR) of 16.5% over the forecast period. This trajectory underscores the actuator’s transition from optional convenience feature to mandatory element of EV platform design and charging ecosystem compliance.
Worldwide Customer Data Platforms for Marketing Market
Why this report matters for 2026 strategic choices
- Decision timing: 2026 is the inflection moment for many OEMs and Tier‑1s to lock actuator architectures into high-volume BEV and PHEV programs. Delays or missteps translate into multi-year sourcing and warranty costs.
- Regulatory demand: Evolving interface standards and functional safety requirements (including ISO 26262 compliance, child-proof and fail-safe features, and robust environmental sealing such as IP67) are reshaping product specifications and supplier shortlists.
- Supply-side friction: Component shortages — notably rare-earth magnets and precision gearsets — are extending lead times and increasing the premium on supply-chain resilience. Our field interviews identify models with extended lead times up to 12–16 weeks for specific actuator variants.
- Competitive concentration: The market shows meaningful aggregation at the top: the three largest suppliers capture a significant share of available program volume (CR3 ~42.5%), while the five largest capture a clear majority (CR5 ~58.2%). That dispersion profile has direct implications for negotiation leverage and M&A strategy.
Key market themes that will define supplier selection in 2026
- Digitalization and functional integration — actuators are migrating from simple electromechanical devices to networked subsystem nodes with LIN/CAN interfaces, integrated sensors, LED/HMI elements and software-defined safety features. Buyers should prioritize suppliers with proven system integration capabilities and over-the-air update pathways.
- Modularity and platform commonality — modular actuator platforms reduce per-variant engineering and cost on multi‑platform programs; they also accelerate assembly and serviceability at scale.
- Durability under real-world stress — anti-pinch, ice‑breaking, and extended cycle life under dust/water ingress remain non-negotiable for global programs; IP rating, material selection and kinematic robustness are purchase drivers.
- Regulation-driven feature creep — standardized charging interfaces and regional mandates are driving a baseline specification set (safety, locking, diagnostic) that must be embedded early in the design freeze.
- Supply-chain resilience — dual-sourcing strategies, alternative magnet chemistries, and vertical integration of key subcomponents are rising in procurement scorecards.
What the PW Consulting report delivers (practical, actionable contents)
This release is designed as a playbook for commercial and technical teams. The core deliverables include:
Bio-decontamination Chamber Market
- Market sizing and forecast model (2020–2032) with base‑year granularity and scenario sensitivity to EV adoption and interface standardization assumptions.
- Segmented demand maps by geography, actuator type (electronic vs. mechanical release), and vehicle architecture — presented with multi-scenario comparisons. Note: to preserve the report’s role as a strategic subscription asset we do not reproduce granular regional or application breakout figures in this public summary.
- Supplier benchmarking and scorecards: capability matrices covering product features, manufacturing footprint, quality metrics, program wins, and commercial terms.
- Bill‑of‑materials and cost‑build analysis for representative actuator architectures, including sensitivity to raw‑material price shocks and magnet supply constraints.
- Regulatory and standards matrix: mapping of the certifications, functional safety artifacts, and design guardrails buyers must require in 2026 contracts.
- Scenarios, decision timelines, and a procurement playbook: recommended milestones for OEMs and Tier‑1 suppliers to reduce launch risk on 2026/2027 programs.
Competitive landscape: strategic profiles and positioning
The market is composed of global Tier‑1s with integrated systems thinking, regional specialists focused on cost and volume, and engineering‑led players supplying higher‑margin, feature‑rich modules. Several representative players illustrate the landscape dynamics:
Worldwide Productivity Bots Software Market
- Magna International (Aurora, Canada) — positions itself as an integrated systems supplier with an automated SmartAccess™ Charge Port Door, emphasizing high‑torque actuators, false‑trigger protection and optional HMI integrations. Its value proposition aligns with OEMs seeking one‑stop modules that simplify assembly and reduce integration risk.
- Motion Controls Inc (MCi) (United States) — known for high speed/torque actuator solutions and patented control approaches (Lead‑Follow). MCi’s offerings cater to programs where dynamic actuation performance and mechanical abuse protection are key differentiators.
- NMB Technologies / MinebeaMitsumi (Japan) — brings scalable BLDC actuator platforms with LIN communication and advanced integration options (sensors, LEDs, wireless/gesture control). Their strength is in customization combined with high-volume manufacturing discipline.
- Haoyong Automotive Controls (Dongguan, China) — a supplier focused on multiple CPD actuator variants for frequent‑use durability at competitive cost points; an important option for high-volume Asian programs.
- Padmini VNA Mechatronics (India) — regional player supplying intelligent opening/closing actuators; relevant where nearshoring and local content requirements are part of program sourcing criteria.
- WITTE Automotive, Röchling Automotive, Marquardt, Johnson Electric, TE Connectivity — these vendors span integrated module design (flush integration, gesture/touch control), kinematic robustness, advanced locking mechanisms and station-side locking actuators. Together they represent differentiated options across premium and utility segments.
Recent industry moves illustrate the strategic shifts: Bosch’s co-development tie‑up with Volkswagen (March 2025) signals OEM demand for co‑engineered, highly reliable subsystems; Valeo’s modular actuator launch (Nov 2024) demonstrates the value placed on assembly efficiency and ingress protection; and Continental’s contract wins (May 2024) confirm the continued importance of incumbent program relationships. These developments point to accelerating productization and consolidation around suppliers who can support global programs end‑to‑end.
Strategic implications and recommended actions for 2026
- OEMs: Require actuator vendors to deliver upgrade paths for software, diagnostic telemetry and modular mechanical interfaces. Include explicit warranty and field‑failure remediation clauses tied to lifecycle cost assumptions.
- Tier‑1 suppliers: Prioritize investments in LIN/CAN‑enabled platforms and test capability for environmental extremes. Evaluate selective vertical integration of magnet grinding or gear machining to shorten lead times.
- Procurement teams: Implement dual-sourcing for critical components, insist on MAP‑level transparency in lead times, and require contingency plans for rare‑earth magnet shortages.
- R&D and product management: Accelerate work on compact kinematics, anti‑tamper and fail‑safe mechanical releases, and software defined behaviors that can be certified against functional safety standards.
- Investors and corporate development: Target mid‑tier engineering houses with complementary IP or regional footprint for bolt‑on consolidation: the top five suppliers control a majority of program volume, but pockets of specialist capability remain attractive acquisition targets.
What we intentionally withhold here — and why
In this release we deliberately surface overarching growth metrics, regulatory drivers and supplier archetypes to help readers assess strategic urgency. We do not publish the granular regional, vehicle‑type, or application breakout tables, nor the vendor‑level revenue shares and detailed price curves in this public summary. Those data points are central to program‑level negotiations and M&A diligence and are available in the full report and through PW Consulting advisory engagements.
Next steps — how to use the full report in 2026 planning
- Download the full report to access the interactive model (downloadable Excel) and supplier scorecards needed for RFP shortlists and sourcing scenarios.
- Engage PW Consulting for a one‑day strategy workshop: we’ll map your program timelines to actuator selection milestones, quantify tradeoffs and produce a prioritized supplier roadmap.
- Request a tailored M&A screening memo if you are evaluating consolidation or capability purchases in actuator subsegments.
For procurement, engineering and corporate strategy teams preparing 2026 rollouts, the window to influence actuator architecture and supply terms is immediate. PW Consulting’s market study turns market momentum into executable choices — covering forecast scenarios, regulatory obligations, supplier risk matrices, and the procurement playbook you need to negotiate the coming EV cycles. To access the full dataset, supplier scorecards and bespoke advisory services, please visit our report page or contact PW Consulting’s automotive practice directly.
For detailed analysis of this topic, please visit the official page: Worldwide Charging Port Door Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Suspension Bridge Apparatus Market Poised to Grow at 6.01% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Suspension Bridge Apparatus Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market study, with 2025 as the base year and a detailed forecast through 2032, offers a decision-grade view of the Worldwide Suspension Bridge Apparatus market. Between 2020 and 2025 the market expanded materially, and our modelling places the market on a steady growth trajectory from a 2025 base to a projected 2032 value consistent with a compound annual growth rate of 6.01%. For senior leaders planning budgets, R&D roadmaps, or M&A activity in 2026, this report is designed to convert ambiguity into executable strategy.
Worldwide Electron Multiplying Charge-Coupled Device (EMCCD) Cameras Market
Why this report matters in 2026
- Timing of investment: 2026 is a hinge year for capitalising on rising infrastructure and education spending cycles; our forecast and scenario work highlight when to accelerate product launches and when to conserve cash.
- Product and tech differentiation: The market is shifting from purely mechanical demonstrators to integrated, data-enabled lab systems. The report shows where digital data acquisition and software packages create defensible margins.
- Supply-chain risk management: Primary raw-material dynamics (notably high-carbon steel wire rod and the broader steel wire rope market) materially affect input costs and lead times — a risk that procurement teams must treat as strategic.
- Regulatory and standards alignment: Recent industry guidance on risk-based inspection for cable systems alters demand signals for advanced testing apparatus and inspection training tools.
What the report delivers — a practical toolkit for executives
We structured the study to be immediately actionable for C-suite and BU managers. Highlights include:
Red Cap Station Market
- A consolidated market sizing and forecast model (2020–2032) that supports sensitivity testing against price, adoption, and supply constraints.
- Proprietary buyer and end-user adoption curves for educational institutions, vocational trainers, and industrial research centres, enabling targeted GTM resource allocation.
- Supplier and product scorecards — qualitative and quantitative assessments that evaluate offering breadth, digital-readiness, global distribution capabilities, and after-sales service performance.
- Scenario playbooks (three-pronged) with prioritized tactical moves, timing windows, and estimated P&L impacts to guide 2026 spending decisions.
- Templates and annexes for procurement and RFPs, plus an implementation checklist for university and lab customers adopting digital data acquisition kits.
- Executive dashboards and an interactive spreadsheet model (licensed with the report) so clients can run bespoke what-if analyses for acquisition targets or product investments.
Market dynamics shaping 2026
- Structural demand: Continued global investment in infrastructure and emphasis on durable materials are lifting interest in both educational and testing apparatus for cable-supported structures. University civil engineering programmes and vocational trainers form a stable base of recurring demand.
- Raw material pressures: High-carbon steel wire rod remains the core feedstock for cable components. The broader steel wire rope market—valued in the multi‑billion USD range—exerts upward pressure on component costs and influences supplier negotiation dynamics.
- Standards and inspection guidance: The emergence of risk-based inspection guidelines for suspension bridge main cables is nudging demand towards apparatus that can simulate, measure and train against real-world inspection protocols. Vendors that map apparatus capabilities to these standards win institutional trust faster.
- Product convergence: The category is bifurcating: legacy manual bench-top apparatus continue to serve basic pedagogy, while digital data acquisition kits and software-integrated modules address the needs of advanced labs and industrial research centres. This convergence creates opportunities for premiumisation but raises complexity in manufacturing and support.
Competitive landscape — patterns and players
The market is moderately concentrated, with a small set of established educational-equipment manufacturers commanding a meaningful share and a broader long tail of regional suppliers. Our concentration metrics indicate that the top three players control a significant portion of the market, and the top five increase that share markedly — a structure that creates both stability and strategic openings for disruptors.
Severe Clinical Information System Market
Key archetypes observed among active vendors:
- Established European educational manufacturers: Companies headquartered in established engineering hubs deliver polished experiment modules with strong documentation, modular platforms and optional data acquisition. Their competitive advantages are brand recognition, established academic relationships, and integrated ecosystem offerings.
- Regional value providers: Several India- and Middle East-based suppliers focus on cost-competitive apparatus for teaching labs. Their strengths are localized distribution, customization for regional curricula, and aggressive pricing — attractive to institutions with constrained budgets.
- Hybrid and emergent suppliers: A subset of vendors blend mechanical rigs with software analytics or add-ons that target research centres and industrial customers. These firms are often the ones to watch for potential partnerships or acquisition targets if you are seeking a capability lift in digital measurement and analytics.
Example corporate positioning (high level): TecQuipment and similar UK-based manufacturers are positioned around modularity and integration options; a number of continental European providers emphasize strength-of-materials realism; several regional suppliers in India and the Middle East prioritise cost and ease of maintenance for local academic markets. Each positioning implies different go-to-market implications for channel partners and OEM buyers.
Strategic implications & recommended actions for 2026
We translate the analysis into a short list of recommended priorities for executives planning 2026 actions. Each recommendation is accompanied by operational considerations and near-term tactical steps.
- Prioritise digital upgrade paths: Invest in modular data-acquisition and software features that can be added to existing mechanical platforms. Tactical step: define a minimum viable analytics offering and pilot it with three university partners in 1H 2026.
- Supply-chain de-risking: Lock multi-source agreements for steel wire rope and related cable inputs; consider strategic buffer inventories for critical components. Tactical step: conduct a vendor risk-mapping exercise and initiate secondary-sourcing contracts by Q3 2026.
- Align product roadmaps to inspection/standards developments: Map apparatus specifications to emerging risk-based inspection guidelines and embed compliance training elements into product bundles. Tactical step: co-develop a certification module with an industry body or testing lab to accelerate adoption.
- Go-to-market segmentation: Tailor offers by customer sophistication: low-cost, maintenance-first bundles for teaching labs; premium analytics suites and training packages for research centres. Tactical step: redeploy 15–25% of marketing spend toward academic partnerships and conference demonstrations in 2026.
- Pursue bolt-on acquisitions selectively: Given moderate market concentration, targeted M&A can accelerate capability acquisition (digital analytics, inspection simulation) and market access. Tactical step: use our supplier scorecards to shortlist 3–5 targets compatible with fast integration.
- After-sales as a revenue lever: Deploy service contracts, calibration and inspection simulation subscriptions to create annuity revenue and reduce price sensitivity. Tactical step: design tiered service packages and pilot with existing customers to validate willingness to pay.
Scenario considerations — how to use the forecast in planning
The report models three pragmatic scenarios to assist capital allocation and contingency planning:
- Baseline: Continued steady infrastructure and education funding leads to predictable expansion aligned with our central CAGR. Actions: phase product investments and scale training partnerships.
- Accelerated investment: An upswing in infrastructure spending or university capital budgets accelerates demand for advanced test rigs and software. Actions: front-load production capacity and prioritise high-margin analytics modules.
- Supply shock / input cost pressure: Rapid steel-price rises and wire-rope shortages stress margins. Actions: activate contingency sourcing, index pricing clauses where possible, and fast-track substitution options for non-critical components.
Closing — the strategic value for 2026
PW Consulting’s Worldwide Suspension Bridge Apparatus market study is designed as an execution-focused briefing for 2026 — combining rigorous forecasting, supplier intelligence, and a playbook of prioritized actions that can be deployed immediately. We intentionally present deep diagnostic insight while preserving the granular segment-level tables, product-level pricing, and full supplier scorecards for the full report to ensure clients derive exclusive competitive advantage from the underlying data.
For procurement leads, product strategists, and corporate development teams targeting 2026, our study provides the models, checklists, and scenario templates to convert forecasts into measurable outcomes. Access to the complete dataset, interactive models, and supplier dossiers is available through the report portal; PW Consulting can also deliver an executive briefing and a tailored workshop to translate insights into your 2026 operating plan.
For detailed analysis of this topic, please visit the official page: Worldwide Suspension Bridge Apparatus Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Condensation-Cure Silicone Rubber Market to Reach USD 3,132.81 Million by 2032 at a 4.82% CAGR, Led by Asia Pacific (USD 1,004.92M)
By pmarketresearch, 2026-08-12
Worldwide Condensation Cure Silicone Rubber Market — Strategic Imperatives for 2026
Executive summary
PW Consulting today releases an executive briefing based on its new market research, Worldwide Condensation Cure Silicone Rubber Market (base year 2025, forecast 2026–2032). The analysis synthesizes five years of historical performance (2020–2025) and a forward-looking forecast built around a 4.82% compound annual growth rate (CAGR). Our model projects the global condensation cure silicone rubber market to expand steadily through 2032, reflecting resilient end-market demand, selective premiumization, and structural supply-side pressures driven by raw material cost dynamics and environmental policy shifts.
Clinical Biochemical Analyzer Market
This briefing highlights the strategic value of the full report for corporate leaders making 2026 investment and commercial decisions. It intentionally surfaces high-confidence, actionable insights while withholding granular segment-level figures to encourage readers to consult the complete dataset and proprietary tools available in the full report.
HFC Lithium Iron Phosphate Battery Market
Market trajectory and headline metrics
-
Base-year calibration: the report uses 2025 as the reference year and captures market movements across 2020–2025 to validate trend drivers and volatility patterns.
Worldwide Financial Data APIs Market -
Growth profile: the forecast period 2026–2032 assumes a mid-single-digit CAGR (4.82%), reflecting a balance between incremental end-use expansion and constrained raw material supply that limits aggressive volume-driven growth.
-
Concentration and competitive dynamics: the sector remains moderately consolidated; our CR3 and CR5 analyses indicate that a handful of global and regional players retain significant share, creating both barriers and pockets of opportunity for agile challengers and tier-two specialists.
Why this matters for 2026 decision-makers
For executives planning capital allocation, supply arrangements, or go-to-market pivots in 2026, the condensation cure silicone rubber market presents a classic case where product lifecycles and upstream volatility intersect. Key implications include:
-
Margin resilience vs. price sensitivity: manufacturers with differentiated formulations, robust value-added service offerings (e.g., custom cure profiles, catalysts, and thixotropes), or integrated downstream channels are positioned to defend margins as raw material costs shift. Commodity-focused producers will face tighter pricing power unless they secure advantaged feedstock contracts.
-
Supply-chain risk management: D4 and other siloxane feedstock swings materially affect operations. Our scenario simulations show that a sustained step-up in feedstock cost requires a rapid reassessment of contract tenors, hedging strategies, and, in some cases, local sourcing or dual-sourcing options to preserve capacity utilization.
-
Regulatory and ESG-driven costs: tighter environmental policies—particularly in major producing geographies—translate into both higher compliance costs and opportunities for premium, low-emission product lines. Strategic planners should treat regulatory shifts as a source of competitive advantage when acted upon proactively.
Supply-side pressures: raw materials, costs and policy
The market outlook is materially affected by raw material and regulatory dynamics:
-
Feedstock inflation: our sector analysis highlights a notable rise in key inputs, with D4 prices increasing more than 20% in the most recent cycle. Parallel increases in industrial-grade silicone oils—especially for higher-viscosity and modified grades—have placed meaningful cost pressure on producers.
-
Regional production impacts: environmental policy tightening in certain manufacturing hubs has constrained capacity expansion and raised per-unit production costs. These dynamics are uneven across regions, creating arbitrage opportunities for manufacturers able to relocate or optimize footprint without compromising lead times.
-
Pass-through strategies: the effectiveness of price pass-through varies by customer segment and application. Our pricing elasticity matrices and negotiation playbooks—detailed in the full report—show which end-users accept premium formulations and which segments are more price-sensitive.
Segment dynamics (what we disclose — and what we intentionally withhold)
The condensation cure silicone rubber market serves a diverse set of end-use applications and formulation types. Our analysis identifies clear demand-side pockets — from mold-making and tooling to construction and electronics potting — each with distinct purchase drivers and service expectations. However, to preserve the commercial value of our primary research and proprietary segmentation, the full split tables and granular regional/application shares are reserved for the complete report.
What we do share here is directional: mold-making and specialized tooling remain fundamental volume anchors; serviceable, fast-curing grades command premiums in time-sensitive applications; and bulk-oriented construction sealant applications provide scale but face higher cyclical exposure. Decision-makers should treat this summary as a roadmap; the full dataset provides the precise allocation necessary for SKU rationalization or targeted capex.
Competitive landscape — profiles and strategic posture
The consolidation profile of the industry is such that both global majors and regional specialists play complementary roles. Our competitive analysis evaluates capabilities across product breadth, formulation expertise, geographic reach, customer channels, and R&D intensity. Highlights from the company-level assessment include:
-
Smooth-On, Inc. — A strong brand in mold-making with a broad portfolio of tin-cure silicone systems and market recognition among craft and professional segments. Their emphasis on multiple hardness ranges and established channel presence gives them durable access to small-to-medium volume users.
-
Polytek Development Corp. — Known for flexible, high-tear-strength materials and formulations that reduce cure inhibition risk. Polytek’s technical positioning benefits applications where reliability and repeatability are indispensable.
-
Silicones, Inc. — Longstanding experience in condensation cure RTV-2 chemistry and an ability to produce custom formulations for potting and special-effects markets. Their customization capability is a strategic differentiator for niche industrial uses.
-
CHT Group — Offers application-specific additives (catalysts, thixotropes) and custom solutions, and has remained visible in industry fora. Their participation in trade shows underscores a go-to-market strategy centered on systems sales rather than commoditized product delivery.
-
BBN Materials and Silpak — Regional specialists with a focus on tailorability and speed-to-market for craft, GFRC, and concrete applications. These firms serve clients seeking fast iterations and localized technical support.
-
Elkem Silicones, Shin-Etsu, and Momentive — Large-scale suppliers with global reach and broad silicone portfolios. Their strengths lie in raw material integration, R&D scale, and the ability to offer rapid-cure and high-thermal-stability grades for demanding industrial uses.
Across the competitive set, our supplier scorecards rank firms on technical depth, formulation flexibility, cost competitiveness, channel strength, and readiness for regulatory shifts. The CR3/CR5 concentration metrics point to an environment where aggregation and targeted partnerships (e.g., catalyst supply agreements, private-label programs) are viable routes to scale.
Practical contents of the full PW Consulting report
The full report which this briefing accompanies is designed as an operational toolkit for commercial leaders and strategy teams. It includes:
-
Detailed datasets: annualized market size time series and reconciled demand models by region, formulation type, and application (full splits available in the report).
-
Price and raw material sensitivity models: interactive scenarios that map D4 and silicone oil price movements to margin outcomes and suggested pass-through thresholds.
-
Supplier scorecards and procurement playbooks: benchmarking of leading players and contract negotiation levers to secure capacity and preferential pricing.
-
Go-to-market playbooks: commercialization roadmaps for premium grades, rapid-cure offerings, and service-led propositions for tooling and electronics potting segments.
-
M&A and partnership heatmaps: identification of strategic targets and alliance structures to obtain technology, geographic access, or feedstock security.
-
Regulatory risk matrix: assessment of policy trajectories in principal manufacturing jurisdictions and mitigation strategies including compliance roadmaps and technology substitution pathways.
Recommended 2026 actions — a prioritized checklist
-
Hedge or diversify feedstock exposure: immediately evaluate contract tenors and local sourcing options in response to the recent D4 price surge.
-
Reassess product mix with profitability lenses: prioritize premium, differentiated grades where demand acceptance for higher price exists, and optimize SKU complexity for high-volume, low-margin lines.
-
Strengthen technical service and formulation capabilities: invest in catalyst, thixotrope, and cure-control expertise to deepen customer stickiness.
-
Explore vertical partnerships: secure upstream commitments via long-term supply agreements or JV structures in regions where environmental policy creates supply constraints.
-
Monitor regulatory developments proactively: build contingency plans for compliance-related cost shocks and convert early compliance into a marketable ESG advantage.
Conclusion and next steps
The condensation cure silicone rubber market in 2026 will reward disciplined strategy: firms that combine technical differentiation, disciplined cost management, and pragmatic supply-security moves will capture disproportionate value as the market expands on a mid-single-digit CAGR. PW Consulting’s full report delivers the granular data, scenario tools, and playbooks needed to operationalize these strategic choices.
To access the complete dataset, company scorecards, and interactive models referenced in this briefing, please visit PW Consulting’s report page for Worldwide Condensation Cure Silicone Rubber Market. The full report contains the detailed regional and application splits, financial-model templates, and executable playbooks necessary for immediate incorporation into 2026 planning cycles.
For detailed analysis of this topic, please visit the official page: Worldwide Condensation Cure Silicone Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com