

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Charging Port Door Actuators Market to Rise from USD 341.4 Million in 2025 to USD 994.36 Million by 2032 at a 16.5% CAGR — Asia‑Pacific Leads with USD 175.7M, Top‑5 Firms Hold 58.2%

Worldwide Charging Port Door Actuators Market — Strategic Outlook for 2026 Decision-Making
Executive summary
PW Consulting’s newest market intelligence release on the Worldwide Charging Port Door Actuators market delivers a focused strategic toolkit for executives making technology, procurement, and partnership decisions in 2026. Built on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the study quantifies a market that grew from the low hundreds of millions in 2020 to an estimated USD 341.4 Million in 2025 and is projected to exceed USD 399 Million in 2026, tracking a compound annual growth rate (CAGR) of 16.5% over the forecast period. This trajectory underscores the actuator’s transition from optional convenience feature to mandatory element of EV platform design and charging ecosystem compliance.
Worldwide Customer Data Platforms for Marketing Market
Why this report matters for 2026 strategic choices
- Decision timing: 2026 is the inflection moment for many OEMs and Tier‑1s to lock actuator architectures into high-volume BEV and PHEV programs. Delays or missteps translate into multi-year sourcing and warranty costs.
- Regulatory demand: Evolving interface standards and functional safety requirements (including ISO 26262 compliance, child-proof and fail-safe features, and robust environmental sealing such as IP67) are reshaping product specifications and supplier shortlists.
- Supply-side friction: Component shortages — notably rare-earth magnets and precision gearsets — are extending lead times and increasing the premium on supply-chain resilience. Our field interviews identify models with extended lead times up to 12–16 weeks for specific actuator variants.
- Competitive concentration: The market shows meaningful aggregation at the top: the three largest suppliers capture a significant share of available program volume (CR3 ~42.5%), while the five largest capture a clear majority (CR5 ~58.2%). That dispersion profile has direct implications for negotiation leverage and M&A strategy.
Key market themes that will define supplier selection in 2026
- Digitalization and functional integration — actuators are migrating from simple electromechanical devices to networked subsystem nodes with LIN/CAN interfaces, integrated sensors, LED/HMI elements and software-defined safety features. Buyers should prioritize suppliers with proven system integration capabilities and over-the-air update pathways.
- Modularity and platform commonality — modular actuator platforms reduce per-variant engineering and cost on multi‑platform programs; they also accelerate assembly and serviceability at scale.
- Durability under real-world stress — anti-pinch, ice‑breaking, and extended cycle life under dust/water ingress remain non-negotiable for global programs; IP rating, material selection and kinematic robustness are purchase drivers.
- Regulation-driven feature creep — standardized charging interfaces and regional mandates are driving a baseline specification set (safety, locking, diagnostic) that must be embedded early in the design freeze.
- Supply-chain resilience — dual-sourcing strategies, alternative magnet chemistries, and vertical integration of key subcomponents are rising in procurement scorecards.
What the PW Consulting report delivers (practical, actionable contents)
This release is designed as a playbook for commercial and technical teams. The core deliverables include:
Bio-decontamination Chamber Market
- Market sizing and forecast model (2020–2032) with base‑year granularity and scenario sensitivity to EV adoption and interface standardization assumptions.
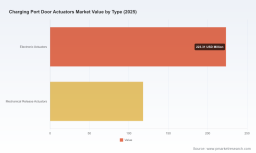
- Segmented demand maps by geography, actuator type (electronic vs. mechanical release), and vehicle architecture — presented with multi-scenario comparisons. Note: to preserve the report’s role as a strategic subscription asset we do not reproduce granular regional or application breakout figures in this public summary.
- Supplier benchmarking and scorecards: capability matrices covering product features, manufacturing footprint, quality metrics, program wins, and commercial terms.
- Bill‑of‑materials and cost‑build analysis for representative actuator architectures, including sensitivity to raw‑material price shocks and magnet supply constraints.
- Regulatory and standards matrix: mapping of the certifications, functional safety artifacts, and design guardrails buyers must require in 2026 contracts.
- Scenarios, decision timelines, and a procurement playbook: recommended milestones for OEMs and Tier‑1 suppliers to reduce launch risk on 2026/2027 programs.
Competitive landscape: strategic profiles and positioning
The market is composed of global Tier‑1s with integrated systems thinking, regional specialists focused on cost and volume, and engineering‑led players supplying higher‑margin, feature‑rich modules. Several representative players illustrate the landscape dynamics:
Worldwide Productivity Bots Software Market
- Magna International (Aurora, Canada) — positions itself as an integrated systems supplier with an automated SmartAccess™ Charge Port Door, emphasizing high‑torque actuators, false‑trigger protection and optional HMI integrations. Its value proposition aligns with OEMs seeking one‑stop modules that simplify assembly and reduce integration risk.
- Motion Controls Inc (MCi) (United States) — known for high speed/torque actuator solutions and patented control approaches (Lead‑Follow). MCi’s offerings cater to programs where dynamic actuation performance and mechanical abuse protection are key differentiators.
- NMB Technologies / MinebeaMitsumi (Japan) — brings scalable BLDC actuator platforms with LIN communication and advanced integration options (sensors, LEDs, wireless/gesture control). Their strength is in customization combined with high-volume manufacturing discipline.
- Haoyong Automotive Controls (Dongguan, China) — a supplier focused on multiple CPD actuator variants for frequent‑use durability at competitive cost points; an important option for high-volume Asian programs.
- Padmini VNA Mechatronics (India) — regional player supplying intelligent opening/closing actuators; relevant where nearshoring and local content requirements are part of program sourcing criteria.
- WITTE Automotive, Röchling Automotive, Marquardt, Johnson Electric, TE Connectivity — these vendors span integrated module design (flush integration, gesture/touch control), kinematic robustness, advanced locking mechanisms and station-side locking actuators. Together they represent differentiated options across premium and utility segments.
Recent industry moves illustrate the strategic shifts: Bosch’s co-development tie‑up with Volkswagen (March 2025) signals OEM demand for co‑engineered, highly reliable subsystems; Valeo’s modular actuator launch (Nov 2024) demonstrates the value placed on assembly efficiency and ingress protection; and Continental’s contract wins (May 2024) confirm the continued importance of incumbent program relationships. These developments point to accelerating productization and consolidation around suppliers who can support global programs end‑to‑end.
Strategic implications and recommended actions for 2026
- OEMs: Require actuator vendors to deliver upgrade paths for software, diagnostic telemetry and modular mechanical interfaces. Include explicit warranty and field‑failure remediation clauses tied to lifecycle cost assumptions.
- Tier‑1 suppliers: Prioritize investments in LIN/CAN‑enabled platforms and test capability for environmental extremes. Evaluate selective vertical integration of magnet grinding or gear machining to shorten lead times.
- Procurement teams: Implement dual-sourcing for critical components, insist on MAP‑level transparency in lead times, and require contingency plans for rare‑earth magnet shortages.
- R&D and product management: Accelerate work on compact kinematics, anti‑tamper and fail‑safe mechanical releases, and software defined behaviors that can be certified against functional safety standards.
- Investors and corporate development: Target mid‑tier engineering houses with complementary IP or regional footprint for bolt‑on consolidation: the top five suppliers control a majority of program volume, but pockets of specialist capability remain attractive acquisition targets.
What we intentionally withhold here — and why
In this release we deliberately surface overarching growth metrics, regulatory drivers and supplier archetypes to help readers assess strategic urgency. We do not publish the granular regional, vehicle‑type, or application breakout tables, nor the vendor‑level revenue shares and detailed price curves in this public summary. Those data points are central to program‑level negotiations and M&A diligence and are available in the full report and through PW Consulting advisory engagements.
Next steps — how to use the full report in 2026 planning
- Download the full report to access the interactive model (downloadable Excel) and supplier scorecards needed for RFP shortlists and sourcing scenarios.
- Engage PW Consulting for a one‑day strategy workshop: we’ll map your program timelines to actuator selection milestones, quantify tradeoffs and produce a prioritized supplier roadmap.
- Request a tailored M&A screening memo if you are evaluating consolidation or capability purchases in actuator subsegments.
For procurement, engineering and corporate strategy teams preparing 2026 rollouts, the window to influence actuator architecture and supply terms is immediate. PW Consulting’s market study turns market momentum into executable choices — covering forecast scenarios, regulatory obligations, supplier risk matrices, and the procurement playbook you need to negotiate the coming EV cycles. To access the full dataset, supplier scorecards and bespoke advisory services, please visit our report page or contact PW Consulting’s automotive practice directly.
For detailed analysis of this topic, please visit the official page: Worldwide Charging Port Door Actuators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com