

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Digital Movie Projector Market Valued at USD 4,412.5 Million in 2025, Poised for 7.21% CAGR Through 2032

Worldwide Digital Movie Projector Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Digital Movie Projector Market positions enterprise leaders to make confident strategic choices in 2026. Built on a verified historical series (2020–2025) and a rigorous forecast (2026–2032), the report shows the market expanding from USD 4,412.5 Million in 2025 to an anticipated USD 7,183.43 Million by 2032, representing a compound annual growth rate (CAGR) of 7.21% over the forecast window. That trajectory, combined with high market concentration among a handful of tier‑one suppliers, creates a decision environment where timing, supplier strategy, and technology selection materially affect both cost and competitive positioning.
Cone-Beam Computed Tomography (CBCT) Equipment for Oral Maxillofacial Market
Market trajectory and macro dynamics
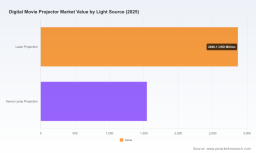
The projector market’s growth is being driven by a convergence of content demand, infrastructure investments (including large-scale cultural and entertainment projects), and rapid innovation in illumination and imaging subsystems. Laser illumination—now the dominant shipment generator among major original equipment manufacturers—has moved from niche to mainstream, materially reshaping product lifecycles, service models, and total cost of ownership calculations. Our cross-validated shipment and revenue models indicate that laser solutions accounted for a clear majority of 2025 volumes among primary vendors, and that trend continues into 2026.
Worldwide Multi Axis Controllers Market
At the same time, structural characteristics matter. Market concentration is high: the top three manufacturers control a very large share of revenue, and the top five capture an even larger share—creating an oligopolistic market dynamic that benefits incumbents but raises strategic issues for buyers and new entrants alike. Supply-side constraints—most notably the concentrated supply of high-performance laser diodes and rare earth inputs—introduce a non-trivial risk premium into procurement and capex planning. Licensing realities around key imaging technologies further reduce the field of substitute suppliers for certain high-brightness, DLP‑based cinema solutions.
Bifurcated Covered Stent Market
Why this matters for 2026 decision-makers
- CapEx planning: With stronger growth and upward price pressure on key components, late-2026 purchases may face higher acquisition and service costs than comparable 2025 deals. The value of staged procurement and vendor financing has increased.
- Technology choices: Laser vs. lamp, DLP vs. alternative imaging stacks, and 4K/120hz‑capable architectures each carry different upgrade paths and service cost profiles. Early adopters capture content and premium pricing advantages, while conservative buyers reduce technical obsolescence exposure.
- Supplier negotiation: High concentration allows leading OEMs to set terms; however, bundled services, multi-year maintenance contracts, and volume commitments remain effective levers for cost mitigation.
- Supply chain resilience: Rare earth and diode supply concentration means procurement teams should incorporate second‑source strategies, buffer inventories, and indexed pricing clauses into contracts.
- M&A & partnerships: Niche optics, laser diode assemblers, and software/automation players represent high-leverage targets for fast-tracking capabilities and protecting margins.
Competitive landscape — who matters and why
The market’s competitive core is populated by a few established players whose product roadmaps, manufacturing scale, and technology licenses shape industry direction. PW Consulting’s competitive assessment synthesizes public disclosures, primary interviews, and product teardowns to map relative strengths and strategic intent for each major vendor.
- Barco NV (Belgium) — A leader in laser-based cinema projectors, Barco’s next‑generation families focus on high‑brightness RGB laser systems, simplified serviceability, and performance consistency for commercial theaters. Barco’s investments in unified platforms reduce SKU complexity and accelerate rollout for large exhibitor chains.
- Christie Digital Systems (U.S., Ushio subsidiary) — Christie maintains a broad cinema portfolio with strong R&D in illumination (Phazer) and a track record of high-performance HDR/ Dolby Vision integrations. Recent mid‑2020s product introductions and expansions broaden their addressable screens, especially for small to mid‑size venues.
- NEC Display Solutions (Sharp NEC, Japan) — NEC’s DLP‑based strategy emphasizes reliability and long service life, particularly for theatre chains prioritizing uptime. Their laser models are engineered for low total operating cost and standardized maintenance workflows.
- Sony Corporation (Japan) — While Sony has shifted its focus across segments, its imaging technology heritage—especially in high‑end projection—keeps it relevant in premium and niche segments where proprietary display tech and color science matter.
Recent product and component developments materially change competitive calculus. In 2025–26, Christie refreshed product lines with Phazer‑illuminated CineLife+ variants and compact 1DLP Jazz series models; Texas Instruments unveiled next‑generation DMD chipsets at CES 2026 that enable higher brightness, better native contrast and 4K/120 fps capabilities; and major vendors expanded RGB and RGBH offerings to capture a wider portion of screen types and exhibitor footprints. Together, these moves compress feature differentiation while increasing technical barriers for late entrants.
What PW Consulting’s report delivers — practical, transaction‑oriented intelligence
This study is designed as a decision toolset, not just a descriptive market portrait. For boardrooms, procurement teams, and product leaders we include:
- Validated historical demand and revenue series (2020–2025) and a probabilistic forecast (2026–2032) with scenarios keyed to supply shocks and premium content cycles.
- Portfolio strategy playbooks: decision trees for purchase vs. lease, upgrade cadence models, and vendor selection matrices based on TCO, uptime, and service network depth.
- Procurement toolkits: supplier scorecards, negotiation scripts, indexed contract templates tied to raw material clauses, and suggested warranty/service bundling strategies.
- Supply risk dashboards: heatmaps of component concentration, supplier single‑point failures, and contingency plans for diode and rare earth disruptions.
- Technology adoption frameworks: capability maps aligning illumination and imaging choices to exhibitor needs (from boutique cinemas to megaplex chains), including upgrade prioritization and obsolescence timelines.
- M&A and partnership screens: prioritised targets, valuation anchors, and integration playbooks for buyers seeking vertical or capability consolidation.
- Executive-ready outputs: a concise strategic memo, investor briefing slides, and an interactive model (Excel + dashboard) so leadership can dynamically stress-test key assumptions.
Methodology and confidence levels
The report integrates multi-source inputs: audited vendor financials, OEM product specifications and teardowns, primary interviews with exhibitors and integrators, component supplier checks, and macroeconomic overlays. Forecasts use scenario-based Monte Carlo simulations to quantify downside (supply shock) and upside (accelerated global content rollouts) outcomes. Where single‑source commercial data exist—such as licensed DLP distributions—we explicitly flag those constraints and model alternatives. Overall, our confidence bands tighten at the market level (total revenue and CAGR) and widen at ultra‑granular segment slices, which is why the report delivers both high-certainty macro guidance and carefully validated segment scenarios for paid subscribers.
Immediate recommendations — what to do in 2026
- Accelerate procurement talks that include indexed price protections and multisupplier commitments to guard against diode and rare‑earth volatility.
- Prioritize pilot deployments of next‑generation 4K/120 workflows in flagship venues to capture premium viewers and set content‑delivery expectations.
- Negotiate multi-year service agreements with performance SLAs to offset the risk of new tech adoption and protect uptime during content premieres.
- For investors and M&A teams: focus on optics and diode assembly assets that can provide margin-insulating integration value to platform OEMs.
- In procurement and operations: deploy the report’s supply risk heatmaps and TCO templates before Q3 2026 capital approvals.
Next steps and how to obtain the full study
This release is a strategic preview intended to demonstrate the report’s depth and immediate applicability while directing decision‑makers to the full dataset, supplier-level scorecards, and forecast models. PW Consulting’s full Worldwide Digital Movie Projector Market report contains the primary datasets, supplier profiles, and executable toolkits referenced here—essential inputs for any organization planning capex, procurement, or partnership activity in 2026.
To access the complete study, interactive models, and bespoke advisory engagements, visit PW Consulting’s research portal or contact our industrial technology practice for a briefing. Our team will tailor the deliverables—scenarios, supplier scorecards, and negotiation playbooks—to your specific risk tolerance and business model.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Movie Projector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com