

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide MLCC Dielectric Materials Market Poised for 7.05% CAGR Through 2026–2032

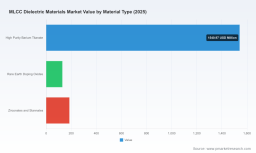
PW Consulting: Strategic Brief — Worldwide MLCC Dielectric Materials Market (2026 Outlook)
As the multilayer ceramic capacitor (MLCC) ecosystem enters a new phase of product miniaturization, electrification, and performance specialization, dielectric materials are emerging as the strategic fulcrum for OEMs, material suppliers, and capital allocators alike. PW Consulting’s latest market study — driven from a 2025 base and projecting through 2032 — shows the global MLCC dielectric materials market reached approximately USD 1,856.4 Million in 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 7.05% over the 2026–2032 horizon, reaching an expected market size near USD 2,981.0 Million by 2032. This press release summarizes the operational intelligence and decision-grade implications the full report delivers for executives planning resource allocation, R&D priorities, and go-to-market timing in 2026.
Induction Furnace Power Transformers Market
Why 2026 Is a Strategic Inflection Point
-
Convergence of technology cycles: Continued demand for higher capacitance per footprint, tighter dielectric tolerances for RF/5G front-ends, and the transition to automotive and industrial-grade reliability are compressing development timelines for dielectric chemistries and processing.
Worldwide Amps & Effects Market -
Supply-side tightening and concentration: The market shows material concentration at the top tier — our analysis indicates a high degree of market share captured by a few global players — creating both supply risk and strategic leverage for integrated MLCC manufacturers and material specialists.
Vertical Centrifuge Tube Market -
Regulatory and sustainability pressure: RoHS and lead-free mandates, together with customer-driven lifecycle carbon expectations, are forcing earlier-than-expected reformulations and qualification programs for legacy dielectric powders.
Key Market Dynamics Shaping 2026 Decisions
-
Material innovation as product differentiation: High‑purity barium titanate remains the workhorse dielectric base, but the competitive advantage is shifting to advanced formulations — rare-earth-doped oxides, engineered zirconates and stannates, and process-enabled microstructure control that underpins both Class I (C0G/NP0) and Class II (X7R, X5R, Y5V) performance envelopes.
-
Miniaturization vs. capacitance trade-offs: The race to squeeze microfarads into the smallest case sizes is increasing pressure on dielectric layering and particle engineering. Suppliers that can marry ultra-thin layers with stable permittivity and low loss will command premium positions in mobile, 5G, and EV applications.
-
Verticalization and strategic partnerships: Leading MLCC producers are investing in in-house dielectric R&D and securing upstream powder supply through long-term contracts or equity stakes — a dynamic that changes negotiation power and time-to-market for new formulations.
-
Geopolitical and supply-chain considerations: Concentration of high-purity powder production in specific geographies, combined with specialized processing know-how, means buyers must model multi-source strategies and consider geographically de-risked inventories for 2026 launch programs.
What the Report Delivers — Practical, Transaction-Ready Intelligence
PW Consulting’s Worldwide MLCC Dielectric Materials Market report is built for decision-makers who require executable insights rather than academic descriptions. The study pairs a rigorous, model-driven market forecast (2026–2032) with modular tools and playbooks that can be operationalized within 90–180 days:
-
Market sizing and scenario models — base, upside, and stress cases aligned to macro demand drivers and technology adoption curves (interactive spreadsheet models accompany the report).
-
Technology roadmaps — comparative performance matrices for Class I vs. Class II dielectrics, emergence timelines for doped oxides, and threshold conditions (temperature, voltage, miniaturization) where specific materials become preferred.
-
Supply-chain maps — tiered supplier lists for powders, formulation houses, and sintering/processing specialists, with risk flags tied to geographic concentration, single points of failure, and qualification lead times.
-
Commercial playbooks — go-to-market sequencing for entrants and incumbents including partnership archetypes, pricing benchmarks, and recommended contract structures for long-term powder supply or joint development agreements.
-
Regulatory and ESG checklist — compliance requirements for lead-free and RoHS-aligned formulations, anticipated testing and certification schedules, and suggestions for lifecycle disclosure to support OEM procurement policies.
Competitive Landscape — Who Matters and Why
The dielectric materials and MLCC production landscape features a mix of vertically integrated MLCC champions, specialized material formulators, and powder manufacturers. The competitive dynamics are defined by three interlocking capabilities: material science depth, process integration (layering, sintering, termination technologies), and scale of manufacturing.
-
Integrated MLCC leaders: Companies such as Murata Manufacturing, Samsung Electro-Mechanics, and TDK continue to hold structural advantages through deep in-house R&D on dielectric formulations and advanced layering processes. Their recent moves — from Murata’s commercialization of extremely high-capacitance 0402 MLCCs to TDK’s expansion of low-resistance, soft-termination automotive lines — illustrate how integrated players convert material advances into product differentiation.
-
Regional and portfolio players: Yageo (including KEMET/AVX), Taiyo Yuden, Kyocera/AVX, and Walsin play to strengths in product breadth, application-specific qualifications (automotive, medical, aerospace), and flexible manufacturing footprints. These players are often the first to respond to customer qualification windows in targeted market segments.
-
Specialists and upstream suppliers: Material-focused companies such as Prosperity Dielectrics, Vibrantz Technologies, Sakai Chemical Industry, and several Japanese powder producers (including Nippon Chemical, Fuji Titanium, and Toho Titanium) supply the high-purity ceramic powders and tailored formulations that underpin the next generation of MLCCs. Their hydrothermal and engineered powder technologies remain central to achieving high density and reliability in ultra-thin dielectric layers.
-
Niche high-reliability suppliers: US-based Vishay, Knowles Precision Devices, and others retain strategic roles in military, medical and certain industrial markets where qualification timelines and reliability thresholds create premium windows.
From a market structure standpoint, the market exhibits notable concentration at the top tiers, creating competitive moats for incumbents while leaving opportunity for specialized entrants through vertical partnerships and focused IP plays. Managers should assume tighter access to differentiated dielectric chemistries without contractual or JV safeguards.
Recent Developments and What They Signal
-
Murata’s mass production of 0402 high-capacitance devices (47 µF) underscores how material-layering innovation is enabling size-to-capacitance leaps, directly impacting mobile and wearable BOMs.
-
TDK’s product expansions — particularly low-resistance soft-termination MLCCs and high-voltage C0G types — highlight demand in automotive and industrial power electronics where both electrical performance and mechanical robustness matter.
Together these product moves reinforce a strategic playbook: accelerate material qualification programs for targeted applications, and align production scale-up with customer qualification windows to avoid missed adoption cycles in 2026.
Strategic Recommendations for 2026
-
Prioritize material partnerships over short-term price plays. Securing co-development or long-term supply agreements with advanced powder/formulation suppliers will be a decisive advantage for firms launching new MLCC SKUs in 2026.
-
Invest in accelerated qualification resources. The parallel pressures of miniaturization and automotive-grade requirements demand parallel investments in test labs and accelerated life testing to compress qualification timelines.
-
Adopt a dual-sourcing strategy for critical powders. Identify and qualify at least one geographically diversified supplier to mitigate regional disruptions and regulatory risks.
-
Assess vertical integration selectively. For firms with scale and capital capacity, backward integration into powder formulation or equity stakes in strategic suppliers can protect roadmaps; for others, exclusivity arrangements and co-development licensing can yield faster routes to differentiated specs.
-
Embed ESG into material strategy. Reformulation for lead-free, lifecycle reporting, and lower-temperature sintering processes will increasingly influence OEM selection criteria and cost of compliance.
How PW Consulting’s Report Supports 2026 Decision Windows
Executives evaluating capital allocation, M&A targets, or R&D roadmaps will find the report’s scenario models, supplier scoring, and time-to-market matrices especially useful. Our deliverables are structured to enable three concrete actions within 90 days: identify the top two critical materials for your 2026 product roadmap; select and initiate discussions with at least one upstream supplier for pilot qualification; and construct a contingency sourcing plan for any single-source powders in your bill of materials.
Next Steps
PW Consulting has intentionally preserved detailed segment-level forecasts, regional breakdowns, and supplier-level financials for subscribers of the full report and data pack. These are the core inputs most procurement officers and corporate strategists need when converting insights into commitments. To access the full dataset, interactive models, and supplier scorecards that underpin our 2026 playbooks, visit our Worldwide MLCC Dielectric Materials Market report page or contact our client services to schedule a briefing tailored to your strategic agenda.
For detailed analysis of this topic, please visit the official page: Worldwide MLCC Dielectric Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com