

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Worldwide Occlusion Spray Market to Rise from USD 115.45 Million (Base Year 2025) to USD 165.72 Million by 2032 at 5.28% CAGR — Europe (USD 42.14M), Green Sprays (USD 48.49M) and Dental Laboratories (USD 65.81M) Lead; CR3 at 48.5%
By pmarketresearch, 2026-08-12
Worldwide Occlusion Spray Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s latest market intelligence brief on the Worldwide Occlusion Spray Market provides an executive-grade synthesis designed to inform 2026 strategic choices across product development, regulatory planning, channel strategy, and M&A. Drawing on a 2020–2025 historical baseline and a 2026–2032 forecast horizon, the report combines a disciplined market-sizing framework with practitioner-ready diagnostics. The market is modeled in USD (Million) using 2025 as the base year; our top-line projection shows the market continuing to expand at a compound annual growth rate (CAGR) of approximately 5.28% through the forecast window.
Worldwide Community Association Management Software Market
Market Snapshot: What the Top-Line Numbers Mean for 2026
At a macro level, the occlusion spray market is modest in absolute scale but structurally resilient. After steady growth over the 2020–2025 historical period, our base-year estimate for 2025 and the near-term projection for 2026 reflect continued expansion driven by incremental adoption in both dental and industrial scanning workflows, as well as routine replacement demand tied to consumable packaging formats.
2 Chamber Bag Market
-
Growth profile — The modeled 5.28% CAGR signals a market in steady, profitable expansion rather than a hyper-growth environment. That profile favors focused investments — product line expansions, optimized distribution, and selective partnerships — over wide-scale disruption bets.
Worldwide Money Insurance Market -
Market scale — Our annual model provides year-on-year revenue projections through 2032 to support rolling three- to five-year business plans. These projections enable scenario analysis for CAPEX, working capital, and commercial resource allocation in 2026 and beyond.
Why This Report Matters for 2026 Strategic Decisions
For executives preparing budgets, approving new product projects, or evaluating M&A targets, the most valuable intelligence is not simply the headline growth rate, but the "so what" — how that growth maps to margin levers, channel economics, and regulatory posture. The report delivers that operational linkage through three types of insight:
-
Commercial levers: We translate market growth into practical demand drivers (e.g., replacement cycles for aerosol cans, color differentiation strategies, and the increasing crossover between traditional occlusion sprays and digital scan-compatible products) so revenue forecasts can be linked to SKU-level commercialization plans.
-
Regulatory roadmap: We map the regulatory landscape and compliance implications for intraoral and non-intraoral formulations — a critical filter for product development pipelines and go-to-market timing.
-
Competitive economics: Through an assessment of concentration metrics and competitor archetypes, the report helps prioritize where to invest in brand, distribution, or innovation to capture disproportionate returns.
Report Contents — Practical, Transactional, and Actionable
The report is organized to support immediate planning cycles and mid-term strategy. Key modules include:
-
Market sizing and forward-looking scenarios: A transparent modeling workbook covering historical (2020–2025) and forecast (2026–2032) revenue, with sensitivity testing for demand shocks and pricing moves.
-
Segment taxonomy and demand drivers: A structured segmentation by geography, product type (color and formulation variants), and end-use (clinical, laboratory, and industrial scanning). The brief summarizes the structural drivers for each segment while reserving full split tables for the full report.
-
Competitive landscape and capability benchmarking: A pragmatic view of incumbent strengths, product differentiation, channel reach, and technical IP where applicable.
-
Regulatory and standards appendix: Collated public regulatory facts, medical device classification implications, and suggested compliance timelines for intraoral approvals in major markets.
-
Commercial playbooks: Go-to-market blueprints for premiumization, value-pack SKUs, strategic distribution partnerships, and digital-scan product positioning.
-
M&A screening framework: A toolset for identifying targets that would materially improve scale, channel access, or technical capabilities — with integration risk checklists.
Competitive Landscape — Profiles and Strategic Implications
The occlusion spray market is characterized by a mix of specialist dental suppliers and broader dental consumable firms. Market concentration is meaningful but not dominant: the top three players account for a substantial portion of market revenue, while the top five increase that share further, indicating material advantages for scale and channel coverage without creating insurmountable entry barriers.
-
Pascal International, Inc. (Bellevue, WA, USA) — Pascal’s Occlude aerosol indicator positions it around intraoral applicability and precision marking. Its intraoral-approved profile is a competitive differentiator for firms targeting clinician-focused channels and premium pricing.
-
Bausch (Dr. Jean Bausch GmbH & Co. KG, Cologne, Germany) — Bausch’s Arti-Spray family emphasizes multi-color options and a thin removable film, which is attractive to labs and practices prioritizing ease of removal and multi-color workflows. Compliance with European device directives in their product messaging supports trust in regulated markets.
-
Renfert GmbH (Hilzingen, Germany) — With targeted offerings that highlight clear marking for model castings and prosthetic work, Renfert is well-placed in lab-centric workflows and among prosthodontic specialists.
-
YETI Dentalprodukte GmbH (Engen, Germany) — YETI’s water-soluble formulations and emphasis on adhesion across substrates make it a practical choice in lab environments where cross-surface compatibility matters.
-
DFS Diamon GmbH (Riedenburg, Germany) — Products designed to be insoluble in common cleaning media provide a differentiated option when model stability and coloration longevity are priorities.
-
Vacalon and Indenco Dental Products (USA) — These companies compete on broad accessibility, a range of pack sizes, and positioning that bridges traditional occlusion marking and digital scan pre-processing.
Implication for 2026: competitors are differentiating along formulation (water-soluble vs. insoluble), color portfolio, regulatory approval status, and pack-size economics. Any new entrant or incumbent seeking growth should map investments against at least two of these levers to create defensible advantages.
Regulatory and Operational Dynamics
Regulatory clarity is a strategic accelerant in this market. Several products in the category are cleared for intraoral use under applicable guidance in major markets — a significant commercial advantage in clinician channels. Similarly, compliance with European medical device directives remains a persuasive trust signal in EMEA. From an operational standpoint, the sector’s reliance on standardized aerosol packaging creates predictable procurement and logistics patterns; common can sizes and propellant considerations simplify supply chain optimization but also create vulnerability to commodity input pricing and shipping constraints.
-
Regulatory note: Products with intraoral approvals unlock a different set of distribution channels, marketing claims, and pricing power.
-
Packaging and SKU economics: Typical aerosol formats and a small set of color variants mean that portfolio optimization can quickly drive margin improvements through SKU rationalization and multi-pack offerings.
-
Digital-scan convergence: Several suppliers promote formulations that also function as digital scan sprays. This dual-use trend opens cross-sell opportunities into industrial scanning workflows and newer digital dentistry toolchains.
Strategic Playbook — Recommendations for 2026
Based on our modeling and competitive analysis, portfolio and channel choices in 2026 should be guided by three priorities:
-
Prioritize regulatory-aligned SKUs for clinician channels. If intraoral approval is not yet in place, accelerate compliance programs for key markets where clinicians drive unit volume and premium pricing.
-
Rationalize SKUs around core color/formulation combinations that align with high-margin channels (e.g., prosthetics labs, premium clinics), while offering value packs for high-volume, price-sensitive buyers.
-
Pursue targeted partnerships or tuck-in acquisitions that add lab-centric capabilities, digital-scan compatibility, or distribution reach in underpenetrated geographies. Given current concentration metrics, well-chosen bolt-ons can materially improve scale without triggering excessive integration complexity.
Risk Factors and Mitigants
Three risk clusters should be actively managed when setting 2026 plans:
-
Regulatory shifts — Changes in device classification or ingredient restrictions can disrupt timelines. Mitigation: proactive regulatory engagement and conservative launch assumptions.
-
Commodity and packaging input volatility — Aerosol propellants and can production may experience price or capacity pressure. Mitigation: diversify suppliers and evaluate multi-pack economics.
-
Channel substitution risk — Adoption of alternative digital-marking technologies could compress demand for certain spray types. Mitigation: invest selectively in dual-use formulations and partnerships with digital scanning vendors.
Conclusion — The Strategic Value of the Full Report
PW Consulting’s Worldwide Occlusion Spray Market brief delivers the practical intelligence necessary to convert a 5.28% market CAGR into executable 2026 strategies. The full report contains the detailed segmentation tables, SKU-level demand levers, and valuation-ready M&A screening tools that boards and strategy teams require. This preview surfaces the levers — regulatory position, formulation differentiation, and channel economics — and the competitive landscape dynamics that will determine who captures disproportionate returns during the next planning cycle.
For companies planning budget allocations, product launches, or M&A activity in 2026, the full report provides the granular inputs and scenario models needed to make high-confidence decisions. Access to the complete dataset, including detailed segment splits and a downloadable modeling workbook, is available on the PW Consulting portal.
For detailed analysis of this topic, please visit the official page: Worldwide Occlusion Spray Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCM Metal Sheet Market Projected to Grow at a 5.15% CAGR Through 2032, Driven by Strong Asia‑Pacific Demand
By pmarketresearch, 2026-08-12
PCM Metal Sheet Market — Strategic Outlook for 2026: A PW Consulting Brief
As demand patterns settle after a period of near-term volatility, pre‑coated metal (PCM) sheet markets move from short‑term recovery into a structurally evolving phase. PW Consulting’s new market research — based on a 2020–2025 historical baseline and a 2026–2032 forecast horizon — quantifies that transition and translates it into executable choices for suppliers, OEMs, and strategic investors heading into 2026. The market registered robust scale in the base year (2025) and our scenario-led projections assume a steady compound annual growth rate (CAGR) of 5.15% through the forecast window, providing a pragmatic reference for capital planning, product roadmaps, and commercial strategies.
Hollow Fiber Bioreactors Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is the inflection year where capital deployment, product launches, and supplier rearrangements planned in 2024–25 will either compound value or expose execution risk. Our analysis pinpoints the commercial and operational levers that determine the outcome.
Single-stage Reverse Osmosis Filtration Systems Market -
Macro-to-micro translation: PW Consulting bridges headline growth with granular, actionable levers — manufacturing throughput, substrate selection, coating chemistry choices, and certification pathways — so leaders can move from “market knows” to “we do.”
Lathe CNC Device Market -
Risk calibration: With upstream cost pressure and regulatory tightening, the report provides scenario-based sensitivity matrices for margin, inventory, and working capital that are immediately usable in 2026 budgeting cycles.
Executive synthesis — what the numbers mean strategically
The PCM market’s compound growth projection (CAGR: 5.15% over the forecast period) is neither hyper‑growth nor contractionary; it is characteristic of a mature industrial material that is re‑differentiating through value‑added coatings, functional additives (e.g., antimicrobial, anti‑scratch), and integrated supply partnerships with appliances and construction OEMs. For corporate strategists, the implication is clear: volume growth will come from targeted application innovation and supply efficiency rather than broad‑based market expansion. That creates an opening for differentiated players and vertically integrated groups to extract premium returns through technology, brand, and logistical excellence.
Practical intelligence in the report (operationally focused)
-
Cost and margin playbooks: detailed models map the sensitivity of finished‑sheet margins to CRC/HRC differentials, zinc coating choices, and coil‑processing yields. These allow procurement teams to stress‑test supplier quotes and to quantify the break‑even for passing raw material inflation downstream.
-
Coating strategy templates: comparative frameworks evaluate polymer systems, film‑lamination versus liquid coating, and performance tradeoffs (corrosion resistance, color fidelity, formability). These are tailored to appliance, building, and transport use cases with implementation checklists for pilot lines.
-
CAPEX scheduling and utilization scenarios: a production planner’s toolset for 2026 prioritizes which lines to upgrade, retrofit, or mothball under three demand scenarios; ROI gates include time‑to‑market for new color sets and certifications.
-
Commercial go‑to‑market blueprints: contract structuring and service SLAs are described for long‑term offtake arrangements with major OEMs, including packaging, Q‑control processes, and returns management that protect price realization.
-
Supply‑chain stress test: recommendations for buffer sizing, inventory segmentation, and strategic dual‑sourcing to harden supply continuity against upstream coil price swings and logistics disruptions.
Industry dynamics impacting 2026 strategies
-
Upstream pricing: material dynamics are non‑trivial — cold‑rolled coil (CRC) commands a meaningful premium relative to hot‑rolled coil (HRC) due to the extra processing required for PCM substrates. In parallel, benchmark HRC indices have shown recent month‑over‑month movement that directly affects base costs for PCM producers. Firms that ignore these spreads risk margin erosion; those that proactively reconfigure buying and hedging can protect or even improve gross margins.
-
Standards and certifications: compliance pathways (ISO 9001, RoHS, plus third‑party testing by SGS/BV/Intertek) are table stakes. The report includes a compliance ladder showing how incremental certification investments translate into price premium bands and preferred supplier status with global OEMs.
-
Product differentiation: coating technology, extended warranties (e.g., long‑term corrosion resistance), and color stability are where PCM suppliers can create defensible value. We identify which functional claims carry the most commercial leverage in appliance and building verticals and offer a prioritization matrix for R&D budgets.
Competitive landscape — positioning and strategic implications
The PCM sector is moderately concentrated: the three largest players capture material market share, and the top five firms further increase that concentration. This structure creates both constraint and opportunity. Dominant global steelmakers and integrated coated‑steel providers enjoy scale, supply security, and sales channels into construction and appliances; at the same time, regional specialists and high‑performance niche players capitalize on agility, speed to market, and customization.
-
Global integrated suppliers (examples include long‑established steel majors): advantage lies in upstream integration, broad substrate portfolios, and large coil‑coating capacity. Their strategic playbooks in 2026 will focus on margin protection through improved coating yields, selective premiumization of product lines, and long‑term OEM contracts.
-
Regional and specialty producers (examples include targeted PCM manufacturers and coil‑coaters): these firms compete on customization, color matching precision, and after‑sales support. Recent public disclosures show product claims such as high salt‑spray resistance, tight ΔE color tolerances, and ISO processes — all translatable into differentiated commercial offers for appliance brands and façade specialists.
-
Manufacturing service providers: independent coil centers and contract coaters will be critical to service OEM decentralization strategies, allowing appliance makers to localize supply without re‑investing in full‑scale upstream capacity.
Recent corporate moves and what they signal for 2026
-
Operational commitments and community engagement by regional manufacturers underscore a twofold priority: ensure stable throughput and maintain social license. Visibility into factory activity and local stakeholder engagement matters more for permitting and workforce stability than in prior cycles.
-
Performance claims from niche exporters — such as extended salt spray records and precision color matching — indicate that product quality is a growing gatekeeper for access to higher‑margin appliance programs. Buyers in 2026 will increasingly validate these claims via independent labs as a procurement precondition.
-
Catalog and product documentation refreshes from leading suppliers show an acceleration in portfolio modularity — more SKUs with shorter lead times — which, if matched by production flexibility, will pressure traditional lead‑time premia.
Strategic recommendations for 2026 decision‑makers
-
Procurement and pricing: institute a two‑track raw material strategy — tactical hedges for the near term and strategic long‑term offtake agreements with selected upstream partners. Model exposures against CRC/HRC spreads and set dynamic pass‑through clauses to preserve margins.
-
Product strategy: prioritize coatings that deliver measurable, verifiable performance attributes (e.g., salt spray, color delta, formability) aligned to targeted OEM specs. Short‑cycle pilot programs that include third‑party validation reduce commercial risk and accelerate adoption.
-
Capacity and CAPEX: condition incremental capacity investments on utilization improvement programs and modular upgrades rather than greenfield expansion. Retrofits that improve coating line efficiency and reduce rejects often yield faster paybacks than new lines.
-
Commercial structuring: adopt blended contract models that combine take‑or‑pay volumes with quality‑linked premiums to align incentives with OEMs, particularly for localized supply arrangements.
-
M&A and partnerships: look for bolt‑on acquisitions that add coating chemistries, color matching capabilities, or regional service centers. Strategic minority stakes with technology licensors can secure access to next‑generation functional coatings without full-scale acquisition risk.
Where the report draws the line — and why you should get the full study
This release is designed as a strategic primer: it demonstrates the analytic rigor and operationally relevant outputs that PW Consulting delivers, while preserving the proprietary granularity that clients rely on to make competitive moves. The full report contains the complete set of segment tables, granular regional and application breakdowns, company scorecards, supplier negotiation playbooks, and model‑ready datasets — elements we intentionally omitted here to ensure clients access the decisive details via the report package.
How to use the report in your 2026 planning cadence
-
Board briefing: use the executive slidepack to align the board on near‑term market exposures and the targeted premium segments that justify investment.
-
Budget cycles: integrate our sensitivity matrices into Q1 and mid‑year reviews to recalibrate CAPEX and working capital based on realized price paths.
-
Commercial pilots: deploy the product and coating selection templates in 60–90 day pilots with selected OEM customers to accelerate qualification and lock in early production slots.
PW Consulting’s PCM Metal Sheet Market research is built for action: it speaks to what to do, when to do it, and how to measure decision outcomes. For teams preparing budgets, negotiation strategies, or R&D roadmaps in 2026, the study converts market growth and concentration dynamics into executable, defensible plans. For full access to the proprietary segment datasets, supplier scorecards, and downloadable models that underpin these recommendations, please visit our report page or contact PW Consulting to arrange a briefing.
For detailed analysis of this topic, please visit the official page: PCM Metal Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide AI Learning Machine Market Set to Surge at 21.08% CAGR, New Insights Report Finds
By pmarketresearch, 2026-08-12
Worldwide AI Learning Machine Market: Strategic Imperatives for Enterprise Decision‑Makers in 2026
As organizations plan technology investments and education providers rethink delivery models for the coming five years, PW Consulting’s new Worldwide AI Learning Machine Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—provides an evidence‑based roadmap for executives, procurement leads, and policy teams. The global market has moved from niche experimentation to mainstream adoption: between 2020 and 2025 the market expanded rapidly, and our modeling projects continued acceleration in 2026 and beyond, driven by converging forces in hardware improvements, model availability, regulatory nudges, and shifts in learning models. Our forecast uses a 21.08% compound annual growth rate and projects a multi‑billion dollar opportunity by 2032 under the baseline scenario.
Phosphate Analyzer Market
Why this report matters for 2026 strategic decisions
-
Timing: 2026 is a pivotal year when several macro and regulatory inflection points collide—new national AI standards, classroom AI literacy mandates, and the first wave of content‑native partnerships. These create windows where early movers can lock in distribution, content, and data partnerships while mitigating regulatory friction.
Worldwide Punch & Die Storage Cabinet Market -
Procurement clarity: Procurement teams are facing unfamiliar product classes—integrated tablets, stationary learning devices with embedded models, and hybrid robotic bases. Our report supplies a vendor evaluation matrix, TCO templates, and procurement clauses aligned to emerging compliance standards so teams can move from vendor demos to defensible purchase decisions.
Educational Monocular Microscopes Market -
Risk control: The landscape blends consumer hardware practices with sensitive learner data. We model regulatory exposure under multiple enforcement intensities and provide mitigation playbooks (data minimization, on‑device processing thresholds, and third‑party audit clauses) for 2026 rollouts.
-
Value capture: For product and business leads the report outlines monetization archetypes—hardware subsidization through content licensing, subscription learning services, and institutional procurement—highlighting levers that most influence unit economics and churn over a three‑year horizon.
What’s in the report: practical, executable content
-
Market sizing and scenario forecasts: detailed baseline, upside and downside trajectories through 2032 using bottom‑up demand drivers and supplier capacity constraints.
-
Vendor scorecards: side‑by‑side assessments covering product maturity, model strategy (on‑device vs. cloud), content ecosystems, pricing architecture, support footprint, and compliance posture.
-
Implementation playbooks: step‑by‑step guides for pilots, rollouts, and scale, including change management templates for teachers and IT, interoperability checklists, and classroom acceptance metrics.
-
Procurement and contracting toolkit: RFP language, SLA constructs for model performance, data usage clauses, and sample budget scenarios that translate strategic aims into line‑item budgets.
-
Regulatory and security frameworks: mapping of national standards and generative AI safety requirements, recommended audit regimes, and incident response flows tailored to learning devices.
-
Competitive and partnership playbook: go‑to‑market options mapped for hardware OEMs, content owners, and systems integrators, plus templates for licensing and co‑development agreements.
Market dynamics: drivers, headwinds and critical inflection points
Three structural forces shape the market through 2026:
-
Demand pull from constrained traditional tutoring channels: Policy changes reducing offline tutoring have accelerated at‑home educational technology adoption, creating demand for compliant, structured AI learning devices.
-
Supply side differentiation via content and models: Companies that pair proprietary large models and curated content ecosystems achieve stronger retention and higher willingness to pay. Content exclusivity deals becoming visible in 2026 exemplify this dynamic.
-
Hardware and compute constraints: Export controls on advanced semiconductors and manufacturing equipment constrain high‑performance on‑device compute for some vendors, increasing the relevance of hybrid cloud designs and optimized model architectures.
These forces do not operate uniformly. Regulatory clarity in some markets is increasing (with standards addressing ML algorithm security and generative AI safety), while others remain fragmented. Our technical risk assessment and compliance map in the report helps enterprises match product specifications to jurisdictional requirements before deployment.
Competitive landscape: who’s shaping the market now
The sector is a mix of established education incumbents, consumer electronics firms, and AI platform players. Market concentration is meaningful but far from monopolistic: the top three firms capture a notable portion of global value while the top five expand that reach further—an important context for partnership or acquisition strategies.
-
iFLYTEK (Hefei, China): A leader in integrating cognitive large models into dedicated learning devices, focused on personalized K‑12 tutoring, voice interaction, and homework assistance. In 2025 the company reported a material revenue acceleration in its smart education segment, and in January 2026 iFLYTEK announced an exclusive content partnership that expands its English learning portfolio—an example of how content deals are being used to differentiate hardware offers.
-
Yuanfudao / Xiaoyuan (Beijing, China): Known for tablet + intelligent base designs that blend diagnostic capabilities and emotional interaction. Their 2025 product generation positions them strongly for companion‑style deployments and highlights the strategic value of hardware innovations that enable novel learning interactions.
-
Zuoyebang (Beijing, China): Focused on AI tutoring, homework assistance, and companion features for younger learners. Their product strategy underscores the ongoing shift from single‑purpose devices to multifunctional learning ecosystems.
-
TAL Education Group (Xueda / Xueersi): Brings deep curriculum design and brand trust to learning devices, leveraging large models for adaptive learning and integration with classroom offerings.
-
BBK, Readboy, Xiaodu (Baidu): Represent a spectrum from consumer OEMs emphasizing hardware ergonomics and screen safety to platform players folding educational features into broader smart hardware portfolios.
For buyers, the implication is clear: evaluate suppliers not just on hardware specs but on content partnerships, model governance, and supply chain resilience. Our vendor selection framework assigns weights to these dimensions based on deployment objectives (institutional vs. consumer vs. hybrid).
Regulatory and operational risks enterprises must plan for in 2026
-
Standards and AI safety: New national standards for ML algorithm security and generative AI safety are moving from guidance to enforceable regimes. Compliance will need to be demonstrable—log retention, model provenance, and content review processes are increasingly table stakes.
-
Curriculum mandates: Several jurisdictions are integrating AI literacy into core instruction. Devices will need to support curriculum alignment and teacher enablement features rather than merely delivering content.
-
Supply chain and compute access: Geopolitical controls on advanced semiconductors impact on‑device inference capabilities and may force architectural tradeoffs that affect latency, privacy, and cost.
-
Content safety and platform governance: Group standards and vendor self‑regulation around content filtering (for example, controls to block gaming content) are emerging. Institutional buyers should insist on auditability and transparent moderation rules.
How to use the report in boardroom conversations
-
Investment committees: Use our three scenario forecasts to stress‑test capital allocations and estimate the payback period for hardware pilots under varying adoption rates and content monetization models.
-
Procurement teams: Adopt the RFP language and SLA templates to reduce procurement cycle time and reduce downstream compliance risk.
-
Product and partnerships: The vendor scorecards and partnership playbooks provide practical starting points for licensing negotiations and co‑development agreements, including guardrails for data usage and IP sharing.
-
Policy and legal teams: Leverage the regulatory map and incident response flows to craft institutional policies around student data, content safety, and audit requirements.
What we intentionally leave out here—and why
To preserve the strategic value of the full report and support informed procurement and investment flows, we have summarized macro trends and firm‑level dynamics in this announcement but withheld granular segmentation disclosures (region‑by‑region shares, product‑type and end‑user monetary splits and other detailed tables). The report contains those specifics, including downloadable datasets, interactive scenario tools, and country‑level sensitivity analysis that are essential for transaction‑level decision making. This “preview” approach is intentional: we provide enough rigor to enable initial prioritization while directing decision‑makers to the full materials for deal execution and contract drafting.
Next steps for clients
-
Commission a tailored briefing: We offer bespoke briefings that map our findings into client‑specific impact assessments—covering procurement timing, pilot site selection, and 18‑month roadmaps.
-
Request the deep‑dive dataset: Institutional subscribers may access the underlying segment models, concentration tables, and vendor benchmarks to drive RFPs and board materials.
-
Engage our implementation practice: For organizations ready to pilot in 2026, PW Consulting provides an end‑to‑end service from site readiness assessment to teacher enablement and post‑pilot evaluation.
In short, the AI learning machine market is moving from exploratory pilots to commercially meaningful deployments. Firms that align technology architecture, content strategy, and regulatory hygiene in 2026 will secure outsized advantages over the following five years. PW Consulting’s Worldwide AI Learning Machine Market report equips leaders with the analytic foundation and practical tools needed to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide AI Learning Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Robotic Scope Holder Market to Grow from USD 310.0 Million in 2025 to USD 514.3 Million by 2032 at a 7.5% CAGR — Autonomous Holders Lead the Market
By pmarketresearch, 2026-08-12
Worldwide Robotic Scope Holder Market — Strategic Imperatives for 2026
As surgical suites continue their steady transition toward hybridized robotic workflows, hospital procurement teams, device OEMs, and financial sponsors face a narrow window in 2026 to translate technical opportunity into defensible commercial positions. PW Consulting’s latest Worldwide Robotic Scope Holder Market report (base year: 2025; historical coverage: 2020–2025; forecast horizon: 2026–2032) synthesizes primary interviews, device-level testing, and quantitative market modeling to pinpoint where resources should flow next. The global market reached approximately USD 310 Million in 2025 and — under our central-case assumptions (CAGR: 7.5% for 2026–2032) — is forecast to exceed USD 500 Million by the end of the forecast period. This briefing highlights the report’s strategic value for 2026 decision-making while preserving high-resolution datasets and segment tables for subscribers.
Worldwide Biopotential Sensors Market
Executive snapshot: Why 2026 matters
-
Commercial inflection: Adoption of scope-holding systems is moving from proof-of-concept deployments to enterprise procurement cycles — 2026 is the year many health systems will commit to platform-level integrations.
Worldwide Mobile Backend Services Market -
Technology consolidation: Voice control, AI-assisted positioning, and native compatibility with leading surgical robots are emerging as table stakes rather than premium differentiators.
Worldwide Urgent Care EMR Software Market -
Regulatory and reimbursement clarity: Electrical safety and device classification standards and emerging reimbursement pathways materially reduce adoption friction — but manufacturers must build dossiers now to benefit from near-term CPT and clearance windows.
Key market dynamics and implications
-
Demand drivers — Workflow automation and labor optimization: Hospitals are prioritizing devices that reduce reliance on manual camera control, shorten procedure times, and improve OR staffing efficiency. Buyers evaluate total cost of ownership (TCO) across device purchase, service agreements, and sterilization/consumable cycles.
-
Technology vectors — Integration, control modalities, and intelligence: Systems offering multi-modal control (voice activation, surgeon-controlled joysticks, and autonomous hold modes) and seamless integration with robotic platforms unlock the highest willingness-to-pay. Recent product updates emphasize AI-assisted positioning and platform interoperability as key differentiators.
-
Regulatory and reimbursement context: Devices in this class must satisfy IEC 60601-1 electrical safety requirements in the OR and generally follow Class II regulatory pathways (510(k) in the U.S.). CPT code 20985 and related reimbursement guidance increasingly cover computer-assisted scope positioning in laparoscopic workflows, improving the procedural economics case for purchasers.
-
Materials and sterilization: Medical-grade stainless steels and titanium alloys remain the materials of choice; designs are validated for autoclave sterilization up to typical industry temperatures. Procurement teams should require sterilization validation and lifecycle cost modeling as part of acquisition evaluations.
-
Market structure: The market exhibits meaningful concentration among a small number of established medical-device firms. The top three players account for the majority share, while the broader top-five captures a high proportion of market value — a dynamic that favors strategic partnerships, white-label agreements, and selective M&A for challengers seeking rapid scale.
Competitive landscape — what the major players signal
-
Mitaka Kohki (Tokyo): Known for multi-axis manipulators with sophisticated voice control and deep integration paths toward robotic-assisted platforms. Recent product updates emphasize AI-assisted positioning for robotic-assisted surgeries — a move that accelerates their relevance in dual-robot ORs.
-
FreeHand Surgical (London): A focused innovator in voice-activated endoscope holders; regulatory clearances and active presence at surgical society conferences make them a partner of choice for early adopter hospitals and specialty clinics exploring hybrid workflows.
-
EndoControl (now part of Medtronic): As an acquired technology within a major OEM, the ViKY asset benefits from scale in distribution and post-market support. Regulatory milestones expanding device compatibility with next-generation endoscopes strengthen its system-level value proposition.
-
Olympus (Tokyo): Brings platform-level optics, imaging stacks, and robotic positioning systems to the table. Integration of scope holders into established surgical imaging ecosystems supports bundled purchasing strategies and lock-in opportunities for health systems.
Strategic takeaways: incumbents are pushing both product-scope (platform integration, AI-assisted positioning) and go-to-market depth (channel partnerships, regulatory clearances). Challengers should target niche clinical workflows and interoperability wins, while buyers should weigh platform compatibility and service economics over nominal device cost.
Actionable 2026 playbook by stakeholder
-
For manufacturers and R&D leads:
-
Prioritize modular interoperability with leading robotic platforms and imaging stacks to shorten procurement cycles.
-
Invest in AI-assisted positioning and robust voice-control fail-safes to reduce cognitive load on the surgeon and improve adoption rates.
-
Lock down supplier agreements for medical-grade alloys and validated sterilization processes to shorten time-to-market and lower recall risk.
-
-
For hospital system executives and procurement:
-
Run total-cost-of-ownership pilots that include OR time-savings, anesthesia throughput effects, and staff redeployment benefits rather than comparing device price alone.
-
Request vendor evidence of IEC 60601-1 compliance, 510(k) clearance where applicable, and explicit sterilization-cycle validation.
-
Structure procurement contracts to include data-sharing clauses and interoperability milestones — these accelerate clinical ROI and protect against obsolescence.
-
-
For investors and strategic acquirers:
-
Given the market’s concentration dynamics, prioritize targets that offer either unique clinical differentiation (e.g., advanced autonomy in complex laparoscopic workflows) or distribution synergies with larger OEMs.
-
Use staged earn-outs tied to regulatory clearances and integration milestones to bridge valuation gaps for early-stage innovators.
-
What the PW Consulting report delivers (operational detail)
-
Market model and forecasts: Annualized revenue model across 2020–2032 with scenario-driven sensitivity (central, upside, downside) and explicit assumptions supporting a 7.5% CAGR for the forecast period.
-
Segmentation and adoption mapping: Regional, product-type, and surgical-application frameworks with demand drivers, price-elasticity matrices, and adoption curves. (Note: high-granularity segment tables and downloadable datasets are available in the full report.)
-
Regulatory and reimbursement playbooks: Step-by-step 510(k)/CE pathway mapping, IEC compliance checklists, and a reimbursement dossier template that aligns clinical claims with CPT code 20985 and analogous codes in major markets.
-
Vendor scorecards and supplier risk assessments: Comparative benchmarking across product performance, integration readiness, service networks, and component supply-chain risk.
-
Commercialization and M&A playbooks: Go-to-market roadmaps for incumbents and challengers, pricing and service models, and an M&A target shortlist with preliminary synergy estimates and integration risks.
-
Primary research and validation: Surgeon and clinical engineering interviews, OR workflow time-and-motion studies, and bench-testing of electromechanical and sterilization durability under clinical-use cycles.
Methodology and modeling transparency
-
Base and historical years: 2025 base year with historical analysis covering 2020–2025.
-
Forecast window: 2026–2032 with a central CAGR assumption of 7.5%. Forecast sensitivity isolates impacts from three variables: (1) rate of surgical-robot penetration, (2) pace of AI-assisted feature adoption, and (3) changes in reimbursement coding.
-
Data sources: Combination of primary interviews, device-level technical testing, regulatory databases, and proprietary pricing and tender intelligence. All assumptions and raw inputs are documented for client review.
Risks, blind spots, and watch items for 2026
-
Regulatory shifts: Any tightening of device classification or new electrical safety requirements would increase time-to-market and development cost. Conversely, streamlined clearances for integrated systems could accelerate adoption.
-
Reimbursement volatility: While CPT 20985 creates a pathway, payer uptake varies by market and can be subject to local coverage determinations. Real-world evidence is the decisive factor for permanent coverage.
-
Interoperability fragmentation: Proprietary integrations by large OEMs could create walled gardens; smaller vendors must prioritize open APIs and standards compliance to remain viable partners.
Conclusion — the strategic imperative for 2026 is clear: organizations that align product development with platform-level interoperability, secure regulatory and reimbursement pathways now, and structure commercial agreements around outcomes will capture disproportionate share as the market expands from its 2025 base toward the half-billion-dollar range at the end of the forecast window. PW Consulting’s Worldwide Robotic Scope Holder Market report provides the decision-grade intelligence, playbooks, and datasets needed to make those calls with confidence.
To access the full datasets, segmentation tables, vendor scorecards, and commercial templates referenced in this briefing, please visit the PW Consulting report page for the Worldwide Robotic Scope Holder Market. Our analysts are available for briefing sessions and bespoke scenario modeling to support your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Robotic Scope Holder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Optoelectronic Safety Laser Scanner Market to Reach USD 949.45 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Optoelectronic Safety Laser Scanner Market — A Strategic Brief for 2026 Decision‑Makers
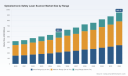
PW Consulting’s new market brief on the Worldwide Optoelectronic Safety Laser Scanner market provides an executive-ready synthesis designed to inform capital allocation, product roadmaps, supply‑chain strategies, and M&A decisions through 2026 and beyond. Anchored on a 2025 base year and a 2026–2032 forecast window, the dataset shows the market continuing on a steady growth trajectory (CAGR 7.15% for the forecast period). After rising from a resilient USD 420.4 million in 2020 to USD 585.5 million in 2025, the market is modeled to exceed USD 629.9 million in 2026 and approach roughly USD 949.4 million by 2032. These macro dynamics make 2026 a pivotal planning year: organisations that translate these trends into operational and commercial moves will capture disproportionate share of the next growth cycle.
Worldwide DEET Repellents Market
Why this report matters in 2026
- Actionable timing: 2026 is the inflection point between early adoption of mobile/outdoor safety sensing and broad enterprise rollouts. Procurement windows, standards updates and product cycles converge this year—creating both risk and opportunity.
- Risk mitigation: Supply‑chain fragility in upstream compound semiconductors requires immediate sourcing and inventory decisions to sustain production plans into 2027–2028.
- Technology selection: The emergence of certified 3D safety LiDAR and increasingly modular 2D scanners forces product strategy tradeoffs between cost, integration footprint and safety performance.
- Competitive positioning: Market concentration is meaningful—top three vendors capture a majority share while top five push that dominance further—making partnership and go‑to‑market moves high‑leverage choices.
What PW Consulting’s brief delivers (practical, deployable content)
- Executive summary with scenario‑mapped market trajectories (base, upside, downside) tied to clear decision triggers for procurement, R&D and M&A.
- Vendor playbooks and competitive scorecards that synthesise product attributes, certified safety levels, integration protocols and after‑sales economics.
- Supply‑chain stress tests and a component risk matrix (laser diodes, compound wafers, optical coatings) with recommended hedging strategies and contract templates.
- Regulatory alignment guides mapping IEC/ISO requirements and the implications of the EN ISO 13855:2024 revision for installation and safety distance calculations.
- Field deployment templates (AGV/AMR, machine guarding, outdoor mobile applications) including integration checklists, commissioning KPIs and cost‑of‑ownership models.
- M&A and partnership screening toolkit to prioritise targets by technology gap, addressable market and integration complexity.
Market dynamics shaping 2026 strategy
Three structural forces will determine winners and losers in the year ahead:
Worldwide Prescription Writing Software Market
- Product evolution: Vendors are migrating from strictly 2D safety scanners to hybrid portfolios that include certified 3D LiDAR. The practical result for OEMs and system integrators is a set of tradeoffs—3D units extend situational awareness and enable outdoor mobile applications but introduce new certification, integration and cost considerations.
- Supply‑chain concentration: Upstream supply is materially concentrated. Export restrictions and geopolitical policy shifts since 2023 have elongated lead times and pushed spot pricing higher for key inputs (in one observed instance, spot prices rose by ~40% following policy actions). In addition, a small set of suppliers controls the bulk of compound‑wafer capacity, creating non‑trivial single‑sourced risk for laser diode components.
- Standards and compliance: Standards remain the commercial gatekeepers. Safety laser scanners must satisfy IEC 61496, ISO 13849 and IEC 61508 family requirements, while the updated EN ISO 13855:2024 refines safe positioning rules and distance calculations—shifting installation practices and, by extension, product feature expectations for 2026 purchasers.
Competitive landscape — reading the rivals
The competitive field combines established industrial automation leaders with focused safety specialists. Our brief provides distilled strategic assessments for each major player to guide sourcing and alliance choices:
Worldwide Machine Learning in Finance Market
- SICK AG (Waldkirch, Germany): A broad portfolio across 2D safety scanners and a recent move into safety‑certified 3D LiDAR positions SICK as a technology leader for outdoor mobile applications and high‑integrity safety systems. Their multiScan100‑S launch signals an offensive into collision‑avoidance applications.
- Leuze electronic (Owen, Germany): Differentiates on compact form‑factor and tight‑space integration—products targeted at AGVs/AMRs and constrained machine envelopes. Expect Leuze to be the partner of choice where footprint and rapid integration matter most.
- Pilz (Ostfildern, Germany): Known for rigorous standards alignment and system engineering tools; recent Profinet integration reduces friction for industrial networked installations and eases diagnostics during commissioning.
- KEYENCE, OMRON, Banner Engineering, Rockwell Automation (Allen‑Bradley): Each brings strong system and network integration capabilities, with different strengths—ranging from extended detection ranges and environmental resistance (KEYENCE) to deep factory automation channel reach (Rockwell).
- European specialists and niche players (Pepperl+Fuchs, Reer, Datasensing, Fiessler, Turck, Hokuyo, IDEC): Often compete on tailored solutions, regional service models and price‑performance for standard machine safety roles.
Implications for sourcing, product and M&A strategy
- Secure dual sourcing for critical laser diodes and wafers. Where possible, obtain contractual cadence and price‑indexing clauses now; lead‑time extensions observed in recent years demand longer procurement cycles.
- Prioritise modularity. Design product families that allow field upgradable sensing subsets—2D for constrained budgets, optional 3D modules for premium mobile use cases—to manage product complexity while capturing upsell opportunities.
- Embed standards expertise into sales and integration processes. The EN ISO 13855:2024 changes are not cosmetic; they reshuffle the cost and time required for installations. Vendors and integrators who translate standards into rapid, auditable commissioning processes will outcompete peers.
- Evaluate bolt‑on tech acquisitions that close immediate capability gaps (e.g., multi‑echo LiDAR signal processing, IP69K‑rated housings, integrated camera + safety fusion) rather than greenfield R&D expansions.
Scenario planning — decision triggers and KPIs for 2026
- Base case (CAGR ~7.15%): Gradual migration to hybrid 2D/3D portfolios. KPI triggers: orderbook growth, lead‑time variance, and adoption rates of certified 3D units in material outdoor applications.
- Upside case: Accelerated automation and safety retrofits drive above‑trend adoption. Strategic moves: scale manufacturing via contract fabs, prioritise channel incentives and accelerate service‑based monetisation.
- Downside case (supply shock): Semiconductor component squeeze compresses margins and elongates delivery windows. Defensive actions: reprice programs, shift to higher margin service agreements, and selectively allocate constrained inventory to strategic customers.
How to use this brief in your 2026 planning cycle
- Board and portfolio reviews: Use the macro market trajectory and concentration insights to stress test revenue targets and to prioritise investments across product lines.
- Procurement and operations: Adopt a six‑to‑nine month runway for critical semiconductor components and implement supplier scorecards mapped to geopolitical risk indices.
- Product and R&D leaders: Revisit platform architectures with an eye to safety certification roadmaps and network protocol support (e.g., PROFINET, CIP Safety, PROFIsafe) that shorten integration time at customer sites.
- Commercial and channel teams: Repackage offerings into outcome‑based bundles (sensing + commissioning + SLA) to defend margins amid component cost volatility.
Why PW Consulting’s dataset is strategic
Our brief is built from proprietary primary interviews, vendor disclosures, component‑level supply chain mapping and scenario modelling. We combine granular technical assessment (safety categories, certification paths, integration protocols) with commercial economics (pricing corridors, aftermarket revenue profiles) to produce recommendations you can operationalise in 2026. Importantly, while this overview synthesises the critical signals, the report itself contains the full segmentation matrices, interactive dashboards and downloadable vendor scorecards you will need to execute procurement, alliance and M&A plays—intentionally withheld here to preserve the targeted “trailer” that guides readers to the full intelligence package.
In a market moving toward certified 3D perception, higher integration expectations and a concentrated supply base, 2026 will reward organisations that align procurement, product development and channel strategy around resilience, modularity and standards proficiency. PW Consulting’s complete Worldwide Optoelectronic Safety Laser Scanner Market report offers the detailed data and playbooks to operationalise those choices. Visit our report page to access the full dataset, vendor scorecards and scenario models necessary to make high‑consequence decisions this year.
For detailed analysis of this topic, please visit the official page: Worldwide Optoelectronic Safety Laser Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aircraft Load Control Solutions Market Forecast to Reach USD 275.03 Million by 2032 at a 6.72% CAGR, Driven by Cloud-based Solutions and Passenger Airlines
By pmarketresearch, 2026-08-12
Worldwide Aircraft Load Control Solution Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
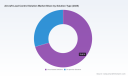
PW Consulting’s latest market intelligence report on the Worldwide Aircraft Load Control Solution market delivers an evidence‑based roadmap for executives making procurement, operational, and M&A decisions in 2026. The market, valued at USD 174.45 Million in our 2025 base year, is forecast to expand at a compound annual growth rate (CAGR) of 6.72% over the 2026–2032 forecast window, reaching USD 275.03 Million by 2032. This steady expansion reflects accelerating airline digitization, regulatory pressure for precision in weight & balance, and growing adoption of centralized load control models and cloud‑native architectures.
Worldwide Glass Hardware Market
Why this report matters for 2026
-
Timing: 2026 is a pivot year for fleet recovery, digital operations, and regulatory alignment. Operators that align load control investments with broader NextGen and airline IT modernization plans will capture disproportionate operational savings and risk reduction.
RC Plane Batteries Market -
Decision focus: Boards and COOs require a concise translation of market momentum into procurement strategy, vendor selection criteria, and value capture pathways. This report converts macro trends into executable options for 12–36 month programs.
Static Spray Ball Market -
Risk control: Given tightening oversight by ICAO, FAA, and EASA on load monitoring and data integrity, the strategic value of robust load control solutions now extends beyond efficiency into compliance and liability mitigation.
What the report contains — practical, actionable intelligence
-
Market sizing and trend analysis: A transparent time series (historical 2020–2025; base year 2025) and a 2026–2032 forecast that quantifies market scale and growth trajectory across solution models and delivery modes.
-
Use‑case driven segmentation: Operational archetypes and adoption roadmaps for passenger airlines, cargo operators, and ground handlers — with playbooks for centralized load control (CLC), station‑level operations, and hybrid models.
-
Vendor assessment framework: A practical RFP/RFX scorecard combining functional fit, integration readiness (flight planning, EFB, dispatch), regulatory compliance, uptime and disaster recovery, and total cost of ownership.
-
Implementation blueprints: Step‑by‑step migration plans for on‑premise to cloud migration, CLC consolidation, and phased automation that defend day‑of‑operations continuity.
-
Financial articulation: Payback scenarios and sensitivity analysis around fuel savings (EZFW optimization), ground handling throughput, and reduced disruption costs — modelled under conservative and aggressive adoption cases.
-
Competitive landscaping and M&A signals: Profiles of incumbent and emergent vendors, partnership archetypes, and strategic flags for consolidators and niche innovators.
-
Data & integration playbook: Data governance, validation checkpoints, and API patterns enabling near real‑time reconciliation with flight planning and aircraft systems.
Market dynamics shaping 2026 choices
-
Regulatory acceleration: Aviation authorities increasingly mandate precise, auditable weight & balance records and expect digital evidence of compliance. NextGen modernization programs and EASA/FAA certification pathways are pushing operators away from manual, ad‑hoc processes.
-
Operational economics: Fuel optimization and accurate zero fuel weight (EZFW) calculations are measurable levers to cut operating expense. Centralized Load Control (CLC) and automated loadsheet generation reduce error rates and gate delays, improving both safety and on‑time performance.
-
Technology shift: The market is migrating towards cloud‑enabled, API‑first solutions that support offline capabilities, mobile EFB integration, and automated load reconciliation. Buyers increasingly demand zero‑click or near‑zero manual interaction for routine loadsheet generation.
-
Service consolidation: Outsourced CLC providers are expanding footprint and scale economies. Recent provider disclosures illustrate how centralized centers support large numbers of airlines and process high volumes of load sheets annually — a factor that materially changes procurement calculus for mid‑sized carriers and ground handlers.
-
Concentration and competition: The industry exhibits moderate concentration — the top few vendors control a material share of the market. This creates a dual‑track environment where established players compete on integration breadth and service scale, while specialist vendors win on rapid innovation and niche functional superiority.
Competitive landscape — positioning and strategic reads
Our vendor mapping identifies three distinct strategic clusters: integrated airline systems vendors, specialist weight & balance solution providers, and centralized service operators. The market’s top three players collectively control roughly half of current market revenue, and the top five approach two‑thirds — a concentration profile that affects pricing leverage, partnership dynamics, and M&A opportunities.
-
Specialist W&B software firms (e.g., providers offering automated, visual exception‑based planning and high‑autonomy loadsheet generation) are winning adoption among carriers seeking quick operational uplift with minimal disruption.
-
Large airline IT vendors and flight‑ops integrators position load control as part of broader flight management and dispatch suites — an attractive option for airlines seeking a single‑vendor ecosystem but requiring careful evaluation of integration flexibility.
-
Centralized service operators leverage scale and geographic reach to offer CLC as a managed service — a compelling model for airlines and handlers that prioritize predictable OPEX and off‑platform risk transfer.
-
Notable developments illustrate these dynamics: a leading ground handler recently highlighted CLC centers in multiple countries supporting dozens of airlines and processing hundreds of thousands of load sheets annually — underscoring the operational and commercial value of scale.
Strategic recommendations for 2026
-
Adopt a two‑track procurement approach: For near‑term operational gains, select specialized, modular load control solutions with strong API and EFB support. For mid‑term strategic resilience, evaluate platforms that align with enterprise‑level flight operations suites.
-
Prioritize integration and data integrity over feature parity: The ability to reliably reconcile passenger and cargo data, integrate with flight planning and aircraft systems, and provide auditable trails for regulators will deliver outsized risk mitigation benefits.
-
Design CLC adoption as a business transformation: Treat Centralized Load Control not just as a systems replacement but as a re‑engineered operating model—align SLAs, uplift training per IATA designations, and embed governance for cross‑station consistency.
-
Validate cloud readiness and offline continuity: Insist on demonstrable offline capabilities and disaster recovery plans; ensure cloud migrations include a staged rollback and test program to protect day‑of‑operations.
-
Use vendor scorecards tied to measurable KPIs: Link procurement decisions to quantifiable targets such as loadsheet error reduction, gate dwell time improvements, and fuel savings recovered through tighter trim and load allocation.
-
Scan for M&A and partnership plays: Providers with differentiated automation, proprietary load automation logic, or strong CLC footprints are prime targets for strategic acquisition or partnership to accelerate capability build‑outs.
How to use this report in boardrooms and operational planning
-
Investment committees: Use the report’s financial scenarios to stress test capital outlays versus projected OPEX savings from automation and fuel optimization, and to set realistic payback windows.
-
CTOs and CIOs: Apply the integration playbook and vendor scorecard during RFP cycles to avoid costly rework and to ensure compliance and auditability are built into delivery contracts.
-
COOs and Ground Ops: Follow the implementation blueprints for phased CLC transitions that safeguard performance at hubs and remote stations while delivering immediate throughput and error‑reduction benefits.
-
Safety and Compliance teams: Leverage the regulatory mapping to prepare certification artifacts and to align training with internationally recognized IATA and regulatory standards.
Closing note — the value of granular intelligence
PW Consulting’s report delivers the granular insight that separates confident, fast‑moving adopters from reactive implementers. By combining a transparent market forecast (base year 2025, 2026–2032 outlook) with pragmatic procurement instruments, operational blueprints, and a surgical vendor evaluation framework, the study empowers leaders to convert the projected market growth trajectory into verifiable operational and financial outcomes.
For program leads preparing 2026 budgets, procurement windows, or M&A screening lists, the full report includes downloadable models, vendor due‑diligence templates, and regional adoption scenarios. To access the comprehensive datasets, segmentation analytics, and the complete competitive profiles that underpin these strategic recommendations, please consult the full PW Consulting market report.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Load Control Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market Poised to Surge at a 26.79% CAGR, Driving Rapid Biopharma Expansion
By pmarketresearch, 2026-08-12
Worldwide LAG‑3 Antibody Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
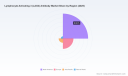
As LAG‑3 emerges from a research curiosity into a commercial immuno‑oncology axis, strategic clarity is accelerating from novelty to necessity. PW Consulting’s latest market study — the Worldwide Lymphocyte Activating 3 (LAG‑3) Antibody Market — translates five years of clinical momentum and commercial activity into an actionable decision framework for 2026. The market has expanded rapidly, from a modest USD 45.2 Million in 2020 to USD 1,320 Million in our 2025 base year. Our base‑case projection positions the market at approximately USD 1,770 Million in 2026 and growing at a 26.79% compound annual growth rate through 2032, reaching roughly USD 6,950 Million by the end of the forecast horizon. These headline dynamics set the stage — but the devil is in the operational detail that will determine winners and losers in the coming 18–36 months.
Worldwide Patient Experience Software Market
Why 2026 Is a Pivotal Decision Horizon
-
Converging inflection points. Clinical readouts, label expansions, and reimbursement negotiations are converging in 2026. Sponsors with mid‑ to late‑stage programs will decide whether to accelerate manufacturing scale‑up, initiate geographic launches, or reallocate capital to other immuno‑oncology targets.
Worldwide Asset Leasing Software Market -
Commercialization sequencing matters. The market’s rapid expansion is concentrated in a limited set of commercialized assets, but pipeline outcomes and regulatory actions will materially shape adoption curves for combinations and bispecific formats.
Worldwide Enterprise Semantic Search Software Market -
Concentration and competitive intensity. Our market concentration analysis shows a high degree of consolidated revenue among leading holders, creating a market where incumbent strategies, partnership choices, and real‑world evidence programs strongly influence access and pricing.
Recent Industry Signals and Their Strategic Implications
-
Approved precedent — Opdualag (relatlimab + nivolumab): The regulatory track record for relatlimab as the first approved LAG‑3‑blocking antibody combination has materially de‑risked the biology and established a commercial playbook for fixed‑dose LAG‑3 combinations. This approval underpins our adoption assumptions in the metastatic melanoma setting but does not eliminate uncertainty in adjuvant or broader solid tumor applications.
-
Mixed clinical momentum — key trial readouts: A notable late‑stage adjuvant trial did not meet its primary endpoint (recurrence‑free survival), highlighting how a single high‑profile negative result can reset expectations across indications, investor sentiment, and regulatory scrutiny. Firms with near‑term readouts should model downside scenarios alongside upside pathways.
-
Pipeline diversity: Multiple modalities — monoclonal antibodies, bispecific constructs (PD‑1 x LAG‑3), and novel LAG‑3 agonist/soluble fusion approaches — are in play. Commercial differentiation will rely on safety/tolerability tradeoffs, biomarker strategies, and combination exclusivity with established checkpoint inhibitors.
What the Report Delivers: Operational Intelligence, Not Ambiguity
We designed the report as a decision tool for executive teams, BD&L functions, and investment committees. Key deliverables include:
-
Dynamic forecasting model: an integrated, scenario‑driven model that projects global revenues (USD, Million) across 2026–2032 with transparent assumptions for uptake, pricing, and indication expansion. The model is structured to let users apply custom assumptions for approval timelines, label breadth, and discounting.
-
Scenario and sensitivity analysis: fast‑track, base‑case, and conservative scenarios with sensitivity to pivotal trial outcomes, payer responses, and competitive launches.
-
Regulatory and reimbursement playbooks: country‑level sequencing strategies, likely HTA considerations, and payer negotiation tactics for fixed‑dose combination immunotherapies.
-
Manufacturing and supply‑chain matrix: capacity requirements, COGS levers, and quality/regulatory checkpoints for biologics scale‑up — including practical mitigation for common biologic manufacturing constraints.
-
Commercial launch and access roadmap: go‑to‑market blueprints that map medical affairs, real‑world evidence generation, and payer engagement to product lifecycle milestones.
-
Deal and valuation frameworks: term sheets and valuation sensitivities for licensing, co‑development, and M&A transactions structured around clinical timing and exclusivity profiles.
Note: In keeping with our “trailer” approach to this public brief, detailed region/type/application splits and proprietary unit‑price schedules are intentionally omitted from this release. The full report contains granular tables, downloadable datasets, and an interactive Excel model to support board‑level decisioning.
Competitive Landscape: Who Matters and Why
The LAG‑3 competitive map is best understood through three strategic archetypes: commercial incumbents, late‑stage challengers, and niche/technology innovators.
-
Bristol Myers Squibb (incumbent commercializer): With the commercial presence of the first approved LAG‑3 blocking combination, BMS sets a reference point for pricing, combination strategies, and real‑world evidence programs. Their experience with Opdualag provides both a clinical and a commercial template that competitors must benchmark against.
-
Regeneron / Sanofi (late‑stage challenger / partner model): Their anti‑LAG‑3 program in combination with an established PD‑1 partner represents a conventional challenger strategy — leverage partner footprints, accelerate registration, and contest indication expansion. Timing of pivotal readouts will determine their ability to capture market share from incumbents or carve out complementary niches.
-
Merck, Roche, Novartis, and other large oncology players (portfolio hedges): These firms bring regulatory experience, global commercialization scale, and combination assets that could be decisive in label expansion and geographic rollouts. Their engagement often signals a step‑change in market expectations.
-
Bispecific and platform innovators (MacroGenics, Xencor, F‑star): Bispecific constructs that co‑target PD‑1 and LAG‑3 aim to offer differentiated efficacy or dosing convenience. These platforms will be judged on safety tradeoffs, manufacturability, and comparative effectiveness vs. combination therapy.
-
Specialized approaches (Immutep): Non‑blocking or agonist LAG‑3 constructs introduce alternative mechanisms of action (e.g., MHC class II agonism) that may address different therapeutic niches such as autoimmune indications or vaccine adjuvants.
Strategic Recommendations for 2026
-
Prioritize evidence generation over headline approvals. Given the sensitivity of uptake to real‑world safety and comparative effectiveness, invest early in RWE studies and payer‑targeted health economics dossiers.
-
Time manufacturing scale‑up to data inflection points. Avoid premature capital intensity unless internal forecasts underwrite downside scenarios; instead structure scalable contract manufacturing and options to accelerate production post‑readout.
-
Adopt a conditional partnering stance. For smaller developers, negotiate deals that balance near‑term funding with milestone‑based payments contingent on specific regulatory and commercial outcomes.
-
Differentiate via biomarkers and patient selection. As checkpoint combinations proliferate, precise biomarkers and subgroup evidence will be key to securing favorable reimbursement and clinician adoption.
-
Model multiple adoption curves. Build finance and commercial plans that accommodate rapid uptake in select indications versus slower, more diffuse adoption across tumor types.
-
Prepare for payers’ scrutiny on combination pricing. Health systems will interrogate the additive value of LAG‑3 contributions to combination regimens — prepare independent value assessments and flexible contracting scenarios (e.g., outcomes‑based agreements).
How PW Consulting Supports Executive Decisions
Our practice couples deep life‑science domain expertise with commercial strategy execution. For 2026, we offer targeted engagements that include:
-
Customized forecasting and valuation linked to client‑specific portfolios and development timelines.
-
Due diligence packages for BD&L that prioritize clinical milestones, freedom‑to‑operate, and comparator strategy.
-
Launch readiness audits and payer engagement simulations tailored to fixed‑dose immunotherapy combinations.
-
Negotiation support for manufacturing contracts and licensing deals with scenario‑based term sheets and risk allocation matrices.
Our full Worldwide LAG‑3 Antibody Market report includes a comprehensive competitor tracker, an interactive financial model (USD, Million), and downloadable appendices that detail assumptions, sensitivity matrices, and payer modeling. The public briefing intentionally omits granular regional and indication‑level splits to preserve the value of the full dataset. For boards, BD teams, and investors preparing for 2026, the complete report and model deliver the granular inputs required to move from strategic intent to executable plans.
To access the full report, interactive model, and bespoke advisory offerings, please visit our report landing page or contact PW Consulting’s Life Sciences practice. In the next 12–24 months, the choices companies make about clinical sequencing, partnering, and evidence generation will determine who captures the majority of the LAG‑3 opportunity — and who is left exposed to downside scenarios. Our analysis equips you to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide System on Module Boards Market Poised to Expand at a Robust 11.45% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide System on Module (SoM) Boards Market — Strategic Briefing for 2026 Decision‑Makers
Introduction
PW Consulting’s latest market intelligence brief on the Worldwide System on Module (SoM) Boards market is designed as a pragmatic decision companion for executives planning capital allocation, product roadmaps, and supply‑chain strategies in 2026. Built on a transparent market model (base year 2025) and forward projections to 2032, the study balances quantitative rigor with hands‑on operational guidance. This article highlights the strategic value of the report and summarizes the high‑level industry dynamics—deliberately omitting granular segment tables and vendor‑level revenue breakdowns to preserve the report’s role as a lead conversion asset.
Worldwide Portable Automotive Tire Pressure Gauges Market
Executive snapshot — the macro view that drives decisions
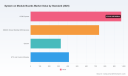
The SoM market has moved from a niche engineering commodity into a strategic component class for embedded systems across industrial automation, transportation, medical, and edge AI deployments. Our baseline figures reflect that transformation: the market grew materially from the start of the last five‑year window and reached a global scale of approximately USD 2.45 billion in 2025. Under our primary scenario, the market is projected to expand at a compound annual growth rate (CAGR) of roughly 11.45% through the 2026–2032 forecast window, roughly doubling the market scale by the early 2030s. Market concentration metrics indicate a mid‑tier consolidation trend: the top three suppliers control a meaningful share of market revenue while the top five further increase concentration—signaling both scale advantages and opportunity pockets for focused challengers.
Smart Power Plant Controller (SPPC) Market
Why this matters for 2026 strategy
- Platform and architecture selection matters: Choices between ARM, x86 and heterogeneous FPGA/SoC platforms are now strategic, affecting lifespan, power budgets, software ecosystems, and aftermarket support costs.
- Time‑to‑market and design wins are decisive: Shorter procurement cycles and faster module qualification translate directly to commercial success for OEMs targeting aggressive product roadmaps.
- Supply‑chain economics are non‑linear: Semiconductor lead‑time volatility, tariff regimes and raw‑material cost shocks reshape total cost of ownership and build vs. buy calculus.
- Consolidation creates differentiated routes to scale: A partially consolidated vendor landscape favors partnerships, customized module programs and co‑engineering deals for rapid product differentiation.
What the report delivers — practical, executable intelligence
Beyond headline forecasts, the report is organized to be immediately usable by product, procurement and corporate development teams. Key deliverables include:
Worldwide Clinical Research Services (CRS) Market
- Dynamic market model (2020–2032) with scenario toggles that stress test growth under supply shocks, policy interventions and adoption accelerators.
- Technology adoption timelines mapping processor nodes, AI acceleration blocks, and connectivity stacks to likely application windows.
- Supplier scorecards and maturity matrices that synthesize engineering capability, long‑term availability, certification footprints and aftermarket support.
- Procurement playbooks: BOM cost benchmarking templates, lead‑time hedging strategies and negotiation guidance for long‑term supply agreements.
- Commercial roll‑out playbooks for platform providers and OEMs, covering modular product architectures, reference‑design strategies, and launch KPIs for capturing design wins.
- Regulatory and trade impact assessment, offering pragmatic options for localization, dual‑sourcing and compliance routing.
- An annex of primary interviews, case studies and vendor dialogues used to validate assumptions and build actionable checklists.
Competitive landscape — players to watch and what they reveal
The competitive map combines established embedded specialists and agile regional vendors. The report profiles leading suppliers and highlights their strategic positioning, innovation focus and go‑to‑market moves. Examples include:
- Toradex (Horw, Switzerland) — toradex.com: A market‑leading provider with portfolio depth across Verdin, Colibri and Apalis families, leveraging NXP i.MX, TI Sitara and Renesas platforms to anchor industrial deployments. Recent product introductions emphasize edge AI readiness.
- Variscite (Yokneam, Israel) — variscite.com: A specialist in compact SoMs (DART / VAR‑SOM lines) targeting IoT and edge compute, notable for modular reference designs and rapid engineering support models.
- Kontron (Augsburg, Germany) — kontron.com: Strong in open standards (SMARC, Qseven, COM Express) with ruggedized modules and qualification programs for industrial IoT customers.
- Advantech and AAEON (Taipei / New Taipei City, Taiwan) — advantech.com / aaeon.com: Broad portfolios addressing automation and gateway markets, with deep channel networks for system integrators.
- Phytec, Compulab, Gateworks, TechNexion and regional players: Each pursues differentiated niches—automotive/avionics qualifications, outdoor video/wireless modules, and AI/vision optimized SoMs. Their roadmaps show how vendors compete on certification, extended temperature ranges, and verticalized software stacks.
Recent vendor moves—product launches featuring advanced NXP and TI processors, SMARC 2.1 qualifications, and production ramp announcements—underscore a market pivot toward edge AI and domain‑specific modules. The competitive implications are straightforward: engineering depth and ecosystem partnerships increasingly determine who secures premium design wins.
External dynamics shaping supplier economics and product choices
Macro‑policy and input market dynamics are materially shaping 2026 choices:
- Policy levers: The EU Chips Act and other regional industrial policies are directing significant funding to semiconductor capacity and design ecosystems, improving medium‑term component availability for manufacturers with EU footprints.
- Export controls: Restrictive export rules on advanced semiconductors can complicate distribution to some markets and require careful compliance workflows for multinational OEMs.
- Lead‑time normalization: After extreme peaks in prior cycles, lead times for key SoC families have shortened materially—shifting procurement strategy from panic buying to targeted hedging and supplier collaboration.
- Tariffs and input costs: Trade measures and tariff regimes (including certain duties on components and PCBs) remain pricing levers that influence where to assemble and how to price products.
- Raw material pressure: Price moves in critical inputs—such as gallium used in power and RF components—introduce non‑linear cost risks for power‑sensitive SoM designs.
Strategic imperatives for 2026 — how to translate insights into action
PW Consulting recommends a set of prioritized actions for companies looking to convert market momentum into lasting advantage in 2026:
- Adopt modular product architectures: Reduce redesign cycles by standardizing on a small set of SoM form factors and creating clean interface abstractions for faster board‑level swaps.
- Diversify supplier exposure: Combine tier‑1 specialists with agile regional partners to balance scale, customization capability and geopolitical risk.
- Lock strategic component supply early: Use targeted long‑lead purchases for critical SoCs, and negotiate dual‑sourced component agreements to avoid single‑point failures.
- Localize manufacturing selectively: For products serving regulated or high‑margin markets, local assembly and certification hubs can mitigate tariffs, reduce lead times and improve service levels.
- Embed software and lifecycle services: Differentiate on secure boot, over‑the‑air update frameworks and long‑term support contracts that monetize post‑sale relationships.
- Use financial hedges for raw‑material exposure: For power‑sensitive modules, incorporate commodity hedging clauses or indexation mechanisms in supplier contracts where feasible.
- Pursue focused M&A or JV plays: Target bolt‑on capabilities—software stacks, certification labs, or regional assembly capacity—that speed route‑to‑market without diluting core R&D.
Each recommendation is substantiated in the full report with implementation roadmaps, procurement templates, and KPI matrices that guide execution from pilot to scale.
How boards and executive teams should use the report in 2026
The report is structured for rapid assimilation by non‑technical leadership and deep‑dive by engineering and procurement teams alike. Use it to:
- Inform capital allocation decisions: tie module choices to revenue and margin scenarios.
- Prioritize product roadmaps: align architecture choices with three‑year certification and support costs.
- Shape procurement contracts: use supplier scorecards and lead‑time models to design resilient sourcing strategies.
- Screen M&A targets: apply our buyer’s checklist and valuation bridges for capability acquisitions.
Additionally, the research package includes an interactive model and a set of annexes (vendor dialogues, BOM templates, certification timelines) that turn insights into executable tasks for 60‑ to 120‑day pilots.
Conclusion and next steps
The SoM market in 2026 presents simultaneous challenges and opportunities: accelerating adoption in AI‑enabled edge systems, policy interventions reshaping supply geographies, and supplier consolidation that creates both scale advantages and white spaces for specialists. PW Consulting’s Worldwide System on Module Boards Market report offers the quantitative backbone and practical playbooks needed to translate those dynamics into competitive advantage.
To access the full segmentation tables, supplier scorecards, and the interactive market model that underpin the recommendations summarized here, please consult the full report on our website. This briefing is intentionally selective—designed to demonstrate the depth of our work while preserving the detailed, actionable intelligence contained in the full publication.
For detailed analysis of this topic, please visit the official page: Worldwide System on Module Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com