

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide AI Learning Machine Market Set to Surge at 21.08% CAGR, New Insights Report Finds

Worldwide AI Learning Machine Market: Strategic Imperatives for Enterprise Decision‑Makers in 2026
As organizations plan technology investments and education providers rethink delivery models for the coming five years, PW Consulting’s new Worldwide AI Learning Machine Market report—anchored on a 2025 base year and a 2026–2032 forecast horizon—provides an evidence‑based roadmap for executives, procurement leads, and policy teams. The global market has moved from niche experimentation to mainstream adoption: between 2020 and 2025 the market expanded rapidly, and our modeling projects continued acceleration in 2026 and beyond, driven by converging forces in hardware improvements, model availability, regulatory nudges, and shifts in learning models. Our forecast uses a 21.08% compound annual growth rate and projects a multi‑billion dollar opportunity by 2032 under the baseline scenario.
Phosphate Analyzer Market
Why this report matters for 2026 strategic decisions
-
Timing: 2026 is a pivotal year when several macro and regulatory inflection points collide—new national AI standards, classroom AI literacy mandates, and the first wave of content‑native partnerships. These create windows where early movers can lock in distribution, content, and data partnerships while mitigating regulatory friction.
Worldwide Punch & Die Storage Cabinet Market -
Procurement clarity: Procurement teams are facing unfamiliar product classes—integrated tablets, stationary learning devices with embedded models, and hybrid robotic bases. Our report supplies a vendor evaluation matrix, TCO templates, and procurement clauses aligned to emerging compliance standards so teams can move from vendor demos to defensible purchase decisions.
Educational Monocular Microscopes Market -
Risk control: The landscape blends consumer hardware practices with sensitive learner data. We model regulatory exposure under multiple enforcement intensities and provide mitigation playbooks (data minimization, on‑device processing thresholds, and third‑party audit clauses) for 2026 rollouts.
-
Value capture: For product and business leads the report outlines monetization archetypes—hardware subsidization through content licensing, subscription learning services, and institutional procurement—highlighting levers that most influence unit economics and churn over a three‑year horizon.
What’s in the report: practical, executable content
-
Market sizing and scenario forecasts: detailed baseline, upside and downside trajectories through 2032 using bottom‑up demand drivers and supplier capacity constraints.
-
Vendor scorecards: side‑by‑side assessments covering product maturity, model strategy (on‑device vs. cloud), content ecosystems, pricing architecture, support footprint, and compliance posture.
-
Implementation playbooks: step‑by‑step guides for pilots, rollouts, and scale, including change management templates for teachers and IT, interoperability checklists, and classroom acceptance metrics.
-
Procurement and contracting toolkit: RFP language, SLA constructs for model performance, data usage clauses, and sample budget scenarios that translate strategic aims into line‑item budgets.
-
Regulatory and security frameworks: mapping of national standards and generative AI safety requirements, recommended audit regimes, and incident response flows tailored to learning devices.
-
Competitive and partnership playbook: go‑to‑market options mapped for hardware OEMs, content owners, and systems integrators, plus templates for licensing and co‑development agreements.
Market dynamics: drivers, headwinds and critical inflection points
Three structural forces shape the market through 2026:
-
Demand pull from constrained traditional tutoring channels: Policy changes reducing offline tutoring have accelerated at‑home educational technology adoption, creating demand for compliant, structured AI learning devices.
-
Supply side differentiation via content and models: Companies that pair proprietary large models and curated content ecosystems achieve stronger retention and higher willingness to pay. Content exclusivity deals becoming visible in 2026 exemplify this dynamic.
-
Hardware and compute constraints: Export controls on advanced semiconductors and manufacturing equipment constrain high‑performance on‑device compute for some vendors, increasing the relevance of hybrid cloud designs and optimized model architectures.
These forces do not operate uniformly. Regulatory clarity in some markets is increasing (with standards addressing ML algorithm security and generative AI safety), while others remain fragmented. Our technical risk assessment and compliance map in the report helps enterprises match product specifications to jurisdictional requirements before deployment.
Competitive landscape: who’s shaping the market now
The sector is a mix of established education incumbents, consumer electronics firms, and AI platform players. Market concentration is meaningful but far from monopolistic: the top three firms capture a notable portion of global value while the top five expand that reach further—an important context for partnership or acquisition strategies.
-
iFLYTEK (Hefei, China): A leader in integrating cognitive large models into dedicated learning devices, focused on personalized K‑12 tutoring, voice interaction, and homework assistance. In 2025 the company reported a material revenue acceleration in its smart education segment, and in January 2026 iFLYTEK announced an exclusive content partnership that expands its English learning portfolio—an example of how content deals are being used to differentiate hardware offers.
-
Yuanfudao / Xiaoyuan (Beijing, China): Known for tablet + intelligent base designs that blend diagnostic capabilities and emotional interaction. Their 2025 product generation positions them strongly for companion‑style deployments and highlights the strategic value of hardware innovations that enable novel learning interactions.
-
Zuoyebang (Beijing, China): Focused on AI tutoring, homework assistance, and companion features for younger learners. Their product strategy underscores the ongoing shift from single‑purpose devices to multifunctional learning ecosystems.
-
TAL Education Group (Xueda / Xueersi): Brings deep curriculum design and brand trust to learning devices, leveraging large models for adaptive learning and integration with classroom offerings.
-
BBK, Readboy, Xiaodu (Baidu): Represent a spectrum from consumer OEMs emphasizing hardware ergonomics and screen safety to platform players folding educational features into broader smart hardware portfolios.
For buyers, the implication is clear: evaluate suppliers not just on hardware specs but on content partnerships, model governance, and supply chain resilience. Our vendor selection framework assigns weights to these dimensions based on deployment objectives (institutional vs. consumer vs. hybrid).
Regulatory and operational risks enterprises must plan for in 2026
-
Standards and AI safety: New national standards for ML algorithm security and generative AI safety are moving from guidance to enforceable regimes. Compliance will need to be demonstrable—log retention, model provenance, and content review processes are increasingly table stakes.
-
Curriculum mandates: Several jurisdictions are integrating AI literacy into core instruction. Devices will need to support curriculum alignment and teacher enablement features rather than merely delivering content.
-
Supply chain and compute access: Geopolitical controls on advanced semiconductors impact on‑device inference capabilities and may force architectural tradeoffs that affect latency, privacy, and cost.
-
Content safety and platform governance: Group standards and vendor self‑regulation around content filtering (for example, controls to block gaming content) are emerging. Institutional buyers should insist on auditability and transparent moderation rules.
How to use the report in boardroom conversations
-
Investment committees: Use our three scenario forecasts to stress‑test capital allocations and estimate the payback period for hardware pilots under varying adoption rates and content monetization models.
-
Procurement teams: Adopt the RFP language and SLA templates to reduce procurement cycle time and reduce downstream compliance risk.
-
Product and partnerships: The vendor scorecards and partnership playbooks provide practical starting points for licensing negotiations and co‑development agreements, including guardrails for data usage and IP sharing.
-
Policy and legal teams: Leverage the regulatory map and incident response flows to craft institutional policies around student data, content safety, and audit requirements.
What we intentionally leave out here—and why
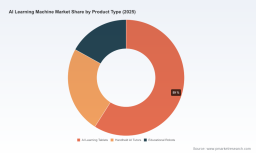
To preserve the strategic value of the full report and support informed procurement and investment flows, we have summarized macro trends and firm‑level dynamics in this announcement but withheld granular segmentation disclosures (region‑by‑region shares, product‑type and end‑user monetary splits and other detailed tables). The report contains those specifics, including downloadable datasets, interactive scenario tools, and country‑level sensitivity analysis that are essential for transaction‑level decision making. This “preview” approach is intentional: we provide enough rigor to enable initial prioritization while directing decision‑makers to the full materials for deal execution and contract drafting.
Next steps for clients
-
Commission a tailored briefing: We offer bespoke briefings that map our findings into client‑specific impact assessments—covering procurement timing, pilot site selection, and 18‑month roadmaps.
-
Request the deep‑dive dataset: Institutional subscribers may access the underlying segment models, concentration tables, and vendor benchmarks to drive RFPs and board materials.
-
Engage our implementation practice: For organizations ready to pilot in 2026, PW Consulting provides an end‑to‑end service from site readiness assessment to teacher enablement and post‑pilot evaluation.
In short, the AI learning machine market is moving from exploratory pilots to commercially meaningful deployments. Firms that align technology architecture, content strategy, and regulatory hygiene in 2026 will secure outsized advantages over the following five years. PW Consulting’s Worldwide AI Learning Machine Market report equips leaders with the analytic foundation and practical tools needed to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide AI Learning Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com