

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PCM Metal Sheet Market Projected to Grow at a 5.15% CAGR Through 2032, Driven by Strong Asia‑Pacific Demand

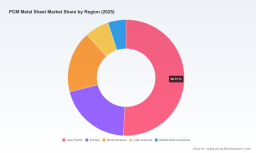
PCM Metal Sheet Market — Strategic Outlook for 2026: A PW Consulting Brief
As demand patterns settle after a period of near-term volatility, pre‑coated metal (PCM) sheet markets move from short‑term recovery into a structurally evolving phase. PW Consulting’s new market research — based on a 2020–2025 historical baseline and a 2026–2032 forecast horizon — quantifies that transition and translates it into executable choices for suppliers, OEMs, and strategic investors heading into 2026. The market registered robust scale in the base year (2025) and our scenario-led projections assume a steady compound annual growth rate (CAGR) of 5.15% through the forecast window, providing a pragmatic reference for capital planning, product roadmaps, and commercial strategies.
Hollow Fiber Bioreactors Market
Why this report matters for 2026 decision cycles
-
Timing: 2026 is the inflection year where capital deployment, product launches, and supplier rearrangements planned in 2024–25 will either compound value or expose execution risk. Our analysis pinpoints the commercial and operational levers that determine the outcome.
Single-stage Reverse Osmosis Filtration Systems Market -
Macro-to-micro translation: PW Consulting bridges headline growth with granular, actionable levers — manufacturing throughput, substrate selection, coating chemistry choices, and certification pathways — so leaders can move from “market knows” to “we do.”
Lathe CNC Device Market -
Risk calibration: With upstream cost pressure and regulatory tightening, the report provides scenario-based sensitivity matrices for margin, inventory, and working capital that are immediately usable in 2026 budgeting cycles.
Executive synthesis — what the numbers mean strategically
The PCM market’s compound growth projection (CAGR: 5.15% over the forecast period) is neither hyper‑growth nor contractionary; it is characteristic of a mature industrial material that is re‑differentiating through value‑added coatings, functional additives (e.g., antimicrobial, anti‑scratch), and integrated supply partnerships with appliances and construction OEMs. For corporate strategists, the implication is clear: volume growth will come from targeted application innovation and supply efficiency rather than broad‑based market expansion. That creates an opening for differentiated players and vertically integrated groups to extract premium returns through technology, brand, and logistical excellence.
Practical intelligence in the report (operationally focused)
-
Cost and margin playbooks: detailed models map the sensitivity of finished‑sheet margins to CRC/HRC differentials, zinc coating choices, and coil‑processing yields. These allow procurement teams to stress‑test supplier quotes and to quantify the break‑even for passing raw material inflation downstream.
-
Coating strategy templates: comparative frameworks evaluate polymer systems, film‑lamination versus liquid coating, and performance tradeoffs (corrosion resistance, color fidelity, formability). These are tailored to appliance, building, and transport use cases with implementation checklists for pilot lines.
-
CAPEX scheduling and utilization scenarios: a production planner’s toolset for 2026 prioritizes which lines to upgrade, retrofit, or mothball under three demand scenarios; ROI gates include time‑to‑market for new color sets and certifications.
-
Commercial go‑to‑market blueprints: contract structuring and service SLAs are described for long‑term offtake arrangements with major OEMs, including packaging, Q‑control processes, and returns management that protect price realization.
-
Supply‑chain stress test: recommendations for buffer sizing, inventory segmentation, and strategic dual‑sourcing to harden supply continuity against upstream coil price swings and logistics disruptions.
Industry dynamics impacting 2026 strategies
-
Upstream pricing: material dynamics are non‑trivial — cold‑rolled coil (CRC) commands a meaningful premium relative to hot‑rolled coil (HRC) due to the extra processing required for PCM substrates. In parallel, benchmark HRC indices have shown recent month‑over‑month movement that directly affects base costs for PCM producers. Firms that ignore these spreads risk margin erosion; those that proactively reconfigure buying and hedging can protect or even improve gross margins.
-
Standards and certifications: compliance pathways (ISO 9001, RoHS, plus third‑party testing by SGS/BV/Intertek) are table stakes. The report includes a compliance ladder showing how incremental certification investments translate into price premium bands and preferred supplier status with global OEMs.
-
Product differentiation: coating technology, extended warranties (e.g., long‑term corrosion resistance), and color stability are where PCM suppliers can create defensible value. We identify which functional claims carry the most commercial leverage in appliance and building verticals and offer a prioritization matrix for R&D budgets.
Competitive landscape — positioning and strategic implications
The PCM sector is moderately concentrated: the three largest players capture material market share, and the top five firms further increase that concentration. This structure creates both constraint and opportunity. Dominant global steelmakers and integrated coated‑steel providers enjoy scale, supply security, and sales channels into construction and appliances; at the same time, regional specialists and high‑performance niche players capitalize on agility, speed to market, and customization.
-
Global integrated suppliers (examples include long‑established steel majors): advantage lies in upstream integration, broad substrate portfolios, and large coil‑coating capacity. Their strategic playbooks in 2026 will focus on margin protection through improved coating yields, selective premiumization of product lines, and long‑term OEM contracts.
-
Regional and specialty producers (examples include targeted PCM manufacturers and coil‑coaters): these firms compete on customization, color matching precision, and after‑sales support. Recent public disclosures show product claims such as high salt‑spray resistance, tight ΔE color tolerances, and ISO processes — all translatable into differentiated commercial offers for appliance brands and façade specialists.
-
Manufacturing service providers: independent coil centers and contract coaters will be critical to service OEM decentralization strategies, allowing appliance makers to localize supply without re‑investing in full‑scale upstream capacity.
Recent corporate moves and what they signal for 2026
-
Operational commitments and community engagement by regional manufacturers underscore a twofold priority: ensure stable throughput and maintain social license. Visibility into factory activity and local stakeholder engagement matters more for permitting and workforce stability than in prior cycles.
-
Performance claims from niche exporters — such as extended salt spray records and precision color matching — indicate that product quality is a growing gatekeeper for access to higher‑margin appliance programs. Buyers in 2026 will increasingly validate these claims via independent labs as a procurement precondition.
-
Catalog and product documentation refreshes from leading suppliers show an acceleration in portfolio modularity — more SKUs with shorter lead times — which, if matched by production flexibility, will pressure traditional lead‑time premia.
Strategic recommendations for 2026 decision‑makers
-
Procurement and pricing: institute a two‑track raw material strategy — tactical hedges for the near term and strategic long‑term offtake agreements with selected upstream partners. Model exposures against CRC/HRC spreads and set dynamic pass‑through clauses to preserve margins.
-
Product strategy: prioritize coatings that deliver measurable, verifiable performance attributes (e.g., salt spray, color delta, formability) aligned to targeted OEM specs. Short‑cycle pilot programs that include third‑party validation reduce commercial risk and accelerate adoption.
-
Capacity and CAPEX: condition incremental capacity investments on utilization improvement programs and modular upgrades rather than greenfield expansion. Retrofits that improve coating line efficiency and reduce rejects often yield faster paybacks than new lines.
-
Commercial structuring: adopt blended contract models that combine take‑or‑pay volumes with quality‑linked premiums to align incentives with OEMs, particularly for localized supply arrangements.
-
M&A and partnerships: look for bolt‑on acquisitions that add coating chemistries, color matching capabilities, or regional service centers. Strategic minority stakes with technology licensors can secure access to next‑generation functional coatings without full-scale acquisition risk.
Where the report draws the line — and why you should get the full study
This release is designed as a strategic primer: it demonstrates the analytic rigor and operationally relevant outputs that PW Consulting delivers, while preserving the proprietary granularity that clients rely on to make competitive moves. The full report contains the complete set of segment tables, granular regional and application breakdowns, company scorecards, supplier negotiation playbooks, and model‑ready datasets — elements we intentionally omitted here to ensure clients access the decisive details via the report package.
How to use the report in your 2026 planning cadence
-
Board briefing: use the executive slidepack to align the board on near‑term market exposures and the targeted premium segments that justify investment.
-
Budget cycles: integrate our sensitivity matrices into Q1 and mid‑year reviews to recalibrate CAPEX and working capital based on realized price paths.
-
Commercial pilots: deploy the product and coating selection templates in 60–90 day pilots with selected OEM customers to accelerate qualification and lock in early production slots.
PW Consulting’s PCM Metal Sheet Market research is built for action: it speaks to what to do, when to do it, and how to measure decision outcomes. For teams preparing budgets, negotiation strategies, or R&D roadmaps in 2026, the study converts market growth and concentration dynamics into executable, defensible plans. For full access to the proprietary segment datasets, supplier scorecards, and downloadable models that underpin these recommendations, please visit our report page or contact PW Consulting to arrange a briefing.
For detailed analysis of this topic, please visit the official page: PCM Metal Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com