

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
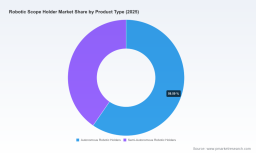
PW Consulting Forecast: Worldwide Robotic Scope Holder Market to Grow from USD 310.0 Million in 2025 to USD 514.3 Million by 2032 at a 7.5% CAGR — Autonomous Holders Lead the Market

Worldwide Robotic Scope Holder Market — Strategic Imperatives for 2026
As surgical suites continue their steady transition toward hybridized robotic workflows, hospital procurement teams, device OEMs, and financial sponsors face a narrow window in 2026 to translate technical opportunity into defensible commercial positions. PW Consulting’s latest Worldwide Robotic Scope Holder Market report (base year: 2025; historical coverage: 2020–2025; forecast horizon: 2026–2032) synthesizes primary interviews, device-level testing, and quantitative market modeling to pinpoint where resources should flow next. The global market reached approximately USD 310 Million in 2025 and — under our central-case assumptions (CAGR: 7.5% for 2026–2032) — is forecast to exceed USD 500 Million by the end of the forecast period. This briefing highlights the report’s strategic value for 2026 decision-making while preserving high-resolution datasets and segment tables for subscribers.
Worldwide Biopotential Sensors Market
Executive snapshot: Why 2026 matters
-
Commercial inflection: Adoption of scope-holding systems is moving from proof-of-concept deployments to enterprise procurement cycles — 2026 is the year many health systems will commit to platform-level integrations.
Worldwide Mobile Backend Services Market -
Technology consolidation: Voice control, AI-assisted positioning, and native compatibility with leading surgical robots are emerging as table stakes rather than premium differentiators.
Worldwide Urgent Care EMR Software Market -
Regulatory and reimbursement clarity: Electrical safety and device classification standards and emerging reimbursement pathways materially reduce adoption friction — but manufacturers must build dossiers now to benefit from near-term CPT and clearance windows.
Key market dynamics and implications
-
Demand drivers — Workflow automation and labor optimization: Hospitals are prioritizing devices that reduce reliance on manual camera control, shorten procedure times, and improve OR staffing efficiency. Buyers evaluate total cost of ownership (TCO) across device purchase, service agreements, and sterilization/consumable cycles.
-
Technology vectors — Integration, control modalities, and intelligence: Systems offering multi-modal control (voice activation, surgeon-controlled joysticks, and autonomous hold modes) and seamless integration with robotic platforms unlock the highest willingness-to-pay. Recent product updates emphasize AI-assisted positioning and platform interoperability as key differentiators.
-
Regulatory and reimbursement context: Devices in this class must satisfy IEC 60601-1 electrical safety requirements in the OR and generally follow Class II regulatory pathways (510(k) in the U.S.). CPT code 20985 and related reimbursement guidance increasingly cover computer-assisted scope positioning in laparoscopic workflows, improving the procedural economics case for purchasers.
-
Materials and sterilization: Medical-grade stainless steels and titanium alloys remain the materials of choice; designs are validated for autoclave sterilization up to typical industry temperatures. Procurement teams should require sterilization validation and lifecycle cost modeling as part of acquisition evaluations.
-
Market structure: The market exhibits meaningful concentration among a small number of established medical-device firms. The top three players account for the majority share, while the broader top-five captures a high proportion of market value — a dynamic that favors strategic partnerships, white-label agreements, and selective M&A for challengers seeking rapid scale.
Competitive landscape — what the major players signal
-
Mitaka Kohki (Tokyo): Known for multi-axis manipulators with sophisticated voice control and deep integration paths toward robotic-assisted platforms. Recent product updates emphasize AI-assisted positioning for robotic-assisted surgeries — a move that accelerates their relevance in dual-robot ORs.
-
FreeHand Surgical (London): A focused innovator in voice-activated endoscope holders; regulatory clearances and active presence at surgical society conferences make them a partner of choice for early adopter hospitals and specialty clinics exploring hybrid workflows.
-
EndoControl (now part of Medtronic): As an acquired technology within a major OEM, the ViKY asset benefits from scale in distribution and post-market support. Regulatory milestones expanding device compatibility with next-generation endoscopes strengthen its system-level value proposition.
-
Olympus (Tokyo): Brings platform-level optics, imaging stacks, and robotic positioning systems to the table. Integration of scope holders into established surgical imaging ecosystems supports bundled purchasing strategies and lock-in opportunities for health systems.
Strategic takeaways: incumbents are pushing both product-scope (platform integration, AI-assisted positioning) and go-to-market depth (channel partnerships, regulatory clearances). Challengers should target niche clinical workflows and interoperability wins, while buyers should weigh platform compatibility and service economics over nominal device cost.
Actionable 2026 playbook by stakeholder
-
For manufacturers and R&D leads:
-
Prioritize modular interoperability with leading robotic platforms and imaging stacks to shorten procurement cycles.
-
Invest in AI-assisted positioning and robust voice-control fail-safes to reduce cognitive load on the surgeon and improve adoption rates.
-
Lock down supplier agreements for medical-grade alloys and validated sterilization processes to shorten time-to-market and lower recall risk.
-
-
For hospital system executives and procurement:
-
Run total-cost-of-ownership pilots that include OR time-savings, anesthesia throughput effects, and staff redeployment benefits rather than comparing device price alone.
-
Request vendor evidence of IEC 60601-1 compliance, 510(k) clearance where applicable, and explicit sterilization-cycle validation.
-
Structure procurement contracts to include data-sharing clauses and interoperability milestones — these accelerate clinical ROI and protect against obsolescence.
-
-
For investors and strategic acquirers:
-
Given the market’s concentration dynamics, prioritize targets that offer either unique clinical differentiation (e.g., advanced autonomy in complex laparoscopic workflows) or distribution synergies with larger OEMs.
-
Use staged earn-outs tied to regulatory clearances and integration milestones to bridge valuation gaps for early-stage innovators.
-
What the PW Consulting report delivers (operational detail)
-
Market model and forecasts: Annualized revenue model across 2020–2032 with scenario-driven sensitivity (central, upside, downside) and explicit assumptions supporting a 7.5% CAGR for the forecast period.
-
Segmentation and adoption mapping: Regional, product-type, and surgical-application frameworks with demand drivers, price-elasticity matrices, and adoption curves. (Note: high-granularity segment tables and downloadable datasets are available in the full report.)
-
Regulatory and reimbursement playbooks: Step-by-step 510(k)/CE pathway mapping, IEC compliance checklists, and a reimbursement dossier template that aligns clinical claims with CPT code 20985 and analogous codes in major markets.
-
Vendor scorecards and supplier risk assessments: Comparative benchmarking across product performance, integration readiness, service networks, and component supply-chain risk.
-
Commercialization and M&A playbooks: Go-to-market roadmaps for incumbents and challengers, pricing and service models, and an M&A target shortlist with preliminary synergy estimates and integration risks.
-
Primary research and validation: Surgeon and clinical engineering interviews, OR workflow time-and-motion studies, and bench-testing of electromechanical and sterilization durability under clinical-use cycles.
Methodology and modeling transparency
-
Base and historical years: 2025 base year with historical analysis covering 2020–2025.
-
Forecast window: 2026–2032 with a central CAGR assumption of 7.5%. Forecast sensitivity isolates impacts from three variables: (1) rate of surgical-robot penetration, (2) pace of AI-assisted feature adoption, and (3) changes in reimbursement coding.
-
Data sources: Combination of primary interviews, device-level technical testing, regulatory databases, and proprietary pricing and tender intelligence. All assumptions and raw inputs are documented for client review.
Risks, blind spots, and watch items for 2026
-
Regulatory shifts: Any tightening of device classification or new electrical safety requirements would increase time-to-market and development cost. Conversely, streamlined clearances for integrated systems could accelerate adoption.
-
Reimbursement volatility: While CPT 20985 creates a pathway, payer uptake varies by market and can be subject to local coverage determinations. Real-world evidence is the decisive factor for permanent coverage.
-
Interoperability fragmentation: Proprietary integrations by large OEMs could create walled gardens; smaller vendors must prioritize open APIs and standards compliance to remain viable partners.
Conclusion — the strategic imperative for 2026 is clear: organizations that align product development with platform-level interoperability, secure regulatory and reimbursement pathways now, and structure commercial agreements around outcomes will capture disproportionate share as the market expands from its 2025 base toward the half-billion-dollar range at the end of the forecast window. PW Consulting’s Worldwide Robotic Scope Holder Market report provides the decision-grade intelligence, playbooks, and datasets needed to make those calls with confidence.
To access the full datasets, segmentation tables, vendor scorecards, and commercial templates referenced in this briefing, please visit the PW Consulting report page for the Worldwide Robotic Scope Holder Market. Our analysts are available for briefing sessions and bespoke scenario modeling to support your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Robotic Scope Holder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com