

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide System on Module Boards Market Poised to Expand at a Robust 11.45% CAGR Through 2032

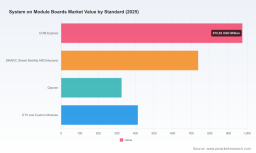
Worldwide System on Module (SoM) Boards Market — Strategic Briefing for 2026 Decision‑Makers
Introduction
PW Consulting’s latest market intelligence brief on the Worldwide System on Module (SoM) Boards market is designed as a pragmatic decision companion for executives planning capital allocation, product roadmaps, and supply‑chain strategies in 2026. Built on a transparent market model (base year 2025) and forward projections to 2032, the study balances quantitative rigor with hands‑on operational guidance. This article highlights the strategic value of the report and summarizes the high‑level industry dynamics—deliberately omitting granular segment tables and vendor‑level revenue breakdowns to preserve the report’s role as a lead conversion asset.
Worldwide Portable Automotive Tire Pressure Gauges Market
Executive snapshot — the macro view that drives decisions
The SoM market has moved from a niche engineering commodity into a strategic component class for embedded systems across industrial automation, transportation, medical, and edge AI deployments. Our baseline figures reflect that transformation: the market grew materially from the start of the last five‑year window and reached a global scale of approximately USD 2.45 billion in 2025. Under our primary scenario, the market is projected to expand at a compound annual growth rate (CAGR) of roughly 11.45% through the 2026–2032 forecast window, roughly doubling the market scale by the early 2030s. Market concentration metrics indicate a mid‑tier consolidation trend: the top three suppliers control a meaningful share of market revenue while the top five further increase concentration—signaling both scale advantages and opportunity pockets for focused challengers.
Smart Power Plant Controller (SPPC) Market
Why this matters for 2026 strategy
- Platform and architecture selection matters: Choices between ARM, x86 and heterogeneous FPGA/SoC platforms are now strategic, affecting lifespan, power budgets, software ecosystems, and aftermarket support costs.
- Time‑to‑market and design wins are decisive: Shorter procurement cycles and faster module qualification translate directly to commercial success for OEMs targeting aggressive product roadmaps.
- Supply‑chain economics are non‑linear: Semiconductor lead‑time volatility, tariff regimes and raw‑material cost shocks reshape total cost of ownership and build vs. buy calculus.
- Consolidation creates differentiated routes to scale: A partially consolidated vendor landscape favors partnerships, customized module programs and co‑engineering deals for rapid product differentiation.
What the report delivers — practical, executable intelligence
Beyond headline forecasts, the report is organized to be immediately usable by product, procurement and corporate development teams. Key deliverables include:
Worldwide Clinical Research Services (CRS) Market
- Dynamic market model (2020–2032) with scenario toggles that stress test growth under supply shocks, policy interventions and adoption accelerators.
- Technology adoption timelines mapping processor nodes, AI acceleration blocks, and connectivity stacks to likely application windows.
- Supplier scorecards and maturity matrices that synthesize engineering capability, long‑term availability, certification footprints and aftermarket support.
- Procurement playbooks: BOM cost benchmarking templates, lead‑time hedging strategies and negotiation guidance for long‑term supply agreements.
- Commercial roll‑out playbooks for platform providers and OEMs, covering modular product architectures, reference‑design strategies, and launch KPIs for capturing design wins.
- Regulatory and trade impact assessment, offering pragmatic options for localization, dual‑sourcing and compliance routing.
- An annex of primary interviews, case studies and vendor dialogues used to validate assumptions and build actionable checklists.
Competitive landscape — players to watch and what they reveal
The competitive map combines established embedded specialists and agile regional vendors. The report profiles leading suppliers and highlights their strategic positioning, innovation focus and go‑to‑market moves. Examples include:
- Toradex (Horw, Switzerland) — toradex.com: A market‑leading provider with portfolio depth across Verdin, Colibri and Apalis families, leveraging NXP i.MX, TI Sitara and Renesas platforms to anchor industrial deployments. Recent product introductions emphasize edge AI readiness.
- Variscite (Yokneam, Israel) — variscite.com: A specialist in compact SoMs (DART / VAR‑SOM lines) targeting IoT and edge compute, notable for modular reference designs and rapid engineering support models.
- Kontron (Augsburg, Germany) — kontron.com: Strong in open standards (SMARC, Qseven, COM Express) with ruggedized modules and qualification programs for industrial IoT customers.
- Advantech and AAEON (Taipei / New Taipei City, Taiwan) — advantech.com / aaeon.com: Broad portfolios addressing automation and gateway markets, with deep channel networks for system integrators.
- Phytec, Compulab, Gateworks, TechNexion and regional players: Each pursues differentiated niches—automotive/avionics qualifications, outdoor video/wireless modules, and AI/vision optimized SoMs. Their roadmaps show how vendors compete on certification, extended temperature ranges, and verticalized software stacks.
Recent vendor moves—product launches featuring advanced NXP and TI processors, SMARC 2.1 qualifications, and production ramp announcements—underscore a market pivot toward edge AI and domain‑specific modules. The competitive implications are straightforward: engineering depth and ecosystem partnerships increasingly determine who secures premium design wins.
External dynamics shaping supplier economics and product choices
Macro‑policy and input market dynamics are materially shaping 2026 choices:
- Policy levers: The EU Chips Act and other regional industrial policies are directing significant funding to semiconductor capacity and design ecosystems, improving medium‑term component availability for manufacturers with EU footprints.
- Export controls: Restrictive export rules on advanced semiconductors can complicate distribution to some markets and require careful compliance workflows for multinational OEMs.
- Lead‑time normalization: After extreme peaks in prior cycles, lead times for key SoC families have shortened materially—shifting procurement strategy from panic buying to targeted hedging and supplier collaboration.
- Tariffs and input costs: Trade measures and tariff regimes (including certain duties on components and PCBs) remain pricing levers that influence where to assemble and how to price products.
- Raw material pressure: Price moves in critical inputs—such as gallium used in power and RF components—introduce non‑linear cost risks for power‑sensitive SoM designs.
Strategic imperatives for 2026 — how to translate insights into action
PW Consulting recommends a set of prioritized actions for companies looking to convert market momentum into lasting advantage in 2026:
- Adopt modular product architectures: Reduce redesign cycles by standardizing on a small set of SoM form factors and creating clean interface abstractions for faster board‑level swaps.
- Diversify supplier exposure: Combine tier‑1 specialists with agile regional partners to balance scale, customization capability and geopolitical risk.
- Lock strategic component supply early: Use targeted long‑lead purchases for critical SoCs, and negotiate dual‑sourced component agreements to avoid single‑point failures.
- Localize manufacturing selectively: For products serving regulated or high‑margin markets, local assembly and certification hubs can mitigate tariffs, reduce lead times and improve service levels.
- Embed software and lifecycle services: Differentiate on secure boot, over‑the‑air update frameworks and long‑term support contracts that monetize post‑sale relationships.
- Use financial hedges for raw‑material exposure: For power‑sensitive modules, incorporate commodity hedging clauses or indexation mechanisms in supplier contracts where feasible.
- Pursue focused M&A or JV plays: Target bolt‑on capabilities—software stacks, certification labs, or regional assembly capacity—that speed route‑to‑market without diluting core R&D.
Each recommendation is substantiated in the full report with implementation roadmaps, procurement templates, and KPI matrices that guide execution from pilot to scale.
How boards and executive teams should use the report in 2026
The report is structured for rapid assimilation by non‑technical leadership and deep‑dive by engineering and procurement teams alike. Use it to:
- Inform capital allocation decisions: tie module choices to revenue and margin scenarios.
- Prioritize product roadmaps: align architecture choices with three‑year certification and support costs.
- Shape procurement contracts: use supplier scorecards and lead‑time models to design resilient sourcing strategies.
- Screen M&A targets: apply our buyer’s checklist and valuation bridges for capability acquisitions.
Additionally, the research package includes an interactive model and a set of annexes (vendor dialogues, BOM templates, certification timelines) that turn insights into executable tasks for 60‑ to 120‑day pilots.
Conclusion and next steps
The SoM market in 2026 presents simultaneous challenges and opportunities: accelerating adoption in AI‑enabled edge systems, policy interventions reshaping supply geographies, and supplier consolidation that creates both scale advantages and white spaces for specialists. PW Consulting’s Worldwide System on Module Boards Market report offers the quantitative backbone and practical playbooks needed to translate those dynamics into competitive advantage.
To access the full segmentation tables, supplier scorecards, and the interactive market model that underpin the recommendations summarized here, please consult the full report on our website. This briefing is intentionally selective—designed to demonstrate the depth of our work while preserving the detailed, actionable intelligence contained in the full publication.
For detailed analysis of this topic, please visit the official page: Worldwide System on Module Boards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com