

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market Poised to Surge at a 26.79% CAGR, Driving Rapid Biopharma Expansion

Worldwide LAG‑3 Antibody Market: Strategic Imperatives for 2026 — PW Consulting Market Brief
As LAG‑3 emerges from a research curiosity into a commercial immuno‑oncology axis, strategic clarity is accelerating from novelty to necessity. PW Consulting’s latest market study — the Worldwide Lymphocyte Activating 3 (LAG‑3) Antibody Market — translates five years of clinical momentum and commercial activity into an actionable decision framework for 2026. The market has expanded rapidly, from a modest USD 45.2 Million in 2020 to USD 1,320 Million in our 2025 base year. Our base‑case projection positions the market at approximately USD 1,770 Million in 2026 and growing at a 26.79% compound annual growth rate through 2032, reaching roughly USD 6,950 Million by the end of the forecast horizon. These headline dynamics set the stage — but the devil is in the operational detail that will determine winners and losers in the coming 18–36 months.
Worldwide Patient Experience Software Market
Why 2026 Is a Pivotal Decision Horizon
-
Converging inflection points. Clinical readouts, label expansions, and reimbursement negotiations are converging in 2026. Sponsors with mid‑ to late‑stage programs will decide whether to accelerate manufacturing scale‑up, initiate geographic launches, or reallocate capital to other immuno‑oncology targets.
Worldwide Asset Leasing Software Market -
Commercialization sequencing matters. The market’s rapid expansion is concentrated in a limited set of commercialized assets, but pipeline outcomes and regulatory actions will materially shape adoption curves for combinations and bispecific formats.
Worldwide Enterprise Semantic Search Software Market -
Concentration and competitive intensity. Our market concentration analysis shows a high degree of consolidated revenue among leading holders, creating a market where incumbent strategies, partnership choices, and real‑world evidence programs strongly influence access and pricing.
Recent Industry Signals and Their Strategic Implications
-
Approved precedent — Opdualag (relatlimab + nivolumab): The regulatory track record for relatlimab as the first approved LAG‑3‑blocking antibody combination has materially de‑risked the biology and established a commercial playbook for fixed‑dose LAG‑3 combinations. This approval underpins our adoption assumptions in the metastatic melanoma setting but does not eliminate uncertainty in adjuvant or broader solid tumor applications.
-
Mixed clinical momentum — key trial readouts: A notable late‑stage adjuvant trial did not meet its primary endpoint (recurrence‑free survival), highlighting how a single high‑profile negative result can reset expectations across indications, investor sentiment, and regulatory scrutiny. Firms with near‑term readouts should model downside scenarios alongside upside pathways.
-
Pipeline diversity: Multiple modalities — monoclonal antibodies, bispecific constructs (PD‑1 x LAG‑3), and novel LAG‑3 agonist/soluble fusion approaches — are in play. Commercial differentiation will rely on safety/tolerability tradeoffs, biomarker strategies, and combination exclusivity with established checkpoint inhibitors.
What the Report Delivers: Operational Intelligence, Not Ambiguity
We designed the report as a decision tool for executive teams, BD&L functions, and investment committees. Key deliverables include:
-
Dynamic forecasting model: an integrated, scenario‑driven model that projects global revenues (USD, Million) across 2026–2032 with transparent assumptions for uptake, pricing, and indication expansion. The model is structured to let users apply custom assumptions for approval timelines, label breadth, and discounting.
-
Scenario and sensitivity analysis: fast‑track, base‑case, and conservative scenarios with sensitivity to pivotal trial outcomes, payer responses, and competitive launches.
-
Regulatory and reimbursement playbooks: country‑level sequencing strategies, likely HTA considerations, and payer negotiation tactics for fixed‑dose combination immunotherapies.
-
Manufacturing and supply‑chain matrix: capacity requirements, COGS levers, and quality/regulatory checkpoints for biologics scale‑up — including practical mitigation for common biologic manufacturing constraints.
-
Commercial launch and access roadmap: go‑to‑market blueprints that map medical affairs, real‑world evidence generation, and payer engagement to product lifecycle milestones.
-
Deal and valuation frameworks: term sheets and valuation sensitivities for licensing, co‑development, and M&A transactions structured around clinical timing and exclusivity profiles.
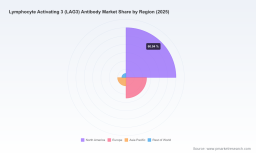
Note: In keeping with our “trailer” approach to this public brief, detailed region/type/application splits and proprietary unit‑price schedules are intentionally omitted from this release. The full report contains granular tables, downloadable datasets, and an interactive Excel model to support board‑level decisioning.
Competitive Landscape: Who Matters and Why
The LAG‑3 competitive map is best understood through three strategic archetypes: commercial incumbents, late‑stage challengers, and niche/technology innovators.
-
Bristol Myers Squibb (incumbent commercializer): With the commercial presence of the first approved LAG‑3 blocking combination, BMS sets a reference point for pricing, combination strategies, and real‑world evidence programs. Their experience with Opdualag provides both a clinical and a commercial template that competitors must benchmark against.
-
Regeneron / Sanofi (late‑stage challenger / partner model): Their anti‑LAG‑3 program in combination with an established PD‑1 partner represents a conventional challenger strategy — leverage partner footprints, accelerate registration, and contest indication expansion. Timing of pivotal readouts will determine their ability to capture market share from incumbents or carve out complementary niches.
-
Merck, Roche, Novartis, and other large oncology players (portfolio hedges): These firms bring regulatory experience, global commercialization scale, and combination assets that could be decisive in label expansion and geographic rollouts. Their engagement often signals a step‑change in market expectations.
-
Bispecific and platform innovators (MacroGenics, Xencor, F‑star): Bispecific constructs that co‑target PD‑1 and LAG‑3 aim to offer differentiated efficacy or dosing convenience. These platforms will be judged on safety tradeoffs, manufacturability, and comparative effectiveness vs. combination therapy.
-
Specialized approaches (Immutep): Non‑blocking or agonist LAG‑3 constructs introduce alternative mechanisms of action (e.g., MHC class II agonism) that may address different therapeutic niches such as autoimmune indications or vaccine adjuvants.
Strategic Recommendations for 2026
-
Prioritize evidence generation over headline approvals. Given the sensitivity of uptake to real‑world safety and comparative effectiveness, invest early in RWE studies and payer‑targeted health economics dossiers.
-
Time manufacturing scale‑up to data inflection points. Avoid premature capital intensity unless internal forecasts underwrite downside scenarios; instead structure scalable contract manufacturing and options to accelerate production post‑readout.
-
Adopt a conditional partnering stance. For smaller developers, negotiate deals that balance near‑term funding with milestone‑based payments contingent on specific regulatory and commercial outcomes.
-
Differentiate via biomarkers and patient selection. As checkpoint combinations proliferate, precise biomarkers and subgroup evidence will be key to securing favorable reimbursement and clinician adoption.
-
Model multiple adoption curves. Build finance and commercial plans that accommodate rapid uptake in select indications versus slower, more diffuse adoption across tumor types.
-
Prepare for payers’ scrutiny on combination pricing. Health systems will interrogate the additive value of LAG‑3 contributions to combination regimens — prepare independent value assessments and flexible contracting scenarios (e.g., outcomes‑based agreements).
How PW Consulting Supports Executive Decisions
Our practice couples deep life‑science domain expertise with commercial strategy execution. For 2026, we offer targeted engagements that include:
-
Customized forecasting and valuation linked to client‑specific portfolios and development timelines.
-
Due diligence packages for BD&L that prioritize clinical milestones, freedom‑to‑operate, and comparator strategy.
-
Launch readiness audits and payer engagement simulations tailored to fixed‑dose immunotherapy combinations.
-
Negotiation support for manufacturing contracts and licensing deals with scenario‑based term sheets and risk allocation matrices.
Our full Worldwide LAG‑3 Antibody Market report includes a comprehensive competitor tracker, an interactive financial model (USD, Million), and downloadable appendices that detail assumptions, sensitivity matrices, and payer modeling. The public briefing intentionally omits granular regional and indication‑level splits to preserve the value of the full dataset. For boards, BD teams, and investors preparing for 2026, the complete report and model deliver the granular inputs required to move from strategic intent to executable plans.
To access the full report, interactive model, and bespoke advisory offerings, please visit our report landing page or contact PW Consulting’s Life Sciences practice. In the next 12–24 months, the choices companies make about clinical sequencing, partnering, and evidence generation will determine who captures the majority of the LAG‑3 opportunity — and who is left exposed to downside scenarios. Our analysis equips you to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Lymphocyte Activating 3 (LAG3) Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com