

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aircraft Load Control Solutions Market Forecast to Reach USD 275.03 Million by 2032 at a 6.72% CAGR, Driven by Cloud-based Solutions and Passenger Airlines

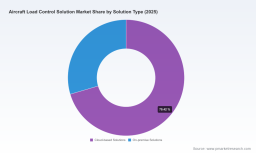
Worldwide Aircraft Load Control Solution Market — Strategic Outlook for 2026 Decision‑Makers
Executive summary
PW Consulting’s latest market intelligence report on the Worldwide Aircraft Load Control Solution market delivers an evidence‑based roadmap for executives making procurement, operational, and M&A decisions in 2026. The market, valued at USD 174.45 Million in our 2025 base year, is forecast to expand at a compound annual growth rate (CAGR) of 6.72% over the 2026–2032 forecast window, reaching USD 275.03 Million by 2032. This steady expansion reflects accelerating airline digitization, regulatory pressure for precision in weight & balance, and growing adoption of centralized load control models and cloud‑native architectures.
Worldwide Glass Hardware Market
Why this report matters for 2026
-
Timing: 2026 is a pivot year for fleet recovery, digital operations, and regulatory alignment. Operators that align load control investments with broader NextGen and airline IT modernization plans will capture disproportionate operational savings and risk reduction.
RC Plane Batteries Market -
Decision focus: Boards and COOs require a concise translation of market momentum into procurement strategy, vendor selection criteria, and value capture pathways. This report converts macro trends into executable options for 12–36 month programs.
Static Spray Ball Market -
Risk control: Given tightening oversight by ICAO, FAA, and EASA on load monitoring and data integrity, the strategic value of robust load control solutions now extends beyond efficiency into compliance and liability mitigation.
What the report contains — practical, actionable intelligence
-
Market sizing and trend analysis: A transparent time series (historical 2020–2025; base year 2025) and a 2026–2032 forecast that quantifies market scale and growth trajectory across solution models and delivery modes.
-
Use‑case driven segmentation: Operational archetypes and adoption roadmaps for passenger airlines, cargo operators, and ground handlers — with playbooks for centralized load control (CLC), station‑level operations, and hybrid models.
-
Vendor assessment framework: A practical RFP/RFX scorecard combining functional fit, integration readiness (flight planning, EFB, dispatch), regulatory compliance, uptime and disaster recovery, and total cost of ownership.
-
Implementation blueprints: Step‑by‑step migration plans for on‑premise to cloud migration, CLC consolidation, and phased automation that defend day‑of‑operations continuity.
-
Financial articulation: Payback scenarios and sensitivity analysis around fuel savings (EZFW optimization), ground handling throughput, and reduced disruption costs — modelled under conservative and aggressive adoption cases.
-
Competitive landscaping and M&A signals: Profiles of incumbent and emergent vendors, partnership archetypes, and strategic flags for consolidators and niche innovators.
-
Data & integration playbook: Data governance, validation checkpoints, and API patterns enabling near real‑time reconciliation with flight planning and aircraft systems.
Market dynamics shaping 2026 choices
-
Regulatory acceleration: Aviation authorities increasingly mandate precise, auditable weight & balance records and expect digital evidence of compliance. NextGen modernization programs and EASA/FAA certification pathways are pushing operators away from manual, ad‑hoc processes.
-
Operational economics: Fuel optimization and accurate zero fuel weight (EZFW) calculations are measurable levers to cut operating expense. Centralized Load Control (CLC) and automated loadsheet generation reduce error rates and gate delays, improving both safety and on‑time performance.
-
Technology shift: The market is migrating towards cloud‑enabled, API‑first solutions that support offline capabilities, mobile EFB integration, and automated load reconciliation. Buyers increasingly demand zero‑click or near‑zero manual interaction for routine loadsheet generation.
-
Service consolidation: Outsourced CLC providers are expanding footprint and scale economies. Recent provider disclosures illustrate how centralized centers support large numbers of airlines and process high volumes of load sheets annually — a factor that materially changes procurement calculus for mid‑sized carriers and ground handlers.
-
Concentration and competition: The industry exhibits moderate concentration — the top few vendors control a material share of the market. This creates a dual‑track environment where established players compete on integration breadth and service scale, while specialist vendors win on rapid innovation and niche functional superiority.
Competitive landscape — positioning and strategic reads
Our vendor mapping identifies three distinct strategic clusters: integrated airline systems vendors, specialist weight & balance solution providers, and centralized service operators. The market’s top three players collectively control roughly half of current market revenue, and the top five approach two‑thirds — a concentration profile that affects pricing leverage, partnership dynamics, and M&A opportunities.
-
Specialist W&B software firms (e.g., providers offering automated, visual exception‑based planning and high‑autonomy loadsheet generation) are winning adoption among carriers seeking quick operational uplift with minimal disruption.
-
Large airline IT vendors and flight‑ops integrators position load control as part of broader flight management and dispatch suites — an attractive option for airlines seeking a single‑vendor ecosystem but requiring careful evaluation of integration flexibility.
-
Centralized service operators leverage scale and geographic reach to offer CLC as a managed service — a compelling model for airlines and handlers that prioritize predictable OPEX and off‑platform risk transfer.
-
Notable developments illustrate these dynamics: a leading ground handler recently highlighted CLC centers in multiple countries supporting dozens of airlines and processing hundreds of thousands of load sheets annually — underscoring the operational and commercial value of scale.
Strategic recommendations for 2026
-
Adopt a two‑track procurement approach: For near‑term operational gains, select specialized, modular load control solutions with strong API and EFB support. For mid‑term strategic resilience, evaluate platforms that align with enterprise‑level flight operations suites.
-
Prioritize integration and data integrity over feature parity: The ability to reliably reconcile passenger and cargo data, integrate with flight planning and aircraft systems, and provide auditable trails for regulators will deliver outsized risk mitigation benefits.
-
Design CLC adoption as a business transformation: Treat Centralized Load Control not just as a systems replacement but as a re‑engineered operating model—align SLAs, uplift training per IATA designations, and embed governance for cross‑station consistency.
-
Validate cloud readiness and offline continuity: Insist on demonstrable offline capabilities and disaster recovery plans; ensure cloud migrations include a staged rollback and test program to protect day‑of‑operations.
-
Use vendor scorecards tied to measurable KPIs: Link procurement decisions to quantifiable targets such as loadsheet error reduction, gate dwell time improvements, and fuel savings recovered through tighter trim and load allocation.
-
Scan for M&A and partnership plays: Providers with differentiated automation, proprietary load automation logic, or strong CLC footprints are prime targets for strategic acquisition or partnership to accelerate capability build‑outs.
How to use this report in boardrooms and operational planning
-
Investment committees: Use the report’s financial scenarios to stress test capital outlays versus projected OPEX savings from automation and fuel optimization, and to set realistic payback windows.
-
CTOs and CIOs: Apply the integration playbook and vendor scorecard during RFP cycles to avoid costly rework and to ensure compliance and auditability are built into delivery contracts.
-
COOs and Ground Ops: Follow the implementation blueprints for phased CLC transitions that safeguard performance at hubs and remote stations while delivering immediate throughput and error‑reduction benefits.
-
Safety and Compliance teams: Leverage the regulatory mapping to prepare certification artifacts and to align training with internationally recognized IATA and regulatory standards.
Closing note — the value of granular intelligence
PW Consulting’s report delivers the granular insight that separates confident, fast‑moving adopters from reactive implementers. By combining a transparent market forecast (base year 2025, 2026–2032 outlook) with pragmatic procurement instruments, operational blueprints, and a surgical vendor evaluation framework, the study empowers leaders to convert the projected market growth trajectory into verifiable operational and financial outcomes.
For program leads preparing 2026 budgets, procurement windows, or M&A screening lists, the full report includes downloadable models, vendor due‑diligence templates, and regional adoption scenarios. To access the comprehensive datasets, segmentation analytics, and the complete competitive profiles that underpin these strategic recommendations, please consult the full PW Consulting market report.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Load Control Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com