

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Hermetic Packages Market to Expand from USD 4,500 Million in 2025 to USD 7,017 Million by 2032 at a 6.55% CAGR — Ceramic Segment Leads with USD 2,240 Million
By pmarketresearch, 2026-08-18
Hermetic Packages for Semiconductor Component Market — Strategic Imperatives for 2026
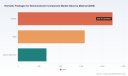
PW Consulting today publishes an executive briefing tied to our full market study, "Hermetic Packages for Semiconductor Component Market" (base year 2025, forecast 2026–2032). The briefing synthesizes the report’s most consequential findings for corporate leaders preparing budget cycles, product roadmaps and supply‑chain reconfiguration in 2026. Our analysis is grounded in a consistent historical dataset (2020–2025) and a forward projection that assumes a compound annual growth rate (CAGR) of 6.55% across the forecast window. In simple scale terms, the market expanded from USD 3,250 Million in 2020 to USD 4,500 Million in 2025 and, under our baseline model, approaches USD 7,017 Million by 2032.
Ship-specific Display Market
Why 2026 is a Strategic Inflection Point
Several converging forces make 2026 the year when strategy becomes execution for hermetic packaging suppliers, semiconductor OEMs and systems integrators:
Vitamin K2 Market
- Technology-driven demand: Continued miniaturization, the thermal and reliability demands of high‑power AI accelerators, and expansion of mmWave RF devices are increasing the technical bar for hermetic solutions.
- Regulatory and qualification pressure: High‑reliability sectors — aerospace, defense and medical — continue to require MIL‑STD and Class H/K level qualifications, elongating time‑to‑market and raising the cost of design changes.
- Supply‑chain resilience and geopolitics: Onshoring initiatives and industrial policy measures aimed at securing critical semiconductor supply chains are reshaping investment incentives for domestic hermetic package capacity.
- Materials and thermal engineering: Adoption of advanced materials (for example AlSiC for thermal management and multilayer ceramic cores to reduce warpage) is shifting supplier specializations and BOM economics.
For 2026 planning, these dynamics translate into specific boardroom priorities: accelerate qualification programs for next‑generation packages, protect roadmap timelines from supplier concentration risk, and prioritize design for hermeticity early in the silicon/package co‑development cycle.
Fresh Onions and Shallots Market
Market Trajectory: What the Numbers Mean for Decision Makers
Our base‑case projection (CAGR 6.55%) embodies a market that is expanding steadily rather than exploding. That growth profile creates a different set of strategic choices than a rapidly hyper‑growing market: suppliers and OEMs must synchronize capacity investments with medium‑term demand certainty, avoid overbuild in narrow subsegments, and carve out higher‑margin niches through specialty materials, qualification services and design‑for‑reliability offerings.
- Capacity planning: Given the moderate but persistent growth trajectory, incremental capacity additions that emphasize flexibility (modular lines, multi‑material process capability) are preferable to single‑purpose greenfield plants.
- R&D and IP: Investing in material science (ceramics, glass‑to‑metal seals, AlSiC composites) and process IP that reduce qualification cycles will yield outsized returns in high‑reliability markets.
- Commercial models: Value‑added services — qualification partner programs, accelerated testing, and custom build‑to‑print options — create differentiation in a market where commoditization pressure exists in standard form factors.
Full segmented demand curves by region, material and application are included in the full report; intentionally, this briefing omits those granular splits to drive direct engagement with the source material for procurement and strategy teams building business cases.
What the Full Report Delivers — Practical, Actionable Tools
We designed the report for use in 2026 planning cycles. Key deliverables include:
- Quantitative demand model (2020–2032) with scenarios (baseline, upside, downside) and sensitivity levers to test price, qualification time, and adoption rates for new materials.
- Supplier scorecards and capability maps assessing process breadth (ceramic HTCC, glass‑to‑metal, AlSiC brazing, molded ceramic), qualification throughput, and geopolitical supply‑chain exposure.
- Go‑to‑market playbooks for suppliers targeting aerospace/defense, medical and AI/high‑power markets — including sales motion, certification roadmaps and sample‑to‑production timelines.
- CapEx prioritization and ROI templates calibrated for the industry’s unit economics and lead‑time realities.
- Regulatory compliance matrix and accelerated qualification checklists for MIL‑STD and Class H/K pathways.
- Design‑for‑hermeticity best practices and yield optimization guidance for packaging engineers collaborating with fab partners.
These deliverables are explicitly practical — designed to be imported into procurement RFPs, product development Gantt charts and board‑level capital allocation models.
Competitive Landscape: Strategic Profiles and Implications
The market comprises a mix of material specialists, vertically integrated fabricators and niche engineered‑product companies. Our competitive analysis covers a representative set of leaders and innovators; the full report contains extended company profiles and comparative scorecards. Selected strategic observations follow:
- SCHOTT AG (Mainz, Germany) — Strength: deep expertise in hermetic microelectronic packages and hybrid solutions. Strategic implication: well‑positioned to lead cross‑border programs where integrated optical/glass solutions are required; prospective partners should evaluate SCHOTT for co‑development where glass hermeticity is a differentiator.
- AMETEK Inc. (Aegis / Hermetic Seal) (USA) — Strength: glass‑to‑metal seals and flatpack heritage for defense/aerospace. Strategic implication: a natural supplier for programs requiring long lifecycle support and high‑reliability traceability; consider long‑term supply agreements to secure capacity for defense contracts.
- Kyocera Corporation (Japan) — Strength: multilayer ceramic hermetic packages and recent commercialization of multilayer ceramic core substrates to mitigate warpage. Strategic implication: semiconductor OEMs pushing advanced packaging (AI and high‑power) should evaluate Kyocera as a materials partner to solve warpage and co‑packaging thermal challenges.
- Electronic Products Inc. (EPI) (USA) — Strength: vertical integration across HTCC ceramic and glass‑to‑metal hermetic processes. Strategic implication: attractive partner for OEMs seeking single‑source qualification and shorter supply chains; useful in onshoring strategies.
- Complete Hermetics (USA) — Strength: bespoke hermetic packages and a recent product refresh emphasizing RF, MEMS and power applications. Strategic implication: ideal for prototyping and low‑volume high‑mix programs where customization and rapid iteration matter.
- CPS Technologies Corporation (USA) — Strength: AlSiC hermetic solutions with thermal management focus. Strategic implication: suppliers and OEMs targeting high‑power modules should assess CPS for thermal subsystem integration.
- StratEdge Corporation (USA) — Strength: fully hermetic molded ceramic packages optimized for microwave/mmWave up to ~18 GHz. Strategic implication: positioned to capture share from 5G/6G infrastructure and automotive radar programs.
- Materion Corporation (USA) — Strength: materials and lid covers, braze alloys essential to hermetic supply chains. Strategic implication: an upstream lever for manufacturers seeking material differentiation or supply security.
- Teledyne Technologies (incl. Micross) (USA) — Strength: system‑level assembly and hermetic packaging for space and medical. Strategic implication: a partner of choice where turn‑key assemblies and traceability are mandatory.
Across this competitive set, our analysis highlights two strategic playbooks that consistently outperform: (1) specialization in a narrowly defined reliability or frequency niche combined with accelerated qualification services, and (2) horizontal integration across materials and assembly to reduce vendor count for high‑assurance programs.
Risks, Scenarios and Strategic Responses
Key risks that should influence 2026 capital and partnership decisions include:
- Raw material volatility and single‑source dependencies (e.g., specialty alloys and composites used for thermal management).
- Qualification timeline overruns driven by stricter MIL‑STD/Class H/K testing and lengthening aerospace/space certification cycles.
- Geopolitical shifts that incentivize onshoring, altering comparative cost structures and creating short‑term capacity squeezes.
We model three scenarios in the full report: a baseline (CAGR 6.55%), an upside where defense/AI acceleration pushes near‑term adoption, and a downside where substitution and longer qualification drag growth. For corporate planning, we recommend stress‑testing financial models against the downside for procurement lead times and the upside for capacity constraints to avoid being caught undercapacity or overleveraged.
How to Use This Intelligence in 2026 Planning
Leaders assembling 2026 budgets should treat hermetic packaging not as a commodity line item but as a strategic node that affects product reliability, time‑to‑field and program margins. Practical steps we recommend this planning season:
- Start qualification conversations now: move early into qualification lanes with at least two suppliers to shorten contingency lead times.
- Adopt modular capacity investments: prefer flexible investments that can be redeployed across materials and form factors.
- Negotiate outcome‑based contracts: link pricing to yield and qualification milestones to align supplier incentives.
- Invest in co‑engineering: internal packaging and reliability engineers should be embedded with supplier teams during prototype stages.
Next Steps — Accessing the Full Intelligence
This briefing is intentionally concentrated on strategic implications and programmatic actions; the full PW Consulting report contains the granular market tables, regional and application splits, comprehensive company scorecards and the downloadable demand model used to generate our forecasts. If your 2026 planning requires vendor shortlists, supplier risk heat maps, or the scenario model exported to your financial templates, the full report and data packs are available through PW Consulting’s market research portal.
For boards, procurement committees and R&D leaders entering the 2026 planning season: hermetic packaging will not be a back‑office detail. It is a determinative factor in program timing, reliability and total cost of ownership. Our analysis provides the calibrated market view and tactical toolset to convert growth into profitable, defendable market share — but the specific segmentation tables and supplier benchmarking you need to operationalize these recommendations are held in the full report.
Contact PW Consulting to arrange a briefing of the full dataset, request customized seg‑by‑application scenarios, or commission a tailored supplier due‑diligence engagement calibrated to your program timelines.
For detailed analysis of this topic, please visit the official page: Hermetic Packages for Semiconductor Component Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Tuberculosis Therapeutics Market Poised for 5.82% CAGR Through 2026–2032
By pmarketresearch, 2026-08-18
Worldwide Tuberculosis Therapeutics Market: Strategic Intelligence to Shape 2026 Decisions
PW Consulting’s new market intelligence brief for the Worldwide Tuberculosis (TB) Therapeutics Market synthesizes clinical, commercial, and policy dynamics into an operational playbook for 2026. Anchored on a 2025 base year assessment and our 2026–2032 forecast, the study projects steady expansion underpinned by incremental uptake of shorter, all-oral regimens, generic entry following patent expirations, and sustained donor and government demand for scalable treatment pathways. The market is forecast to grow at a compound annual growth rate (CAGR) of 5.82% over the projection window—gestures toward material opportunity across originators, generics manufacturers, public health procurers, and investors while also flagging acute access and funding risks that will shape winners and losers in the next 18 months.
Worldwide On-Demand Delivery Software Market
Why this report matters for 2026 strategic choices
-
Actionability: The report translates epidemiology and clinical pipeline trends into commercially actionable scenarios—pricing and reimbursement sensitivity models, product prioritization matrices, and regulatory-readiness checklists targeted at the 2026 decision calendar.
Worldwide On-Line Analytical Processing (OLAP) Business Intelligence Consulting Services Market -
Timing: Several catalytic events converge in and around 2025–2026 (regulatory approvals, patent expiries, late-stage trial readouts). Our analysis maps these inflection points to concrete business actions—e.g., accelerated generic launches, supply-chain hedges, or licencing negotiations—with quarter-by-quarter decision triggers for 2026.
Construcion Machinery Slip Rings Market -
Risk-weighted returns: We provide risk-adjusted revenue scenarios and portfolio impact assessments to help executives calibrate R&D spend, manufacturing scale-up, and M&A activity in an environment where clinical efficacy, access policy, and donor funding can pivot value rapidly.
-
Competitive clarity without spoiling the playbook: The brief demonstrates deep competitor and pipeline insight to inform negotiations and partnership targets, while preserving full granular segment tables and price-sensitivity models to drive readers to the source for transaction-level intelligence.
Macro picture: growth, concentration and what they mean
Built on a 2025 base and extrapolated through 2032, the market outlook indicates consistent expansion at roughly a mid-single-digit CAGR. This trajectory reflects a balance between growing demand for treatment of drug-resistant forms of TB, the adoption of WHO-recommended shorter all-oral regimens, and countervailing pressures from donor funding gaps and price erosion as generics enter key markets. Market concentration metrics point to a moderately consolidated landscape (top-three and top-five firm concentration indices are material), implying that strategic moves by a small set of global and regional players will materially influence pricing, supply, and therapeutic mix across 2026.
Clinical and regulatory inflection points to watch in 2026
-
Late-stage pipeline catalysts: Clinical advancement of novel agents and regimen trials can accelerate transitions from long multi-drug treatments to shorter, all-oral courses. The market brief provides a calibrated view of which investigational assets are most likely to change standard-of-care by 2026–2028 and what that will mean for incumbent portfolios.
-
Patent expiries and generic entry: Key originator patents are reaching expiry windows that permit rapid generic entry in multiple jurisdictions. Our analysis estimates the likely timing and pricing impacts of such entries and models survival curves for branded volumes under different access scenarios.
-
Regulatory approvals and guideline uptake: WHO regimen recommendations and national guideline updates will be the proximate drivers of procurement cycles. The report links clinical readouts and approvals to expected adoption timetables in donor-funded and self-financed markets—information essential for planning 2026 manufacturing and tender participation.
Competitive landscape—who does what and where strategy matters
The market is characterized by a mix of international originators, specialized non-profits, and a robust generics manufacturing base concentrated in certain emerging-market hubs. Our strategic profiles synthesize each player’s commercial positioning, pipeline exposure, manufacturing footprint, and access strategies to identify realistic partnership and competitive threats for 2026:
-
Large originators with proprietary assets: Players that commercialize newer therapies for drug-resistant TB are positioned to capture premium pricing in the near term, but face erosion risk as patents lapse and generics scale. Their strategic options include licensing, voluntary technology transfers, and targeted price differentiation to preserve value while supporting access commitments.
-
Non-profit developers and regimen innovators: Organizations developing shorter, all-oral regimens occupy outsized influence over standard-of-care shifts. Their trial readouts and policy advocacy will directly affect demand for both branded and generic products.
-
Generics manufacturers and API suppliers: A dense set of manufacturers that supply first- and second-line medicines—and crucial APIs—form the backbone of global supply. Their ability to scale, maintain quality standards, and secure API supply will determine who can rapidly capture market share post-patent expiry.
For decision-makers, the competition analysis in the brief flags where collaboration (e.g., product donation, pooled procurement, co-manufacturing) is strategically superior to head-to-head competition in 2026—especially when tender size, regulatory complexity, and procurement timelines are factored in.
Policy, funding and access constraints that will shape 2026 outcomes
Policy and funding considerations are central to any commercial plan for TB therapeutics. The global funding gap for TB prevention, diagnosis and treatment remains significant versus stated targets; constraint in available resources will moderate price tolerance and increase the importance of cost-per-cure economics. The report connects macro funding shortfalls and treatment success rate trends to procurement behavior and donor strategy, helping firms anticipate demand shocks and design adaptive pricing and access plans.
Practical deliverables included in the report
-
Scenario-based revenue models: Multiple demand scenarios with sensitivity to regimen adoption, pricing, and procurement pathways—ready to be adjusted with company-specific inputs.
-
Regulatory and guideline assimilation: A timeline that maps clinical trial milestones to expected WHO and national guideline updates, with suggested regulatory engagement playbooks.
-
Manufacturing and API risk matrix: Supplier concentration analysis, quality-certification heatmaps, and contingency strategies for API disruptions—structured for contract manufacturing decisions in 2026.
-
Commercial go-to-market blueprints: Tender-entry strategies, differentiated pricing frameworks for donor-funded vs. private-pay segments, and partnership archetypes optimized for scale and access.
-
M&A and partnership screeners: Targets and transaction rationales, with quick-read investment cases and downside scenarios to support board-level deliberations.
-
Stakeholder engagement playbooks: Communications and advocacy templates for working with national programs, donors, and civil society to accelerate uptake while managing reputational risk.
Recommended 2026 decision roadmap
We recommend that leadership teams align a set of prioritized actions across three horizons to capitalize on the 2026 inflection landscape:
-
Near-term (Q1–Q4 2026): Lock in supply and regulatory pathways for high-priority products; commence price and access negotiations in markets where guideline updates are imminent; formalize technology-transfer or licensing agreements to prepare for generic competition.
-
Medium-term (2026–2028): Scale manufacturing capacity tied to demand scenarios, execute M&A or strategic partnerships to shore up API supply, and invest selectively in registrational studies supporting regimen indications that map to WHO-recommended treatment algorithms.
-
Longer-term (through 2032): Maintain optionality in R&D pipelines for next-generation molecules while building enduring relationships with procurers and health systems to capture value from regimen shifts and programmatic scale-ups.
How leading organizations will use this intelligence
-
Originators: To decide between defensive price strategies versus open-licensing models and to prioritize geographic registration plans aligned with guideline updates.
-
Generics manufacturers: To time capacity investments and pursue WHO prequalification and procurement partnerships; our models help determine how quickly price competition will compress branded margins post-patent expiry.
-
Donors and purchasers: To model cost-per-cure trade-offs across regimens and to design pooled-procurement vehicles that maximize purchasing power while ensuring supplier diversity.
-
Investors and M&A teams: To screen targets with strategic API positions, regulatory filings, or access partnerships that de-risk near-term revenues despite market transitions.
Where the “trailer” leaves you and why you should consult the full report
This article outlines the strategic implications and action agenda that PW Consulting’s full report provides in operational detail. To preserve proprietary transaction-ready analytics we have intentionally withheld granular segment tables and price-point matrices from this preview. The full report contains the complete dataset, detailed regional and disease-type segmentation, supplier concentration by molecule and API, and downloadable scenario models that can be run with client-specific inputs—tools essential for any organization making binding commercial or capital-allocation decisions in 2026.
Next steps
-
If you are preparing procurement calendars, manufacturing investments, or M&A activity for 2026, begin with a scenario workshop: use our models to stress-test your portfolio under the three demand and funding trajectories we outline.
-
Engage early with policy stakeholders to anticipate guideline adoption timelines; regulatory and procurement timing will be the decisive variables for revenue realization in 2026–2027.
-
Contact PW Consulting for a tailored briefing and access to the full dataset and interactive financial models that underpin these conclusions.
PW Consulting’s Worldwide Tuberculosis Therapeutics Market report is designed to convert epidemiology and pipeline momentum into crisp strategic decisions. For organizations that must act in 2026, the difference between opportunistic positioning and reactive shortfall will be determined by the quality of scenario planning and the speed of execution—both are front and center in our full deliverable.
For detailed analysis of this topic, please visit the official page: Worldwide Tuberculosis Therapeutics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide C5 Resin Market to Rise from USD 2,860 Million in 2025 to USD 3,794 Million by 2032 at a 4.12% CAGR
By pmarketresearch, 2026-08-18
Worldwide C5 Resin Market: Strategic Imperatives for 2026 — PW Consulting Preview
As companies prepare capital allocation, procurement realignment, and product strategy for 2026, PW Consulting publishes an executive preview of our forthcoming Worldwide C5 Resin Market report. Our analysis shows the global C5 resin market—measured on a USD million revenue basis—moving from an estimated USD 2,860 million in the 2025 base year toward roughly USD 3,794 million by 2032, representing a compound annual growth rate (CAGR) of approximately 4.12% across the 2026–2032 forecast window. This trajectory reflects steady, commercially relevant growth driven by adhesive tackifier demand, evolving rubber compounding needs, and paint & coating formulations shifting toward engineered hydrocarbon solutions.
Agriculture Accounting Software Market
Why this report matters to 2026 decision-makers
-
Actionable clarity in a period of structural change: Many procurement and strategy teams enter 2026 confronting regional supply imbalances and regulatory uncertainty. Our report synthesizes supply-side moves, feedstock trends, and trade policy impacts into decision-ready insights for sourcing, inventory policy, and regional footprint planning.
Bone Resorption Inhibitors Market -
Investment screening and M&A prioritization: With a moderately concentrated supplier base at the top and a fragmented second tier, the landscape is ripe for strategic bolt-on acquisitions, joint ventures, or capacity redeployment. We show which asset types and geographies will deliver the most defensive value under three downside scenarios.
Worldwide Supply Chain Cost-To-Serve Analytics Software Market -
Commercial optimization for formulators and converters: For OEMs and adhesives/rubber formulators, the report provides an applied toolkit—tackifier substitution roadmaps, cost-to-performance matrices, and risk-weighted supplier scorecards—that reduce adoption friction and accelerate qualification cycles.
Market dynamics shaping the 2026 agenda
-
Supply rebalancing and regional flow shifts: Recent industry events have accelerated regional imbalances. North American hydrogenated resin line rationalization has pushed the region toward increased dependence on imports, while Asia continues to add new resin-making capacity. These flows are being reshaped by both commercial choices and policy instruments.
-
Trade and tariff noise: Targeted trade measures remain a material influence on global trade patterns. Ongoing Section 301 tariffs and the partial unwinding of broader controls in 2026 have altered flows and created near-term arbitrage opportunities—important for procurement teams evaluating supplier diversification versus localized stocking.
-
Feedstock and cost stability: C5 feedstock availability, derived from naphtha and cracker streams, exhibited relative price stability in late 2025. That calm provides a window for forward procurement contracts and structured hedges, but volatility can re-emerge if cracker utilization or heavy petrochemical maintenance cycles change.
-
Domestic capacity growth in Asia: New lines and brownfield expansions in Asia are recalibrating the global cost curve and delivery lead times. For buyers, the strategic question is whether to lock in long-term supply from incumbent integrated suppliers or shift to emerging producers that are scaling quickly.
-
Product mix and formulation trends: Demand for higher-performance and hydrogenated variants continues within specialty adhesives, pressure-sensitive formulations, and advanced rubber compounds. That trend raises the bar for quality- and specification-driven supply chains and supports premiumization of certain resin grades.
Competitive landscape: players, strategic moves, and implications
-
Eastman Chemical Company (USA) — A well-capitalized supplier with a broad portfolio of aliphatic and hydrogenated C5 resins. Eastman’s integrated position and technical service capability make it a preferred strategic partner for adhesive formulators seeking rapid scale-up and global technical support.
-
Kolon Industries, Inc. (South Korea) — A leading regional producer with deep capabilities in high-purity C5 resins and hydrogenated grades. Kolon’s investments in higher-purity product lines signal an intent to capture specialty pockets where performance and consistency command premium pricing.
-
ExxonMobil Corporation (USA) — A major traditional supplier whose selective shutdowns and portfolio adjustments have immediate market ripple effects. Recent capacity rationalization in hydrogenated lines has contributed to upstream sourcing challenges for North American buyers, underscoring the need for contingency planning.
-
Zeon Corporation & Arakawa Chemical (Japan) — Technology-focused producers that serve high-performance adhesive and elastomer markets; their product breadth supports formulators requiring tight grade control and tailored tackifier performance.
-
Neville Chemical, Cray Valley (TotalEnergies), and a cluster of Chinese producers — These firms complete a competitive tapestry of global incumbents and agile regional suppliers. China-based manufacturers have visible momentum in expanding scale and global reach; this has implications for pricing dynamics and lead-time optimization.
-
Market concentration signals — The market exhibits moderate top-tier concentration, with the three largest producers capturing a meaningful share but leaving substantial room for mid-sized and regional suppliers to compete. This structure increases the value of differentiated service models and localized supply guarantees.
Recent developments that will matter in 2026
-
Regulatory and corporate restructuring in Asia has prompted portfolio reviews among downstream chemical players; consolidation and strategic repositioning in Korea and Japan are affecting regional feedstock allocations and partnering strategies.
-
Targeted capacity expansions and brownfield upgrades by established players are creating differentiated capability clusters—some focused on high-purity specialty resins, others on broad commercial grades—changing the competitive match-up across applications.
-
Significant plant line closures for hydrogenated grades in North America have altered net trade balances, emphasizing the importance of import strategies, tolling arrangements, and safety-stock policies for 2026.
What the PW Consulting report delivers — practical modules
-
Market sizing and validated forecast model (2020–2032) with scenario toggles: our financial model is built in a way that allows executives to stress-test demand elasticity and price pass-through under alternative macro cases.
-
Segment diagnostics and opportunity mapping: deep dive playbooks for resin types (aliphatic, copolymer, hydrogenated) and end-use clusters that identify margin pools, qualification timelines, and go-to-market mechanics.
-
Supplier heatmaps and risk-adjusted sourcing templates: a procurement-ready framework combining lead-time volatility, quality fit, regulatory exposure, and commercial flexibility.
-
Trade-flow and tariff impact analysis: dynamic routing scenarios that quantify shifts in logistics cost and landed price under prevailing trade measures and alternative tariff outcomes.
-
Technical substitution and product migration guides: stepwise plans to migrate formulations between resin grades with minimal requalification cycles and cost disruption.
-
M&A, JV and capex playbooks: acquisition targets, integration checklists, and capex prioritization matrices tailored to buyers and strategic investors active in the hydrocarbon resin ecosystem.
Recommended 2026 strategic actions — five high-impact moves
-
Formalize dual-sourcing for critical grades: prioritize at least one regional and one global supplier to mitigate delivery shocks from unexpected plant outages or policy shifts.
-
Implement a short-duration forward purchasing program tied to cracker utilization indices: take advantage of the current feedstock calm to secure favorable terms without overexposing balance sheets.
-
Prioritize qualification of hydrogenated and high-purity variants for premium end-markets: these grades offer better margin defensibility where performance matters.
-
Reassess inventory strategy in light of trade frictions: shift from pure cost-minimization to resilience-weighted inventory targets for facilities serving multiple plants or markets.
-
Use M&A/JV selectively to obtain quick access to local capacity or downstream channel control—but only against rigorous IRR and integration metrics provided in our acquisition playbook.
How to use the full report
This release is intended as a strategic preview: it articulates the high-level market trajectory, the levers that matter in 2026, and the playbook executives should adopt to protect and grow margin. The full PW Consulting Worldwide C5 Resin Market report contains the granular segment-level data, regional and application splits, supplier scorecards, and downloadable financial models that boards, strategy teams, and procurement leaders will find indispensable when making binding 2026 decisions. We deliberately withhold the detailed subsegment datapoints in this preview to ensure that organizations seeking immediate operational guidance consult the complete dataset and model hosted on our site.
Conclusion
The C5 resin market in 2026 is neither a classic boom narrative nor a stagnant commodity story—it is a slowly expanding, structurally shifting market where the winners will be those that pair technical differentiation with supply-chain resilience. PW Consulting’s report equips executives with the foresight and the operational tools required to convert the coming changes into competitive advantage. For the authoritative dataset, scenario models, and supplier-level playbooks, access the complete Worldwide C5 Resin Market report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide C5 Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Recycled Containerboard Market Valued at USD 146.5 Billion in 2025, Set to Expand at a 4.69% CAGR Through 2032
By pmarketresearch, 2026-08-18
Recycled Containerboard Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Report
PW Consulting today releases a comprehensive market research briefing on the global Recycled Containerboard market, purpose-built to inform the strategic decisions of corporate leadership and investors for 2026. The report synthesizes a multi-year view of supply, demand, policy and feedstock dynamics and translates those into operational playbooks, capital-allocation guidance and near-term scenario options. This press briefing presents the report’s strategic value proposition, high‑level market trajectory and the decision levers that business leaders should prioritize this year. For full segmentation, granular regional and application breakdowns, and proprietary model outputs, please consult the full report.
General Metal Finishing Solutions Market
Market Snapshot: Growth Measured, Transition Underway
Our analysis shows the recycled containerboard market as a large, steadily expanding sector. By our base year (2025) the market reached approximately USD 146.5 Billion and the forecast envelope points to continued expansion at a compound annual growth rate of roughly 4.69% through 2032, taking the market to about USD 201.9 Billion by the end of the forecast period. That trajectory underlines a structural growth theme driven by packaging substitution toward recycled fibre, rising e‑commerce-related packaging volumes, and regulatory pushes toward higher recycled content.
Car Sharing App Market
However, aggregate growth masks two critical realities that will shape 2026 strategy. First, feedstock and manufacturing ecosystems remain cyclical and regionally differentiated: recovered paper availability and pricing volatility can compress margins quickly, and second, regulation and buyer-specification shifts are increasingly decisive for market access and premium positioning. The report marries the macro growth narrative with these operational frictions so decision makers can translate top‑line opportunity into executable near‑term plans.
Precious Metal Evaporation Materials Market
Why the 2026 Planning Cycle Is Different — and What to Do About It
- From volume to value: As recycled containerboard becomes a default choice for many corrugated applications, margin capture increasingly depends on product-performance differentiation (weight, printability, flatness) and supply-security assurances rather than pure tonnage growth. Executive teams should realign commercial incentives and investments to monetize differentiated recycled grades.
- Regulatory inflection points are immediate: Extended Producer Responsibility (EPR) frameworks are moving from proposal to implementation in multiple jurisdictions, with some laws now specifying significant minimum post‑consumer recycled content. This changes procurement math for brand owners and creates new demand signals for manufacturers who can guarantee compliant content and chain-of-custody documentation.
- Feedstock risk is corporate risk: Recovered paper markets showed signs of rebound in early 2026 after a soft patch in late 2025; even modest swings in OCC availability or price transmission materially impact thin‑margin recycled grades. Procurement, hedging and asset flexibility must be hardwired into 2026 plans.
- Operational tightness coexists with selective capacity expansion: Despite near‑term production variability in some regions, many producers are selectively investing in recycled grades and machine rebuilds. Companies must weigh the long lead times and payback profiles of converted or new recycled machines against the competitive benefit of first‑mover capacity in underserved corridors.
What PW Consulting’s Report Delivers — Hands‑On, Actionable Intelligence
Our research is designed to be operational: not an academic forecast but a decision‑support tool. Key deliverables inside the report include:
- Proprietary market sizing and a scenario matrix that links macro demand trajectories to feedstock availability and pricing sensitivities.
- Commercial playbooks for sellers and buyers — pricing architecture, specification migration paths, and supply‑contract templates tailored for recycled fibre supply chains.
- Capital allocation frameworks for mill owners and converters: break‑even mappings, retrofit prioritization, and greenfield vs conversion decision trees with IRR and payback sensitivities under multiple feedstock and price paths.
- An M&A and JV playbook identifying strategic pockets (tech-enabled deinking, local closed‑loop models, high‑brightness recycled liner) and the financial profile of value creation levers that acquirers should target.
- Operational benchmarking and a plant‑level diagnostic toolkit covering yield, fibre loss, water and energy intensity, and quality‑control levers that materially affect paper performance for customers.
- Regulatory readiness tools: a compliance checklist for EPR regimes, product labeling implications, and supplier traceability templates to support procurement teams and sustainability reporting.
Each section is supported by primary interviews with mill operators, converters and major buyers, plant‑level audits and a bottom‑up demand model calibrated to 2020–2025 historicals and 2026–2032 forecast scenarios.
Competitive Landscape: Who’s Competing on What
The recycled containerboard market remains moderately fragmented: global leadership is distributed among vertically integrated pulp and paper majors, regional specialists, and independent recycled-only operators. Competitive advantage today is built on three capabilities — consistent recycled feedstock procurement, product performance engineering (weight, strength, printability), and integrated closed‑loop solutions for large buyers.
- International Paper — A major global participant with established recycled liner and fluting grades in its EMEA footprint; IP’s play emphasizes high‑performance lightweight grades that enable lower board weights without sacrificing performance.
- ND Paper — Focused on reliable strength and print quality for demanding packaging uses; ND’s asset base targets consistency as its primary commercial differentiator.
- Stora Enso — Highlights 100% recycled fibre testliner offerings with a product strategy around structural performance, flatness and low grammage for e‑commerce and industrial packaging customers.
- Cascades — Emphasizes a full recycled lineup across white and brown grades, pursuing both sustainability claims and surface quality improvement to capture premium applications.
- DS Smith — Positions high‑brightness 100% recycled white liners for FMCG and food applications where printability and visual appeal command price premiums.
- Kruger, New Indy, Pratt and others — Each occupies regional niches or scale positions: Kruger and New Indy have early mover recycled histories in North America; Pratt emphasizes closed‑loop systems; independent suppliers often lead on cost and customized services for localized demand.
- Mondi — Recently brought new recycled‑focused capacity online in Italy; the company’s approach illustrates how targeted capital projects can quickly alter regional supply balances for high‑quality recycled testliner and fluting.
Our competitive analysis goes beyond company positioning to evaluate capital intensity, technology adoption (deinking, refining, optimization), customer mix, and contractual exposure to feedstock and finished‑goods volatility. That analysis provides an M&A and partnership heat map for 2026 priorities.
Recent Industry Signals to Watch in 2026
- Several producers have brought recycled-dedicated machines and upgrades into production in the past 18 months, signaling continued industrial commitment to 100% recovered fibre offerings in priority regions.
- Procurement teams are reacting to recovered paper market dynamics: early 2026 saw a modest rebound in recovered paper availability and regional price stabilization after late‑2025 softness. Procurement strategies should incorporate shorter contract cycles and optionality clauses for feedstock supply.
- Regulatory change is accelerating buyer requirements. New EPR schemes and state‑level mandates are driving brand owners to demand verifiable recycled content and chain‑of‑custody documentation from suppliers; some jurisdictions have set explicit post‑consumer recycled content thresholds that will alter procurement specifications.
- Production metrics in some markets reflect a 2025 year‑on‑year reduction in output even as operating rates stayed high; this underlines the role of maintenance cycles and feedstock shortages in near‑term availability.
Practical Strategic Choices for 2026
Executives should treat 2026 as a year for tactical repositioning and capability building rather than only capacity race expansion. Key actions we recommend:
- Implement a three‑tier procurement strategy: secure core feedstock through anchor contracts, maintain a flexible spot overlay to capture opportunistic supply, and invest in or partner on local collection and sorting where economics permit.
- Prioritize product R&D on surface quality and weight efficiency to expand addressable applications and defend margins against commodity downward pressure.
- Stress‑test capital projects against three feedstock and price scenarios and incorporate regulatory compliance timelines into capex phasing to avoid stranded asset risk.
- Use the report’s M&A heat map to identify bolt‑on acquisitions that deliver either geographic feedstock security or product diversification (e.g., white‑top recycled liners or high‑brightness solutions for food packaging).
- Operationalize EPR readiness: upgrade labelling, chain‑of‑custody systems and customer reporting to convert regulatory compliance into a commercial differentiator.
Conclusion — The Strategic Edge in 2026
The recycled containerboard market is no longer a back‑office sustainability narrative; it is a core commercial battleground with clear profit pools for firms that can integrate feedstock security, product performance and regulatory compliance. PW Consulting’s report equips executive teams with the scenario analysis, operational templates and competitive intelligence required to make defensible 2026 decisions — from procurement and plant investments to M&A and customer contracts.
This briefing is a preview designed to show the depth of analysis and practical outputs the full report contains. To access detailed regional and application segmentation, proprietary pricing and margin models, and the complete suite of implementation tools referenced here, please visit PW Consulting’s report page and download the full Recycled Containerboard Market study.
For detailed analysis of this topic, please visit the official page: Recycled Containerboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Industrial Press Machine Market to Expand at a 5.18% CAGR Through 2032
By pmarketresearch, 2026-08-18
PW Consulting: Strategic Brief — Worldwide Industrial Press Machine Market (2026 Outlook)
PW Consulting today publishes a strategic briefing drawn from our new Worldwide Industrial Press Machine Market report — a practitioner-focused intelligence asset designed to shape capital allocation, product strategy, and M&A decisions through 2026 and beyond. Using 2025 as the analytical base year, our global market system is tracked in USD (Million) with a projected compound annual growth rate (CAGR) of 5.18% across the forecast horizon. The market expanded meaningfully through 2020–2025 and, under our central scenario, progresses toward a materially larger installed base and serviceable market by 2032.
Corporate Travel Booking Platforms Market
Why this matters for 2026 corporate strategy
-
Timing capital: With moderate, steady growth and pockets of accelerated investment, 2026 is a year where the sequencing of capital projects — greenfield presses versus retrofit and automation programs — will determine total cost of ownership and payback periods.
Electric Train Battery Market -
Input-cost sensitivity: Steel-market dynamics and trade policy introduced higher near-term uncertainty in 2025. Organizations that proactively hedge raw-material exposure and redesign supply chains to reduce steel-intensive content will protect margins.
Worldwide Electro-optical Converters Market -
Technology pivot points: The migration to servo-driven systems and integrated automation is no longer niche; it is reshaping buyer selection criteria around precision, energy efficiency, and digital integration.
-
Aftermarket economics: Service, spare parts, and retrofit revenues are becoming essential to sustaining margins as equipment lifecycles lengthen and customers seek guaranteed uptime under tighter production schedules.
What PW Consulting’s report delivers
-
Robust market sizing and forward-looking scenario analysis, calibrated to market events through the 2025 base year and projecting to 2032 with multiple demand scenarios and sensitivity cases tied to raw-material and trade-policy assumptions.
-
Practical go-to-market playbooks for OEMs and component suppliers — from product positioning and pricing levers to channel design, local-assembly thresholds, and retrofit service bundling.
-
Procurement and supply-chain stress tests, including break-even analyses for vertical integration versus global sourcing, and supplier concentration mapping to identify single points of failure.
-
Competitive benchmarking with vendor scorecards across engineering capability, automation integration, aftermarket footprint, and balance-sheet resilience.
-
A curated M&A pipeline and diligence checklist highlighting acquisition targets likely to accelerate access to key end-markets, digital capability, or regional manufacturing scale.
-
Operational playbooks for manufacturers and end-users — CAPEX prioritization grids, retrofit vs. replace matrices, and pilot-to-scale templates for automation deployment.
Competitive landscape: who matters and why
The market remains moderately fragmented, with concentration metrics indicating space for scale plays: the top three firms capture a meaningful but not overwhelming share, and the top five firms broaden that concentration band further. This structure creates both opportunity for consolidation and room for specialized players to defend niches.
-
Schuler Group (Göppingen, Germany) — A broad-spectrum supplier of mechanical, hydraulic, and servo presses. Schuler’s global service footprint and deep OEM relationships in high-volume stamping make it a reference player for full-line systems and turnkey lines.
-
AIDA Engineering (Japan) — High-precision mechanical and servo presses oriented to high-speed stamping. AIDA’s engineering reputation positions it well where cycle time and die-life economics dominate procurement choices.
-
Amada (Japan) — Known for sheet-metal forming equipment and automation, Amada’s product breadth in punching and bending complements press makers who need to offer integrated cell solutions to contract manufacturers.
-
Komatsu Press (Japan) — Strong in heavy industrial stamping and automation-enabled solutions; Komatsu’s integration of presses with higher-tier material handling continues to win large-scale industrial projects.
-
Beckwood Press Company (St. Louis, USA) — Specialist in custom-engineered hydraulic and servo-electric presses. Beckwood is attractive for OEMs needing bespoke capabilities for composites, molding, or specialty forming.
-
Pacific Press Technologies (USA) — Focused on North American metal forming needs with a reputation for reliable hydraulic and straight-side presses and a strong OEM-aftermarket channel.
-
Macrodyne Press (North America) — Heavy-duty hydraulic presses for deep draw and hydroforming; the firm is strategically positioned for large-scale vehicle and industrial applications where scale and force are differentiators.
-
French Oil Mill Machinery Co. (USA) — Longstanding heritage in custom hydraulic presses, particularly in compression molding and rubber applications; an example of how specialized product competence sustains market niches.
-
Ermaksan (Turkey) — Offers CNC hydraulic and servo turret punch presses; presents an alternative for cost-conscious regional buyers seeking modern control systems.
-
Fagor Arrasate (Spain) — Supplies mechanical and hydraulic presses and full stamping lines; notable for turnkey solutions in automotive and appliance segments.
-
Sutherland Presses & Stamtec (USA) — Both bring manufacturing locality and trusted U.S.-made quality, appealing to buyers prioritizing short lead times and domestic support.
Supply-chain and input-cost dynamics shaping decisions in 2026
Two critical, observable forces are shaping supplier economics and pricing strategies heading into 2026. First, raw-material dynamics: steel prices stabilized in the low–mid ranges in mid-2025 and remain a key driver of frame and component costs. Second, trade policy changes — most notably elevated U.S. steel tariffs implemented in 2025 — have created a bifurcated sourcing environment where domestic producers gain pricing support but import-dependent players face higher input costs. Coupled with structural overcapacity in global steel markets, these dynamics argue for differentiated procurement playbooks: tactical hedges for near-term volatility and strategic reconfiguration of BOMs and subassembly sourcing for medium-term resilience.
Technology & product trends that will re-write competitive scorecards
-
Servo and hybrid presses: Adoption is being driven by buyers demanding tighter tolerances, lower energy intensity, and better integration with digital controls. These systems are increasingly the default for precision stamping and higher mix–lower volume production profiles.
-
Automation and Industry 4.0 integration: Press lines are being sold as node-enabled assets — remote diagnostics, predictive maintenance, and line-level optimization are table stakes for premium OEMs and leasing offerings.
-
Modularity and retrofitability: Product families that allow incremental capability upgrades (controls, drives, safety) dramatically improve customer ROI and create recurring aftermarket monetization opportunities.
Actionable takeaways for executives planning 2026
-
Recalibrate CAPEX: Prioritize mixed investments — small pilot projects in servo and automation plus targeted replacement of legacy assets that create bottlenecks.
-
Design supplier risk playbooks: Implement dual-sourcing strategies for critical steel components and evaluate nearshoring of final assembly where tariffs and lead time exposures are material.
-
Monetize installed base: Build service tiers (SLA-backed uptime, condition-based maintenance) to convert fixed-cost installed assets into recurring-revenue streams.
-
Segment go-to-market by capability: Use differentiated sales motions for high-volume automotive stamping versus precision electronics forming; standardize offerings where possible and modularize where necessary.
-
Accelerate partnerships with automation integrators and controls suppliers to shorten time-to-value for buyers and create bundled greenfield and retrofit propositions.
-
Evaluate M&A for capability gaps: Target acquisitions that immediately add digital controls, regional service networks, or material-handling expertise to close visible gaps in competitive scorecards.
Recent market activity and signals
Industry events and product showings continue to validate the market momentum and technology transition. For example, machine builders participated in major manufacturing exhibitions in early 2026 to showcase new forming and press-line integrations — a reminder that OEMs are actively pursuing visibility and order pipelines as end-users refresh assets.
Why PW Consulting’s report is the decision tool for 2026
Our report combines transparent, auditable methodology with practitioner tools: demand-model Excel workbooks, vendor scorecards, stress-test scenarios, and a prioritized action checklist. We balance high-level foresight (macro demand and trade impacts) with hands-on levers (procurement negotiation scripts, retrofit ROI calculators, and go-to-market templates) so that executives do more than understand the market — they act on it.
This briefing intentionally highlights strategic themes and decision-relevant insight while reserving the granular segment tables, regional breakdowns, and line-item supplier economics for the full report and accompanying datasets. Industry leaders and buyers who require the detailed segmentation, downloadable models, and vendor-level financials will find those deliverables in the full PW Consulting publication and Excel annex.
For executives preparing 2026 plans, the choice is straightforward: rely on high-level intuition, or use a field-tested, data-driven playbook that aligns capital, capability, and go-to-market efforts against the real levers that move margin and market share. PW Consulting’s Worldwide Industrial Press Machine Market report delivers the latter.
Contact and access
PW Consulting’s market research and advisory teams are available to present bespoke briefings, workshop CAPEX scenarios, or support vendor diligence. Access to the full report, annex data files, and proprietary models is available through PW Consulting’s publication channels.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Press Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Anti-Radiation Clothing Market to Expand at a 7.03% CAGR During 2026–2032
By pmarketresearch, 2026-08-18
Worldwide Anti-Radiation Clothing Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide Anti-Radiation Clothing Market report (base year: 2025; historical: 2020–2025; forecast: 2026–2032). The global market has expanded from roughly USD 585 million in 2020 to about USD 789 million in 2025 and is forecast to continue growing to an estimated USD 1,266 million by 2032, reflecting a compound annual growth rate of 7.03% over the 2026–2032 forecast window. For executives planning investment, product strategy, or procurement in 2026, these macro trajectories and the practical frameworks we provide are immediately actionable — while the full report contains the granular segmentation tables and decision-grade datasets that support tactical execution.
Bifurcated Covered Stent Market
Why this report matters for 2026
-
Transition point for buyers and suppliers: 2026 is the inflection year where material innovation, regulatory scrutiny, and diversified end‑use demand converge to change procurement and product roadmaps. Our report translates that convergence into discrete, time‑bound actions for R&D, sourcing, and marketing teams.
Worldwide Flip Chip CSP Market -
Investment calibration: with the market growing at a mid‑single-digit CAGR into the early 2030s, capital allocation decisions must balance steady recurring demand (medical and occupational protective apparel) against episodic, higher‑value opportunities (specialty suits for aerospace and emergency response). We show how to size those bets without exposing sensitive client-level data in this briefing.
Worldwide Lip Makeup Market -
Regulation and certification as market enablers: standards and device classifications will determine market access and procurement cycles; alignment with these frameworks is a prerequisite for growth in regulated channels.
Key market dynamics and growth drivers
-
Persistent medical demand and evolving occupational use-cases: healthcare imaging and interventional suites remain steady anchors. Parallel growth is driven by new professional use‑cases where targeted attenuation and lighter garments are required for extended wear.
-
Material-led product differentiation: the shift from traditional lead to lead‑free composites (tungsten, bismuth, antimony blends) is reshaping product performance and user acceptance. These alternatives can reduce garment weight substantially — typically in the 30–50% range versus equivalent lead products — enabling new form factors and new channels.
-
Standards and regulatory gating: internationally recognized standards (e.g., IEC 61331‑1) and device classifications (such as FDA’s treatment of radiation-attenuating garments) continue to be both market levers and barriers; compliance accelerates institutional purchasing while absence of certification constrains access to large buyers.
-
Moderate market concentration: leading players capture a meaningful share of the market, but the industry retains multiple viable niches. Measured concentration metrics indicate room for both consolidation plays and specialist entrants that focus on specific use‑cases or materials.
-
Risk and safety messaging: public health guidance confirming there is no clothing that provides complete protection against all forms of ionizing radiation increases demand for solution‑specific messaging and validated performance claims rather than generic protection claims.
What the full report contains — practical, executable content
PW Consulting’s full market study is designed as a working tool for management teams. Highlights include:
-
Market sizing and forward-looking scenario models: comprehensive base and scenario forecasts (2026–2032) with sensitivity analyses that stress-test demand across regulatory outcomes, raw material price shocks, and adoption curves.
-
Go‑to‑market playbooks: channel strategies for medical, occupational, and specialist aerospace/emergency response buyers; distributor partner profiles; sample procurement RFIs and commercial contracting templates.
-
Technology and material roadmaps: patent landscaping, supplier capability matrices, and a materials cost‑performance dashboard to help product teams prioritize composites and fiber technologies.
-
Regulatory and standards matrix: mapping of global certification requirements, clinical validation protocols, and routes to market for medical device classification versus general protective apparel.
-
Competitive and M&A intelligence: vendor scorecards, capability gaps, strategic fit analyses, and an acquisition target shortlist for buyers seeking inorganic growth.
-
Supply chain resilience playbook: contingency planning for scarce raw materials, logistics stress testing, supplier hedging strategies, and contract clauses to link price and performance.
-
Operational checklists: product validation protocols, testing labs checklist (including IEC-compliant test criteria), and quality management KPIs tailored to protective apparel manufacturing.
Competitive landscape — what leading vendors signal for strategy
The market’s competitive set combines specialist innovators with established medical‑supply manufacturers. A few illustrative company profiles and recent developments are instructive for strategy:
-
StemRad (Israel): a technology‑led innovator focused on selective shielding in high‑risk applications. Their validated AstroRad vest and first‑responder 360 Gamma suit demonstrate how mission‑grade performance claims combined with external validation (e.g., aerospace program certifications) can create premium product lines and open non‑traditional channels.
-
Radiation Protection Products (U.S.): an established medical apparel manufacturer that recently refreshed its product portfolio with lighter, more flexible lead‑free aprons. This kind of iterative product innovation suggests a path for incumbents to defend share through material swaps and ergonomics rather than only price competition.
-
Barrier Technologies (U.S.): a specialist in lightweight designs (Zero‑Gravity portfolio) that uses trade‑show visibility to accelerate adoption among clinicians — a reminder that targeted engagement at professional conferences remains a high‑ROI demand generation tactic.
-
Infab Corporation, MarShield, Ray‑Bar Engineering: these firms represent breadth across medical and industrial shielding, custom composites, and barrier solutions. Their presence underscores fragmentation in product form factors and the opportunity for vertically integrated players to capture higher margins via custom material compounds and contract manufacturing.
Recent proof points — product certifications and new launches — indicate two actionable themes: (1) certification and third‑party validation materially improve procurement momentum in institutional channels; and (2) ergonomics and weight reduction drive adoption among frontline users. Both themes should inform product roadmaps and commercial messaging in 2026.
Strategic implications and recommended priorities for 2026
We recommend a four‑pillar approach for firms planning strategic moves next year:
-
Invest selectively in materials and ergonomics. Prioritize R&D that targets a 30–50% perceived weight improvement via lead‑free composites while maintaining IEC‑level attenuation across target energy bands. Build a prototype and validation timeline that aligns with procurement cycles of major hospital systems and emergency services.
-
Certify early and tell the story. Plan for IEC and, where applicable, medical device registrations. Certification accelerates access to regulated channels and supports premium pricing. Use third‑party validation in all sales collateral for institutional buyers.
-
Design channel plays by buyer archetype. Separate strategies for medical imaging departments, occupational safety buyers, and specialty aerospace/emergency customers. For each archetype, articulate total cost of ownership, training requirements, and lifecycle replacement metrics.
-
Securitize supply chains. Given the reliance on specialized composite inputs and the potential for raw material price volatility, build supplier redundancy, long‑lead inventory buffering, and contractual hedges. Our supplier map and price sensitivity models in the full report make these decisions executable.
KPIs and near‑term signals to monitor in 2026
-
Certification milestones achieved (IEC and applicable national device registrations).
-
Adoption velocity in institutional tenders and number of hospitals/clinics transacting on new lead‑free SKUs.
-
Material cost trends for tungsten/bismuth/antimony blends and announced capacity expansions by composite producers.
-
Competitor product launches and trade‑show visibility (e.g., major radiology conferences) as leading indicators of commercial focus.
Concluding assessment
The anti‑radiation clothing market is no longer a static, commodity domain. It is evolving into a differentiated landscape where materials science, regulatory alignment, and channel strategy determine winners. With the market projected to expand meaningfully from its 2025 base toward the early 2030s and with moderate concentration among leading suppliers, 2026 will reward firms that couple validated product advances with disciplined go‑to‑market execution.
PW Consulting’s full report synthesizes the granular data, validated supplier and buyer intelligence, and tactical playbooks required to execute those moves. This briefing offers the strategic contours — the full dataset, segmentation tables, vendor scorecards, and executable templates are available in the complete study for teams that need to convert insight into 2026 operational plans.
For detailed analysis of this topic, please visit the official page: Worldwide Anti Radiation Clothing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ion Beam Machining Market Poised for 7.85% CAGR, Report Forecasts Robust 2026–2032 Growth
By pmarketresearch, 2026-08-18
Ion Beam Machining Market 2026: Strategic Imperatives for Leaders — PW Consulting Preview
As PW Consulting publishes its flagship Ion Beam Machining Market report, this briefing outlines the high-level implications that senior executives, corporate strategists, and investment committees must factor into 2026 planning cycles. Built on a robust 2020–2025 historical base and a 2026–2032 forecast framework, the analysis projects a resilient expansion trajectory — driven by advanced semiconductor nodes, next‑generation photonics and optics, and intensifying demand for precision materials analysis. Our model anticipates the market to expand from a 2025 base of USD 215.75 Million to a materially larger industry by 2032, reflecting a compound annual growth rate (CAGR) of 7.85% across the forecast horizon. This release is a strategic “preview”: it surfaces the decision‑critical insights and actionable implications while preserving the granular segment-level intelligence for report subscribers.
AI Server Low Dielectric Glass Fiber Market
Why Ion Beam Machining Matters to 2026 Corporate Strategy
Ion beam machining (IBM) technologies — including focused ion beam (FIB), broad ion beam (BIB) and emerging plasma-based ion systems — are now mission‑critical in three strategic domains: advanced semiconductor manufacturing, high-precision optics/coatings, and materials science research & failure analysis. For technology OEMs and capital equipment investors, IBM is less a niche process and more a leverage point for enabling tighter tolerances, higher yields, and new device architectures (e.g., heterogeneous integration, photonic integration, and advanced packaging). The projected mid‑single‑digit to high‑single‑digit CAGR reflects both sustained demand for replacement and retrofit systems as well as a wave of new unit deployments tied to capacity expansions and R&D investments.
Wireless Network Simulator Market
Market Structure and Competitive Dynamics — What Leaders Should Read First
Two structural features define competitive dynamics and should shape boardroom deliberations in 2026:
Engine Compartment Protective Panel Assembly Market
- Consolidation and Concentration: The industry exhibits a moderate level of concentration among the top players, reflecting high technical barriers, IP intensity, and capital requirements. This concentration supports premium pricing for differentiated platforms but also creates acquisition windows for fast‑moving challengers and specialized service providers.
- Platform Diversification: Market leaders are pursuing multi‑technology portfolios — combining FIB, PFIB, and broad ion beam capabilities with software, automation, and service contracts — to capture end‑to‑end value and to reduce cyclicality tied to capex spending patterns of end customers.
Key incumbents profiled in our study exhibit distinct but complementary competitive plays. Some vendors emphasize precision thin‑film and optical coatings; others push integrated FIB‑SEM and high‑throughput failure analysis solutions. Meanwhile, specialized service providers and regional OEMs deploy nimble product programs and local service networks to win aftermarket share.
Recent Strategic Moves That Signal the Next Phase
- Product modularity and platform launches are accelerating: recent modular platforms bring together ion beam and plasma processes onto configurable toolsets, shortening time‑to‑qualification for multi‑process customers.
- Order flows into optical and laser supply chains point to renewed capex activity in select photonics segments, indicating pockets of above‑market growth outside pure semiconductor fabs.
- Broad ion beam tooling for sample preparation and cooling configurations have moved from laboratory staples into higher‑throughput production settings, unlocking new addressable use cases.
These directional shifts are evident in multiple vendor announcements over the past 18 months and are reflected in our scenarios for 2026 planning. For practitioners, the strategic question is not whether to play in ion beam, but how to structure participation — direct OEM play, system rental and service, software and automation, or vertical integration with end‑user fabs and research institutions.
Supply Chain and Technology Risks: What to Monitor Closely
Two risk vectors deserve board‑level attention in 2026:
- Raw material and source dependencies: Traditional FIB tools commonly rely on gallium liquid metal ion sources. This creates potential supply chain vulnerability to gallium availability and price volatility. Companies should stress‑test procurement and consider alternative ion sources or dual‑sourcing strategies where feasible.
- Process artifacts and rework needs: Post‑FIB implantation can introduce surface amorphization and contamination that necessitate follow‑up milling or low‑energy broad ion polishing. Product roadmaps that incorporate downstream mitigation (e.g., argon/xenon polishing, plasma treatments) will offer superior yield and lower total cost of ownership for end customers.
Regulatory and quality frameworks remain exacting — ion beam equipment must meet high‑vacuum and precision manufacturing standards. This reality elevates the importance of validated supply chains, accredited calibration services, and robust documentation for customers operating in regulated sectors.
Strategic Playbook — Four High‑Impact Moves for 2026
From our work with OEMs, fab operators, and private equity clients, the following four moves consistently preserve optionality and maximize upside in an IBM ecosystem growing at ~7.85% CAGR.
- Prioritize modularity and software differentiation: Invest in control software, AI‑driven process recipes, and modular hardware architectures that enable rapid reconfiguration. Software licensing and remote diagnostics materially increase annuity‑style revenue and improve gross margins.
- Pursue targeted M&A and partnership plays: Given the sector’s concentration dynamics, smaller acquisitions or licensing deals can accelerate entry into complementary process domains (e.g., PFIB, deposition/etch hybrids) faster than organic R&D alone.
- Shift to solutions and services: Expand into process development, application labs, and uptime guarantees. Service‑heavy contracts reduce customer capex sensitivity and create sticky long‑term relationships.
- Hedge supply risks and redesign consumable strategies: Secure multi‑year supply agreements for strategic feedstock, qualify alternate ion sources, and re‑engineer consumable lifecycles to reduce single‑supply dependencies.
What Our Full Report Delivers — Practical Tools for Decision‑Making
Our full Ion Beam Machining Market report goes beyond narrative and delivers executable assets that teams can use immediately in 2026 strategy cycles. Highlights include:
- Revenue and unit shipment models with scenario toggles for high/medium/low demand trajectories across the 2026–2032 horizon.
- Competitor scorecards and product roadmaps that benchmark technology readiness, service coverage, and commercialization timelines.
- CapEx and TCO calculators tailored to OEMs and end‑users that quantify payback periods under alternative utilization rates.
- An M&A screening matrix that flags targets by strategic fit, integration complexity, and accretion/dilution sensitivities.
- Supply chain risk heatmaps and mitigation playbooks addressing raw material sourcing, logistics constraints, and regulatory compliance checkpoints.
- Go‑to‑market blueprints for service expansion, including pricing models for subscriptions, uptime SLAs, and application lab commercialization.
- Executive dashboards for board reporting, with pre‑built visualizations for revenue run‑ways, margin scenarios, and capital planning.
Each tool is built to be directly plug‑and‑play within corporate financial models or to be adapted by private equity due diligence teams. While this preview highlights our core recommendations and strategic direction, the granular segmentation analytics, supplier share tables, and downloadable Excel models are gated in the full report to preserve subscriber value.
Competitive Appendix — Vendor Schemes to Watch
Our competitive synthesis profiles leading vendors across several strategic postures:
- Vendors focused on optical and thin‑film process integration are leveraging ion beam sputtering and deposition solutions to penetrate photonics and laser supply chains.
- Firms with integrated FIB‑SEM and plasma FIB roadmaps are capturing high‑value applications in failure analysis and volume imaging, enabling higher ASPs and service contracts.
- Specialized implanter and service providers are expanding their footprint by bundling processing services with equipment sales, creating hybrid commercial models that lower adoption friction for capital‑constrained customers.
Recent product launches and order flows underscore that incumbents are doubling down on modular platforms, higher throughput configurations, and service ecosystems — strategies that raise the bar for new entrants but create defined partnership pathways for niche innovators.
How to Use This Preview in Your 2026 Planning Cycle
For executive teams building 2026 strategic plans, this preview frames three immediate actions:
- Embed ion beam technological scenarios in capital planning: include upside/cushion scenarios tied to photonics and research capital cycles, not just mainstream fab investments.
- Update procurement and supplier strategies to reflect material source risk: run stress tests on gallium and alternative ion lines and prioritize multi‑source qualification.
- Allocate R&D and commercial resources to software and service offerings that convert cyclical hardware revenue into recurring annuities.
PW Consulting’s full report supplies the numbers, supplier maps, and decision tools required to operationalize each recommendation and quantify trade‑offs under a range of demand conditions.
Next Steps — Accessing the Full Report
This strategic preview is intentionally selective: it communicates the high‑level market trajectory and the decision levers that matter to leaders in 2026, while preserving the granular segment and vendor intelligence that forms the core of our premium analysis. For procurement teams, corporate strategists, and investors seeking the full dataset — including per‑segment forecasts, regional dynamics, and downloadable financial models — please visit the PW Consulting report page to license the complete Ion Beam Machining Market report and associated toolkits.
PW Consulting stands ready to support bespoke workshops, scenario stress tests, and M&A due diligence engagements that translate the report’s insights into executable 2026 strategies. Contact our industry team to schedule a briefing and receive a tailored package that aligns with your short‑ and medium‑term objectives.
For detailed analysis of this topic, please visit the official page: Ion Beam Machining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 6.25% CAGR for Global ESD Grounding Mats Market Through 2032
By pmarketresearch, 2026-08-18
ESD Grounding Mats Market — Strategic Imperatives for 2026: PW Consulting Executive Brief
As manufacturers, procurement leads, and strategic planners prepare capital and product roadmaps for 2026, the ESD grounding mats market is asserting itself as a quietly dynamic segment with clear implications for operations, compliance, and margin management. PW Consulting’s latest market study — synthesizing historical performance through 2025 and forward-looking scenarios to 2032 — provides the evidence base organizations need to make prioritized, risk-aware decisions next year. This executive brief outlines the report’s strategic value, highlights the forces shaping 2026 decision windows, and offers a concise playbook for executives. (Note: this preview demonstrates analytical depth while reserving the full segment-level detail for the full report.)
Fuke Zhidai Pian Market
Market snapshot: growth trajectory and competitive structure
The ESD grounding mats market has shown steady expansion over the past half-decade, increasing from an estimated USD 235.0 Million in 2020 to USD 315.5 Million in 2025. Our base-case forecast projects continued expansion in 2026 and beyond, with the market expected to reach approximately USD 332.6 Million in 2026 and to grow to roughly USD 482.3 Million by 2032 — reflecting a compounded annual growth rate of about 6.25% across the forecast window. These numbers reflect broad-based demand drivers and moderate pricing power in a market that remains fragmented: the three-largest players account for under one-third of market share, while the top five control less than 40%, indicating room for consolidation, differentiation, and local incumbency advantages.
Luxury Cross Door Refrigerator Market
Why 2026 matters: converging drivers that create a decision inflection
-
Standards and compliance are tightening. ANSI/ESD S20.20 and IEC 61340-5-1 remain the operative frameworks driving procurement specifications. In parallel, guidance such as ANSI/ESD TR20.20 effectively mandates daily verification of footwear and mat grounding systems in many electronics assembly environments — elevating the importance of traceable verification and service-level warranties.
Flip Chip Packages Market -
End-market tailwinds are reinforcing demand. Continued investment in semiconductor and electronics manufacturing capacity, together with medical and aerospace production requirements, underpins steady mat replacement and upgrade cycles.
-
Input-cost pressure is nontrivial. Natural rubber benchmark prices and synthetic rubber indices have firmed, with spot observations showing natural rubber around the USD 2.40/kg mark in parts of Northeast Asia and elevated producer-price indices for synthetic rubber variants. This creates a test case for price recovery mechanisms and material substitution strategies.
-
Product differentiation is shifting from material composition alone to tested, certified systems. The recent rollout of serialized testing and certification kits and the publication of updated selection guides show that customers increasingly value provable, auditable performance over commodity pricing.
What the full report delivers (practical, operational content)
Pitched to support procurement directors, product managers, and corporate strategists, the full PW Consulting ESD Grounding Mats Market report is built around operational utility rather than academic segmentation alone. Key deliverables include:
-
Validated market sizing and forward scenarios (2020–2032) with stress-tested sensitivity to input-cost shocks and demand slippage.
-
Regulatory and test-protocol playbook clarifying compliance obligations (ANSI/ESD, IEC frameworks) and practical verification cadences for shop-floor implementation.
-
Buying and sourcing toolkit: supplier scorecards, total cost of ownership (TCO) models, and contract clauses to manage raw-material pass-throughs and quality warranties.
-
Commercial templates for service-led monetization: certification-as-a-service, serialized test records, and aftermarket replacement programs.
-
Acquisition and partnership screening — a prioritized list of capabilities that make for attractive tuck-ins or alliances (e.g., test-serialization, localized manufacturing, specialty compound formulations).
To preserve strategic value for decision-makers, the report reserves detailed sub-segment shares and region/application splits for subscribers — providing the directional narrative here while ensuring the full data set remains a decision-enabling asset.
Competitive landscape: what incumbent and challenger strategies tell us
The market features a mix of large diversified industrial players and specialized niche manufacturers. Leading examples demonstrate how different strategic postures shape market positioning:
-
Desco Industries Inc. (incl. SCS) — a long-standing leader offering ANSI/ESD-compliant vinyl and rubber dissipative products and a strong technical messaging play around standards adherence. Strengths: established channel relationships, recognized compliance expertise, vertical product range for worksurfaces and floors.
-
ACL Staticide Inc. — known for resilient dual-layer and homogeneous mat constructions with chemical and heat resistance. Strengths: product engineering and laboratory-oriented value propositions that appeal to high-reliability verticals.
-
Botron Company Inc. — differentiates with multi-layer rubber designs (including exclusive 3-layer constructions) and ergonomics-focused floor mat offerings. Strengths: durability claims and ergonomic product development.
-
NoTrax (Justrite Safety Group) — brings broader industrial safety portfolio leverage to ESD anti-fatigue and anti-static mat lines, enabling bundled safety+ESD offers to manufacturing customers.
-
3M — leverages its larger static-control portfolio and distribution reach to sell integrated ESD protection solutions; strength is the ability to package mats with broader ESD program services and materials.
Recent industry moves underscore a growing emphasis on certification and selection guidance: in December 2025 a vendor introduced serialized, individually-certified bench mat kits; in early 2026, a prominent mat supplier published an updated selection guide aligned with IEC 61340; and in 2025 a technical body released practical testing-frequency guidelines. These trends favor suppliers who can combine product quality with traceable verification and buyer education.
Strategic playbook for 2026 (prioritized actions)
-
For manufacturers: Move from a pure product-sale model to a product-plus-certification model. Invest in serialized testing capability, certificate management platforms, and clearly marketed verification services. This supports premiuming and lowers price elasticity.
-
For procurement: Reassess sourcing strategies to mitigate rubber-price risk: negotiate flexible index-linked pricing, introduce multi-year hedges where appropriate, and evaluate alternative compounds (SBR/EPDM blends) with full TCO analysis that includes lifecycle replacement and compliance costs.
-
For product leaders: Prioritize modular mat systems that reduce SKU complexity while allowing customization for key verticals (electronics, aerospace, healthcare). Consider anti-microbial and wipe-down-friendly laminates for healthcare and lab environments as a differentiator.
-
For investors / M&A teams: Target acquisitions that provide serialized testing capabilities, local manufacturing footprints in high-growth manufacturing clusters, or proprietary compound formulations. Given the market’s fragmentation and sub-40% top-five concentration, well-executed tuck-ins can quickly accrete market share and margin.
-
For compliance and operations teams: Formalize daily verification routines and digital record-keeping consistent with ANSI/ESD TR20.20 guidance. Building transparent audit trails not only reduces failure risk but creates aftermarket services opportunities.
Investment implications and risk management
-
Opportunities: Service-led revenue streams (certification, scheduled testing), premium differentiated materials, and consolidation-driven margin expansion.
-
Risks: Input-cost volatility (natural and synthetic rubber), regulatory non-compliance exposures, and margin compression from low-cost global entrants. The supply-chain impact of rubber-price inflation is tangible and calls for contract-level mitigants and supplier diversification.
-
Mitigants: Indexed pricing clauses, dual sourcing, localized production where logistics and lead-time sensitivity demand it, and product warranties tied to documented verification regimes.
How PW Consulting’s report supports 2026 decision cycles
Leaders must balance near-term operational resilience against medium-term strategic positioning. Our report converts market forecasting into executable decision support: scenario-tested budgets for capital procurement, prioritized product investments, and a short list of candidate targets for inorganic growth. Importantly, it provides templates you can operationalize within 60–120 days across procurement, compliance, and product teams.
For teams that require immediacy: the report’s appendices include sample contract language for raw-material pass-throughs, a compliance verification checklist aligned to ANSI/ESD and IEC standards, and a supplier scorecard tailored to evaluate both product performance and service capability (including the ability to deliver serialized certification).
Conclusion — the tactical horizon for 2026
2026 will reward organizations that convert compliance pressure and material-cost volatility into structured commercial advantage. Those that unify product quality with auditable verification, hedge input risks, and pursue selective capability acquisitions will capture outsized share and margin gains. PW Consulting’s full ESD Grounding Mats Market report is designed to be an operational companion for those moves — delivering the proprietary sub-segment data, supplier maps, and scenario toolkits that are intentionally summarized here to preserve strategic utility.
Access the full analysis to obtain the detailed regional, material, and application breakdowns, along with the proprietary models we used to stress-test 2026 scenarios. PW Consulting stands ready to support tailored strategy workshops, acquisition screening, and procurement playbook rollouts to translate insight into action.
For detailed analysis of this topic, please visit the official page: ESD Grounding Mats Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com