

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide C5 Resin Market to Rise from USD 2,860 Million in 2025 to USD 3,794 Million by 2032 at a 4.12% CAGR

Worldwide C5 Resin Market: Strategic Imperatives for 2026 — PW Consulting Preview
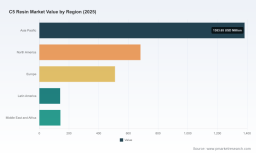
As companies prepare capital allocation, procurement realignment, and product strategy for 2026, PW Consulting publishes an executive preview of our forthcoming Worldwide C5 Resin Market report. Our analysis shows the global C5 resin market—measured on a USD million revenue basis—moving from an estimated USD 2,860 million in the 2025 base year toward roughly USD 3,794 million by 2032, representing a compound annual growth rate (CAGR) of approximately 4.12% across the 2026–2032 forecast window. This trajectory reflects steady, commercially relevant growth driven by adhesive tackifier demand, evolving rubber compounding needs, and paint & coating formulations shifting toward engineered hydrocarbon solutions.
Agriculture Accounting Software Market
Why this report matters to 2026 decision-makers
-
Actionable clarity in a period of structural change: Many procurement and strategy teams enter 2026 confronting regional supply imbalances and regulatory uncertainty. Our report synthesizes supply-side moves, feedstock trends, and trade policy impacts into decision-ready insights for sourcing, inventory policy, and regional footprint planning.
Bone Resorption Inhibitors Market -
Investment screening and M&A prioritization: With a moderately concentrated supplier base at the top and a fragmented second tier, the landscape is ripe for strategic bolt-on acquisitions, joint ventures, or capacity redeployment. We show which asset types and geographies will deliver the most defensive value under three downside scenarios.
Worldwide Supply Chain Cost-To-Serve Analytics Software Market -
Commercial optimization for formulators and converters: For OEMs and adhesives/rubber formulators, the report provides an applied toolkit—tackifier substitution roadmaps, cost-to-performance matrices, and risk-weighted supplier scorecards—that reduce adoption friction and accelerate qualification cycles.
Market dynamics shaping the 2026 agenda
-
Supply rebalancing and regional flow shifts: Recent industry events have accelerated regional imbalances. North American hydrogenated resin line rationalization has pushed the region toward increased dependence on imports, while Asia continues to add new resin-making capacity. These flows are being reshaped by both commercial choices and policy instruments.
-
Trade and tariff noise: Targeted trade measures remain a material influence on global trade patterns. Ongoing Section 301 tariffs and the partial unwinding of broader controls in 2026 have altered flows and created near-term arbitrage opportunities—important for procurement teams evaluating supplier diversification versus localized stocking.
-
Feedstock and cost stability: C5 feedstock availability, derived from naphtha and cracker streams, exhibited relative price stability in late 2025. That calm provides a window for forward procurement contracts and structured hedges, but volatility can re-emerge if cracker utilization or heavy petrochemical maintenance cycles change.
-
Domestic capacity growth in Asia: New lines and brownfield expansions in Asia are recalibrating the global cost curve and delivery lead times. For buyers, the strategic question is whether to lock in long-term supply from incumbent integrated suppliers or shift to emerging producers that are scaling quickly.
-
Product mix and formulation trends: Demand for higher-performance and hydrogenated variants continues within specialty adhesives, pressure-sensitive formulations, and advanced rubber compounds. That trend raises the bar for quality- and specification-driven supply chains and supports premiumization of certain resin grades.
Competitive landscape: players, strategic moves, and implications
-
Eastman Chemical Company (USA) — A well-capitalized supplier with a broad portfolio of aliphatic and hydrogenated C5 resins. Eastman’s integrated position and technical service capability make it a preferred strategic partner for adhesive formulators seeking rapid scale-up and global technical support.
-
Kolon Industries, Inc. (South Korea) — A leading regional producer with deep capabilities in high-purity C5 resins and hydrogenated grades. Kolon’s investments in higher-purity product lines signal an intent to capture specialty pockets where performance and consistency command premium pricing.
-
ExxonMobil Corporation (USA) — A major traditional supplier whose selective shutdowns and portfolio adjustments have immediate market ripple effects. Recent capacity rationalization in hydrogenated lines has contributed to upstream sourcing challenges for North American buyers, underscoring the need for contingency planning.
-
Zeon Corporation & Arakawa Chemical (Japan) — Technology-focused producers that serve high-performance adhesive and elastomer markets; their product breadth supports formulators requiring tight grade control and tailored tackifier performance.
-
Neville Chemical, Cray Valley (TotalEnergies), and a cluster of Chinese producers — These firms complete a competitive tapestry of global incumbents and agile regional suppliers. China-based manufacturers have visible momentum in expanding scale and global reach; this has implications for pricing dynamics and lead-time optimization.
-
Market concentration signals — The market exhibits moderate top-tier concentration, with the three largest producers capturing a meaningful share but leaving substantial room for mid-sized and regional suppliers to compete. This structure increases the value of differentiated service models and localized supply guarantees.
Recent developments that will matter in 2026
-
Regulatory and corporate restructuring in Asia has prompted portfolio reviews among downstream chemical players; consolidation and strategic repositioning in Korea and Japan are affecting regional feedstock allocations and partnering strategies.
-
Targeted capacity expansions and brownfield upgrades by established players are creating differentiated capability clusters—some focused on high-purity specialty resins, others on broad commercial grades—changing the competitive match-up across applications.
-
Significant plant line closures for hydrogenated grades in North America have altered net trade balances, emphasizing the importance of import strategies, tolling arrangements, and safety-stock policies for 2026.
What the PW Consulting report delivers — practical modules
-
Market sizing and validated forecast model (2020–2032) with scenario toggles: our financial model is built in a way that allows executives to stress-test demand elasticity and price pass-through under alternative macro cases.
-
Segment diagnostics and opportunity mapping: deep dive playbooks for resin types (aliphatic, copolymer, hydrogenated) and end-use clusters that identify margin pools, qualification timelines, and go-to-market mechanics.
-
Supplier heatmaps and risk-adjusted sourcing templates: a procurement-ready framework combining lead-time volatility, quality fit, regulatory exposure, and commercial flexibility.
-
Trade-flow and tariff impact analysis: dynamic routing scenarios that quantify shifts in logistics cost and landed price under prevailing trade measures and alternative tariff outcomes.
-
Technical substitution and product migration guides: stepwise plans to migrate formulations between resin grades with minimal requalification cycles and cost disruption.
-
M&A, JV and capex playbooks: acquisition targets, integration checklists, and capex prioritization matrices tailored to buyers and strategic investors active in the hydrocarbon resin ecosystem.
Recommended 2026 strategic actions — five high-impact moves
-
Formalize dual-sourcing for critical grades: prioritize at least one regional and one global supplier to mitigate delivery shocks from unexpected plant outages or policy shifts.
-
Implement a short-duration forward purchasing program tied to cracker utilization indices: take advantage of the current feedstock calm to secure favorable terms without overexposing balance sheets.
-
Prioritize qualification of hydrogenated and high-purity variants for premium end-markets: these grades offer better margin defensibility where performance matters.
-
Reassess inventory strategy in light of trade frictions: shift from pure cost-minimization to resilience-weighted inventory targets for facilities serving multiple plants or markets.
-
Use M&A/JV selectively to obtain quick access to local capacity or downstream channel control—but only against rigorous IRR and integration metrics provided in our acquisition playbook.
How to use the full report
This release is intended as a strategic preview: it articulates the high-level market trajectory, the levers that matter in 2026, and the playbook executives should adopt to protect and grow margin. The full PW Consulting Worldwide C5 Resin Market report contains the granular segment-level data, regional and application splits, supplier scorecards, and downloadable financial models that boards, strategy teams, and procurement leaders will find indispensable when making binding 2026 decisions. We deliberately withhold the detailed subsegment datapoints in this preview to ensure that organizations seeking immediate operational guidance consult the complete dataset and model hosted on our site.
Conclusion
The C5 resin market in 2026 is neither a classic boom narrative nor a stagnant commodity story—it is a slowly expanding, structurally shifting market where the winners will be those that pair technical differentiation with supply-chain resilience. PW Consulting’s report equips executives with the foresight and the operational tools required to convert the coming changes into competitive advantage. For the authoritative dataset, scenario models, and supplier-level playbooks, access the complete Worldwide C5 Resin Market report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Worldwide C5 Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com