

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Industrial Press Machine Market to Expand at a 5.18% CAGR Through 2032

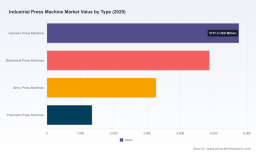
PW Consulting: Strategic Brief — Worldwide Industrial Press Machine Market (2026 Outlook)
PW Consulting today publishes a strategic briefing drawn from our new Worldwide Industrial Press Machine Market report — a practitioner-focused intelligence asset designed to shape capital allocation, product strategy, and M&A decisions through 2026 and beyond. Using 2025 as the analytical base year, our global market system is tracked in USD (Million) with a projected compound annual growth rate (CAGR) of 5.18% across the forecast horizon. The market expanded meaningfully through 2020–2025 and, under our central scenario, progresses toward a materially larger installed base and serviceable market by 2032.
Corporate Travel Booking Platforms Market
Why this matters for 2026 corporate strategy
-
Timing capital: With moderate, steady growth and pockets of accelerated investment, 2026 is a year where the sequencing of capital projects — greenfield presses versus retrofit and automation programs — will determine total cost of ownership and payback periods.
Electric Train Battery Market -
Input-cost sensitivity: Steel-market dynamics and trade policy introduced higher near-term uncertainty in 2025. Organizations that proactively hedge raw-material exposure and redesign supply chains to reduce steel-intensive content will protect margins.
Worldwide Electro-optical Converters Market -
Technology pivot points: The migration to servo-driven systems and integrated automation is no longer niche; it is reshaping buyer selection criteria around precision, energy efficiency, and digital integration.
-
Aftermarket economics: Service, spare parts, and retrofit revenues are becoming essential to sustaining margins as equipment lifecycles lengthen and customers seek guaranteed uptime under tighter production schedules.
What PW Consulting’s report delivers
-
Robust market sizing and forward-looking scenario analysis, calibrated to market events through the 2025 base year and projecting to 2032 with multiple demand scenarios and sensitivity cases tied to raw-material and trade-policy assumptions.
-
Practical go-to-market playbooks for OEMs and component suppliers — from product positioning and pricing levers to channel design, local-assembly thresholds, and retrofit service bundling.
-
Procurement and supply-chain stress tests, including break-even analyses for vertical integration versus global sourcing, and supplier concentration mapping to identify single points of failure.
-
Competitive benchmarking with vendor scorecards across engineering capability, automation integration, aftermarket footprint, and balance-sheet resilience.
-
A curated M&A pipeline and diligence checklist highlighting acquisition targets likely to accelerate access to key end-markets, digital capability, or regional manufacturing scale.
-
Operational playbooks for manufacturers and end-users — CAPEX prioritization grids, retrofit vs. replace matrices, and pilot-to-scale templates for automation deployment.
Competitive landscape: who matters and why
The market remains moderately fragmented, with concentration metrics indicating space for scale plays: the top three firms capture a meaningful but not overwhelming share, and the top five firms broaden that concentration band further. This structure creates both opportunity for consolidation and room for specialized players to defend niches.
-
Schuler Group (Göppingen, Germany) — A broad-spectrum supplier of mechanical, hydraulic, and servo presses. Schuler’s global service footprint and deep OEM relationships in high-volume stamping make it a reference player for full-line systems and turnkey lines.
-
AIDA Engineering (Japan) — High-precision mechanical and servo presses oriented to high-speed stamping. AIDA’s engineering reputation positions it well where cycle time and die-life economics dominate procurement choices.
-
Amada (Japan) — Known for sheet-metal forming equipment and automation, Amada’s product breadth in punching and bending complements press makers who need to offer integrated cell solutions to contract manufacturers.
-
Komatsu Press (Japan) — Strong in heavy industrial stamping and automation-enabled solutions; Komatsu’s integration of presses with higher-tier material handling continues to win large-scale industrial projects.
-
Beckwood Press Company (St. Louis, USA) — Specialist in custom-engineered hydraulic and servo-electric presses. Beckwood is attractive for OEMs needing bespoke capabilities for composites, molding, or specialty forming.
-
Pacific Press Technologies (USA) — Focused on North American metal forming needs with a reputation for reliable hydraulic and straight-side presses and a strong OEM-aftermarket channel.
-
Macrodyne Press (North America) — Heavy-duty hydraulic presses for deep draw and hydroforming; the firm is strategically positioned for large-scale vehicle and industrial applications where scale and force are differentiators.
-
French Oil Mill Machinery Co. (USA) — Longstanding heritage in custom hydraulic presses, particularly in compression molding and rubber applications; an example of how specialized product competence sustains market niches.
-
Ermaksan (Turkey) — Offers CNC hydraulic and servo turret punch presses; presents an alternative for cost-conscious regional buyers seeking modern control systems.
-
Fagor Arrasate (Spain) — Supplies mechanical and hydraulic presses and full stamping lines; notable for turnkey solutions in automotive and appliance segments.
-
Sutherland Presses & Stamtec (USA) — Both bring manufacturing locality and trusted U.S.-made quality, appealing to buyers prioritizing short lead times and domestic support.
Supply-chain and input-cost dynamics shaping decisions in 2026
Two critical, observable forces are shaping supplier economics and pricing strategies heading into 2026. First, raw-material dynamics: steel prices stabilized in the low–mid ranges in mid-2025 and remain a key driver of frame and component costs. Second, trade policy changes — most notably elevated U.S. steel tariffs implemented in 2025 — have created a bifurcated sourcing environment where domestic producers gain pricing support but import-dependent players face higher input costs. Coupled with structural overcapacity in global steel markets, these dynamics argue for differentiated procurement playbooks: tactical hedges for near-term volatility and strategic reconfiguration of BOMs and subassembly sourcing for medium-term resilience.
Technology & product trends that will re-write competitive scorecards
-
Servo and hybrid presses: Adoption is being driven by buyers demanding tighter tolerances, lower energy intensity, and better integration with digital controls. These systems are increasingly the default for precision stamping and higher mix–lower volume production profiles.
-
Automation and Industry 4.0 integration: Press lines are being sold as node-enabled assets — remote diagnostics, predictive maintenance, and line-level optimization are table stakes for premium OEMs and leasing offerings.
-
Modularity and retrofitability: Product families that allow incremental capability upgrades (controls, drives, safety) dramatically improve customer ROI and create recurring aftermarket monetization opportunities.
Actionable takeaways for executives planning 2026
-
Recalibrate CAPEX: Prioritize mixed investments — small pilot projects in servo and automation plus targeted replacement of legacy assets that create bottlenecks.
-
Design supplier risk playbooks: Implement dual-sourcing strategies for critical steel components and evaluate nearshoring of final assembly where tariffs and lead time exposures are material.
-
Monetize installed base: Build service tiers (SLA-backed uptime, condition-based maintenance) to convert fixed-cost installed assets into recurring-revenue streams.
-
Segment go-to-market by capability: Use differentiated sales motions for high-volume automotive stamping versus precision electronics forming; standardize offerings where possible and modularize where necessary.
-
Accelerate partnerships with automation integrators and controls suppliers to shorten time-to-value for buyers and create bundled greenfield and retrofit propositions.
-
Evaluate M&A for capability gaps: Target acquisitions that immediately add digital controls, regional service networks, or material-handling expertise to close visible gaps in competitive scorecards.
Recent market activity and signals
Industry events and product showings continue to validate the market momentum and technology transition. For example, machine builders participated in major manufacturing exhibitions in early 2026 to showcase new forming and press-line integrations — a reminder that OEMs are actively pursuing visibility and order pipelines as end-users refresh assets.
Why PW Consulting’s report is the decision tool for 2026
Our report combines transparent, auditable methodology with practitioner tools: demand-model Excel workbooks, vendor scorecards, stress-test scenarios, and a prioritized action checklist. We balance high-level foresight (macro demand and trade impacts) with hands-on levers (procurement negotiation scripts, retrofit ROI calculators, and go-to-market templates) so that executives do more than understand the market — they act on it.
This briefing intentionally highlights strategic themes and decision-relevant insight while reserving the granular segment tables, regional breakdowns, and line-item supplier economics for the full report and accompanying datasets. Industry leaders and buyers who require the detailed segmentation, downloadable models, and vendor-level financials will find those deliverables in the full PW Consulting publication and Excel annex.
For executives preparing 2026 plans, the choice is straightforward: rely on high-level intuition, or use a field-tested, data-driven playbook that aligns capital, capability, and go-to-market efforts against the real levers that move margin and market share. PW Consulting’s Worldwide Industrial Press Machine Market report delivers the latter.
Contact and access
PW Consulting’s market research and advisory teams are available to present bespoke briefings, workshop CAPEX scenarios, or support vendor diligence. Access to the full report, annex data files, and proprietary models is available through PW Consulting’s publication channels.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Press Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com