

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hermetic Packages Market to Expand from USD 4,500 Million in 2025 to USD 7,017 Million by 2032 at a 6.55% CAGR — Ceramic Segment Leads with USD 2,240 Million

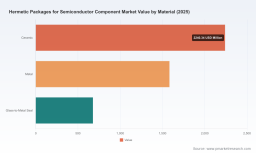
Hermetic Packages for Semiconductor Component Market — Strategic Imperatives for 2026
PW Consulting today publishes an executive briefing tied to our full market study, "Hermetic Packages for Semiconductor Component Market" (base year 2025, forecast 2026–2032). The briefing synthesizes the report’s most consequential findings for corporate leaders preparing budget cycles, product roadmaps and supply‑chain reconfiguration in 2026. Our analysis is grounded in a consistent historical dataset (2020–2025) and a forward projection that assumes a compound annual growth rate (CAGR) of 6.55% across the forecast window. In simple scale terms, the market expanded from USD 3,250 Million in 2020 to USD 4,500 Million in 2025 and, under our baseline model, approaches USD 7,017 Million by 2032.
Ship-specific Display Market
Why 2026 is a Strategic Inflection Point
Several converging forces make 2026 the year when strategy becomes execution for hermetic packaging suppliers, semiconductor OEMs and systems integrators:
Vitamin K2 Market
- Technology-driven demand: Continued miniaturization, the thermal and reliability demands of high‑power AI accelerators, and expansion of mmWave RF devices are increasing the technical bar for hermetic solutions.
- Regulatory and qualification pressure: High‑reliability sectors — aerospace, defense and medical — continue to require MIL‑STD and Class H/K level qualifications, elongating time‑to‑market and raising the cost of design changes.
- Supply‑chain resilience and geopolitics: Onshoring initiatives and industrial policy measures aimed at securing critical semiconductor supply chains are reshaping investment incentives for domestic hermetic package capacity.
- Materials and thermal engineering: Adoption of advanced materials (for example AlSiC for thermal management and multilayer ceramic cores to reduce warpage) is shifting supplier specializations and BOM economics.
For 2026 planning, these dynamics translate into specific boardroom priorities: accelerate qualification programs for next‑generation packages, protect roadmap timelines from supplier concentration risk, and prioritize design for hermeticity early in the silicon/package co‑development cycle.
Fresh Onions and Shallots Market
Market Trajectory: What the Numbers Mean for Decision Makers
Our base‑case projection (CAGR 6.55%) embodies a market that is expanding steadily rather than exploding. That growth profile creates a different set of strategic choices than a rapidly hyper‑growing market: suppliers and OEMs must synchronize capacity investments with medium‑term demand certainty, avoid overbuild in narrow subsegments, and carve out higher‑margin niches through specialty materials, qualification services and design‑for‑reliability offerings.
- Capacity planning: Given the moderate but persistent growth trajectory, incremental capacity additions that emphasize flexibility (modular lines, multi‑material process capability) are preferable to single‑purpose greenfield plants.
- R&D and IP: Investing in material science (ceramics, glass‑to‑metal seals, AlSiC composites) and process IP that reduce qualification cycles will yield outsized returns in high‑reliability markets.
- Commercial models: Value‑added services — qualification partner programs, accelerated testing, and custom build‑to‑print options — create differentiation in a market where commoditization pressure exists in standard form factors.
Full segmented demand curves by region, material and application are included in the full report; intentionally, this briefing omits those granular splits to drive direct engagement with the source material for procurement and strategy teams building business cases.
What the Full Report Delivers — Practical, Actionable Tools
We designed the report for use in 2026 planning cycles. Key deliverables include:
- Quantitative demand model (2020–2032) with scenarios (baseline, upside, downside) and sensitivity levers to test price, qualification time, and adoption rates for new materials.
- Supplier scorecards and capability maps assessing process breadth (ceramic HTCC, glass‑to‑metal, AlSiC brazing, molded ceramic), qualification throughput, and geopolitical supply‑chain exposure.
- Go‑to‑market playbooks for suppliers targeting aerospace/defense, medical and AI/high‑power markets — including sales motion, certification roadmaps and sample‑to‑production timelines.
- CapEx prioritization and ROI templates calibrated for the industry’s unit economics and lead‑time realities.
- Regulatory compliance matrix and accelerated qualification checklists for MIL‑STD and Class H/K pathways.
- Design‑for‑hermeticity best practices and yield optimization guidance for packaging engineers collaborating with fab partners.
These deliverables are explicitly practical — designed to be imported into procurement RFPs, product development Gantt charts and board‑level capital allocation models.
Competitive Landscape: Strategic Profiles and Implications
The market comprises a mix of material specialists, vertically integrated fabricators and niche engineered‑product companies. Our competitive analysis covers a representative set of leaders and innovators; the full report contains extended company profiles and comparative scorecards. Selected strategic observations follow:
- SCHOTT AG (Mainz, Germany) — Strength: deep expertise in hermetic microelectronic packages and hybrid solutions. Strategic implication: well‑positioned to lead cross‑border programs where integrated optical/glass solutions are required; prospective partners should evaluate SCHOTT for co‑development where glass hermeticity is a differentiator.
- AMETEK Inc. (Aegis / Hermetic Seal) (USA) — Strength: glass‑to‑metal seals and flatpack heritage for defense/aerospace. Strategic implication: a natural supplier for programs requiring long lifecycle support and high‑reliability traceability; consider long‑term supply agreements to secure capacity for defense contracts.
- Kyocera Corporation (Japan) — Strength: multilayer ceramic hermetic packages and recent commercialization of multilayer ceramic core substrates to mitigate warpage. Strategic implication: semiconductor OEMs pushing advanced packaging (AI and high‑power) should evaluate Kyocera as a materials partner to solve warpage and co‑packaging thermal challenges.
- Electronic Products Inc. (EPI) (USA) — Strength: vertical integration across HTCC ceramic and glass‑to‑metal hermetic processes. Strategic implication: attractive partner for OEMs seeking single‑source qualification and shorter supply chains; useful in onshoring strategies.
- Complete Hermetics (USA) — Strength: bespoke hermetic packages and a recent product refresh emphasizing RF, MEMS and power applications. Strategic implication: ideal for prototyping and low‑volume high‑mix programs where customization and rapid iteration matter.
- CPS Technologies Corporation (USA) — Strength: AlSiC hermetic solutions with thermal management focus. Strategic implication: suppliers and OEMs targeting high‑power modules should assess CPS for thermal subsystem integration.
- StratEdge Corporation (USA) — Strength: fully hermetic molded ceramic packages optimized for microwave/mmWave up to ~18 GHz. Strategic implication: positioned to capture share from 5G/6G infrastructure and automotive radar programs.
- Materion Corporation (USA) — Strength: materials and lid covers, braze alloys essential to hermetic supply chains. Strategic implication: an upstream lever for manufacturers seeking material differentiation or supply security.
- Teledyne Technologies (incl. Micross) (USA) — Strength: system‑level assembly and hermetic packaging for space and medical. Strategic implication: a partner of choice where turn‑key assemblies and traceability are mandatory.
Across this competitive set, our analysis highlights two strategic playbooks that consistently outperform: (1) specialization in a narrowly defined reliability or frequency niche combined with accelerated qualification services, and (2) horizontal integration across materials and assembly to reduce vendor count for high‑assurance programs.
Risks, Scenarios and Strategic Responses
Key risks that should influence 2026 capital and partnership decisions include:
- Raw material volatility and single‑source dependencies (e.g., specialty alloys and composites used for thermal management).
- Qualification timeline overruns driven by stricter MIL‑STD/Class H/K testing and lengthening aerospace/space certification cycles.
- Geopolitical shifts that incentivize onshoring, altering comparative cost structures and creating short‑term capacity squeezes.
We model three scenarios in the full report: a baseline (CAGR 6.55%), an upside where defense/AI acceleration pushes near‑term adoption, and a downside where substitution and longer qualification drag growth. For corporate planning, we recommend stress‑testing financial models against the downside for procurement lead times and the upside for capacity constraints to avoid being caught undercapacity or overleveraged.
How to Use This Intelligence in 2026 Planning
Leaders assembling 2026 budgets should treat hermetic packaging not as a commodity line item but as a strategic node that affects product reliability, time‑to‑field and program margins. Practical steps we recommend this planning season:
- Start qualification conversations now: move early into qualification lanes with at least two suppliers to shorten contingency lead times.
- Adopt modular capacity investments: prefer flexible investments that can be redeployed across materials and form factors.
- Negotiate outcome‑based contracts: link pricing to yield and qualification milestones to align supplier incentives.
- Invest in co‑engineering: internal packaging and reliability engineers should be embedded with supplier teams during prototype stages.
Next Steps — Accessing the Full Intelligence
This briefing is intentionally concentrated on strategic implications and programmatic actions; the full PW Consulting report contains the granular market tables, regional and application splits, comprehensive company scorecards and the downloadable demand model used to generate our forecasts. If your 2026 planning requires vendor shortlists, supplier risk heat maps, or the scenario model exported to your financial templates, the full report and data packs are available through PW Consulting’s market research portal.
For boards, procurement committees and R&D leaders entering the 2026 planning season: hermetic packaging will not be a back‑office detail. It is a determinative factor in program timing, reliability and total cost of ownership. Our analysis provides the calibrated market view and tactical toolset to convert growth into profitable, defendable market share — but the specific segmentation tables and supplier benchmarking you need to operationalize these recommendations are held in the full report.
Contact PW Consulting to arrange a briefing of the full dataset, request customized seg‑by‑application scenarios, or commission a tailored supplier due‑diligence engagement calibrated to your program timelines.
For detailed analysis of this topic, please visit the official page: Hermetic Packages for Semiconductor Component Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com