

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Recycled Containerboard Market Valued at USD 146.5 Billion in 2025, Set to Expand at a 4.69% CAGR Through 2032

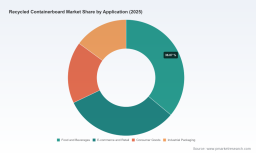
Recycled Containerboard Market 2026: Strategic Imperatives from PW Consulting’s Latest Industry Report
PW Consulting today releases a comprehensive market research briefing on the global Recycled Containerboard market, purpose-built to inform the strategic decisions of corporate leadership and investors for 2026. The report synthesizes a multi-year view of supply, demand, policy and feedstock dynamics and translates those into operational playbooks, capital-allocation guidance and near-term scenario options. This press briefing presents the report’s strategic value proposition, high‑level market trajectory and the decision levers that business leaders should prioritize this year. For full segmentation, granular regional and application breakdowns, and proprietary model outputs, please consult the full report.
General Metal Finishing Solutions Market
Market Snapshot: Growth Measured, Transition Underway
Our analysis shows the recycled containerboard market as a large, steadily expanding sector. By our base year (2025) the market reached approximately USD 146.5 Billion and the forecast envelope points to continued expansion at a compound annual growth rate of roughly 4.69% through 2032, taking the market to about USD 201.9 Billion by the end of the forecast period. That trajectory underlines a structural growth theme driven by packaging substitution toward recycled fibre, rising e‑commerce-related packaging volumes, and regulatory pushes toward higher recycled content.
Car Sharing App Market
However, aggregate growth masks two critical realities that will shape 2026 strategy. First, feedstock and manufacturing ecosystems remain cyclical and regionally differentiated: recovered paper availability and pricing volatility can compress margins quickly, and second, regulation and buyer-specification shifts are increasingly decisive for market access and premium positioning. The report marries the macro growth narrative with these operational frictions so decision makers can translate top‑line opportunity into executable near‑term plans.
Precious Metal Evaporation Materials Market
Why the 2026 Planning Cycle Is Different — and What to Do About It
- From volume to value: As recycled containerboard becomes a default choice for many corrugated applications, margin capture increasingly depends on product-performance differentiation (weight, printability, flatness) and supply-security assurances rather than pure tonnage growth. Executive teams should realign commercial incentives and investments to monetize differentiated recycled grades.
- Regulatory inflection points are immediate: Extended Producer Responsibility (EPR) frameworks are moving from proposal to implementation in multiple jurisdictions, with some laws now specifying significant minimum post‑consumer recycled content. This changes procurement math for brand owners and creates new demand signals for manufacturers who can guarantee compliant content and chain-of-custody documentation.
- Feedstock risk is corporate risk: Recovered paper markets showed signs of rebound in early 2026 after a soft patch in late 2025; even modest swings in OCC availability or price transmission materially impact thin‑margin recycled grades. Procurement, hedging and asset flexibility must be hardwired into 2026 plans.
- Operational tightness coexists with selective capacity expansion: Despite near‑term production variability in some regions, many producers are selectively investing in recycled grades and machine rebuilds. Companies must weigh the long lead times and payback profiles of converted or new recycled machines against the competitive benefit of first‑mover capacity in underserved corridors.
What PW Consulting’s Report Delivers — Hands‑On, Actionable Intelligence
Our research is designed to be operational: not an academic forecast but a decision‑support tool. Key deliverables inside the report include:
- Proprietary market sizing and a scenario matrix that links macro demand trajectories to feedstock availability and pricing sensitivities.
- Commercial playbooks for sellers and buyers — pricing architecture, specification migration paths, and supply‑contract templates tailored for recycled fibre supply chains.
- Capital allocation frameworks for mill owners and converters: break‑even mappings, retrofit prioritization, and greenfield vs conversion decision trees with IRR and payback sensitivities under multiple feedstock and price paths.
- An M&A and JV playbook identifying strategic pockets (tech-enabled deinking, local closed‑loop models, high‑brightness recycled liner) and the financial profile of value creation levers that acquirers should target.
- Operational benchmarking and a plant‑level diagnostic toolkit covering yield, fibre loss, water and energy intensity, and quality‑control levers that materially affect paper performance for customers.
- Regulatory readiness tools: a compliance checklist for EPR regimes, product labeling implications, and supplier traceability templates to support procurement teams and sustainability reporting.
Each section is supported by primary interviews with mill operators, converters and major buyers, plant‑level audits and a bottom‑up demand model calibrated to 2020–2025 historicals and 2026–2032 forecast scenarios.
Competitive Landscape: Who’s Competing on What
The recycled containerboard market remains moderately fragmented: global leadership is distributed among vertically integrated pulp and paper majors, regional specialists, and independent recycled-only operators. Competitive advantage today is built on three capabilities — consistent recycled feedstock procurement, product performance engineering (weight, strength, printability), and integrated closed‑loop solutions for large buyers.
- International Paper — A major global participant with established recycled liner and fluting grades in its EMEA footprint; IP’s play emphasizes high‑performance lightweight grades that enable lower board weights without sacrificing performance.
- ND Paper — Focused on reliable strength and print quality for demanding packaging uses; ND’s asset base targets consistency as its primary commercial differentiator.
- Stora Enso — Highlights 100% recycled fibre testliner offerings with a product strategy around structural performance, flatness and low grammage for e‑commerce and industrial packaging customers.
- Cascades — Emphasizes a full recycled lineup across white and brown grades, pursuing both sustainability claims and surface quality improvement to capture premium applications.
- DS Smith — Positions high‑brightness 100% recycled white liners for FMCG and food applications where printability and visual appeal command price premiums.
- Kruger, New Indy, Pratt and others — Each occupies regional niches or scale positions: Kruger and New Indy have early mover recycled histories in North America; Pratt emphasizes closed‑loop systems; independent suppliers often lead on cost and customized services for localized demand.
- Mondi — Recently brought new recycled‑focused capacity online in Italy; the company’s approach illustrates how targeted capital projects can quickly alter regional supply balances for high‑quality recycled testliner and fluting.
Our competitive analysis goes beyond company positioning to evaluate capital intensity, technology adoption (deinking, refining, optimization), customer mix, and contractual exposure to feedstock and finished‑goods volatility. That analysis provides an M&A and partnership heat map for 2026 priorities.
Recent Industry Signals to Watch in 2026
- Several producers have brought recycled-dedicated machines and upgrades into production in the past 18 months, signaling continued industrial commitment to 100% recovered fibre offerings in priority regions.
- Procurement teams are reacting to recovered paper market dynamics: early 2026 saw a modest rebound in recovered paper availability and regional price stabilization after late‑2025 softness. Procurement strategies should incorporate shorter contract cycles and optionality clauses for feedstock supply.
- Regulatory change is accelerating buyer requirements. New EPR schemes and state‑level mandates are driving brand owners to demand verifiable recycled content and chain‑of‑custody documentation from suppliers; some jurisdictions have set explicit post‑consumer recycled content thresholds that will alter procurement specifications.
- Production metrics in some markets reflect a 2025 year‑on‑year reduction in output even as operating rates stayed high; this underlines the role of maintenance cycles and feedstock shortages in near‑term availability.
Practical Strategic Choices for 2026
Executives should treat 2026 as a year for tactical repositioning and capability building rather than only capacity race expansion. Key actions we recommend:
- Implement a three‑tier procurement strategy: secure core feedstock through anchor contracts, maintain a flexible spot overlay to capture opportunistic supply, and invest in or partner on local collection and sorting where economics permit.
- Prioritize product R&D on surface quality and weight efficiency to expand addressable applications and defend margins against commodity downward pressure.
- Stress‑test capital projects against three feedstock and price scenarios and incorporate regulatory compliance timelines into capex phasing to avoid stranded asset risk.
- Use the report’s M&A heat map to identify bolt‑on acquisitions that deliver either geographic feedstock security or product diversification (e.g., white‑top recycled liners or high‑brightness solutions for food packaging).
- Operationalize EPR readiness: upgrade labelling, chain‑of‑custody systems and customer reporting to convert regulatory compliance into a commercial differentiator.
Conclusion — The Strategic Edge in 2026
The recycled containerboard market is no longer a back‑office sustainability narrative; it is a core commercial battleground with clear profit pools for firms that can integrate feedstock security, product performance and regulatory compliance. PW Consulting’s report equips executive teams with the scenario analysis, operational templates and competitive intelligence required to make defensible 2026 decisions — from procurement and plant investments to M&A and customer contracts.
This briefing is a preview designed to show the depth of analysis and practical outputs the full report contains. To access detailed regional and application segmentation, proprietary pricing and margin models, and the complete suite of implementation tools referenced here, please visit PW Consulting’s report page and download the full Recycled Containerboard Market study.
For detailed analysis of this topic, please visit the official page: Recycled Containerboard Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com